Japanese Yen ignores every reason it has to strengthen
- The Yen held near a closely watched level for a third straight session despite supportive domestic news.
- Strong Japanese growth data and looming central bank tightening have not been enough to offset the Dollar.
- Intervention risk is climbing again just as oil and rate differentials pin the currency near its lows.
There is a strange disconnect running through the Japanese Yen right now, and USD/JPY parked just above 160.00 captures it perfectly. By any domestic reading the Yen should be firming: first-quarter Gross Domestic Product (GDP) beat expectations over the weekend at 0.5% on the quarter, the Bank of Japan (BoJ) is widely expected to raise rates at its meeting on June 18, and authorities have spent the past week jawboning a currency they clearly want stronger. Instead the pair is hovering at levels that dragged Tokyo into direct intervention back in April, a third consecutive session glued to the figure, and the path of least resistance still looks upward.
Why the good news bounces off
The reason is that none of the bullish-Yen inputs can compete with the two forces actually setting the price. The first is the interest rate gap. Friday's US Nonfarm Payrolls (NFP) report came in at 172K against a consensus near 85K, and the market responded by lifting the odds of higher US rates by December to around 72% on CME FedWatch, pricing the Federal Reserve (Fed) toward hikes rather than cuts and widening an already punishing yield differential against a BoJ that is tightening in slow motion from 0.75%. The second is energy. Japan imports roughly 95% of its Crude Oil from the Middle East, so the regional conflict that pushed Brent up more than 5% early Monday is a direct tax on the Yen, worsening the trade balance and importing exactly the inflation the BoJ keeps citing. A strong GDP print simply does not weigh much against that.
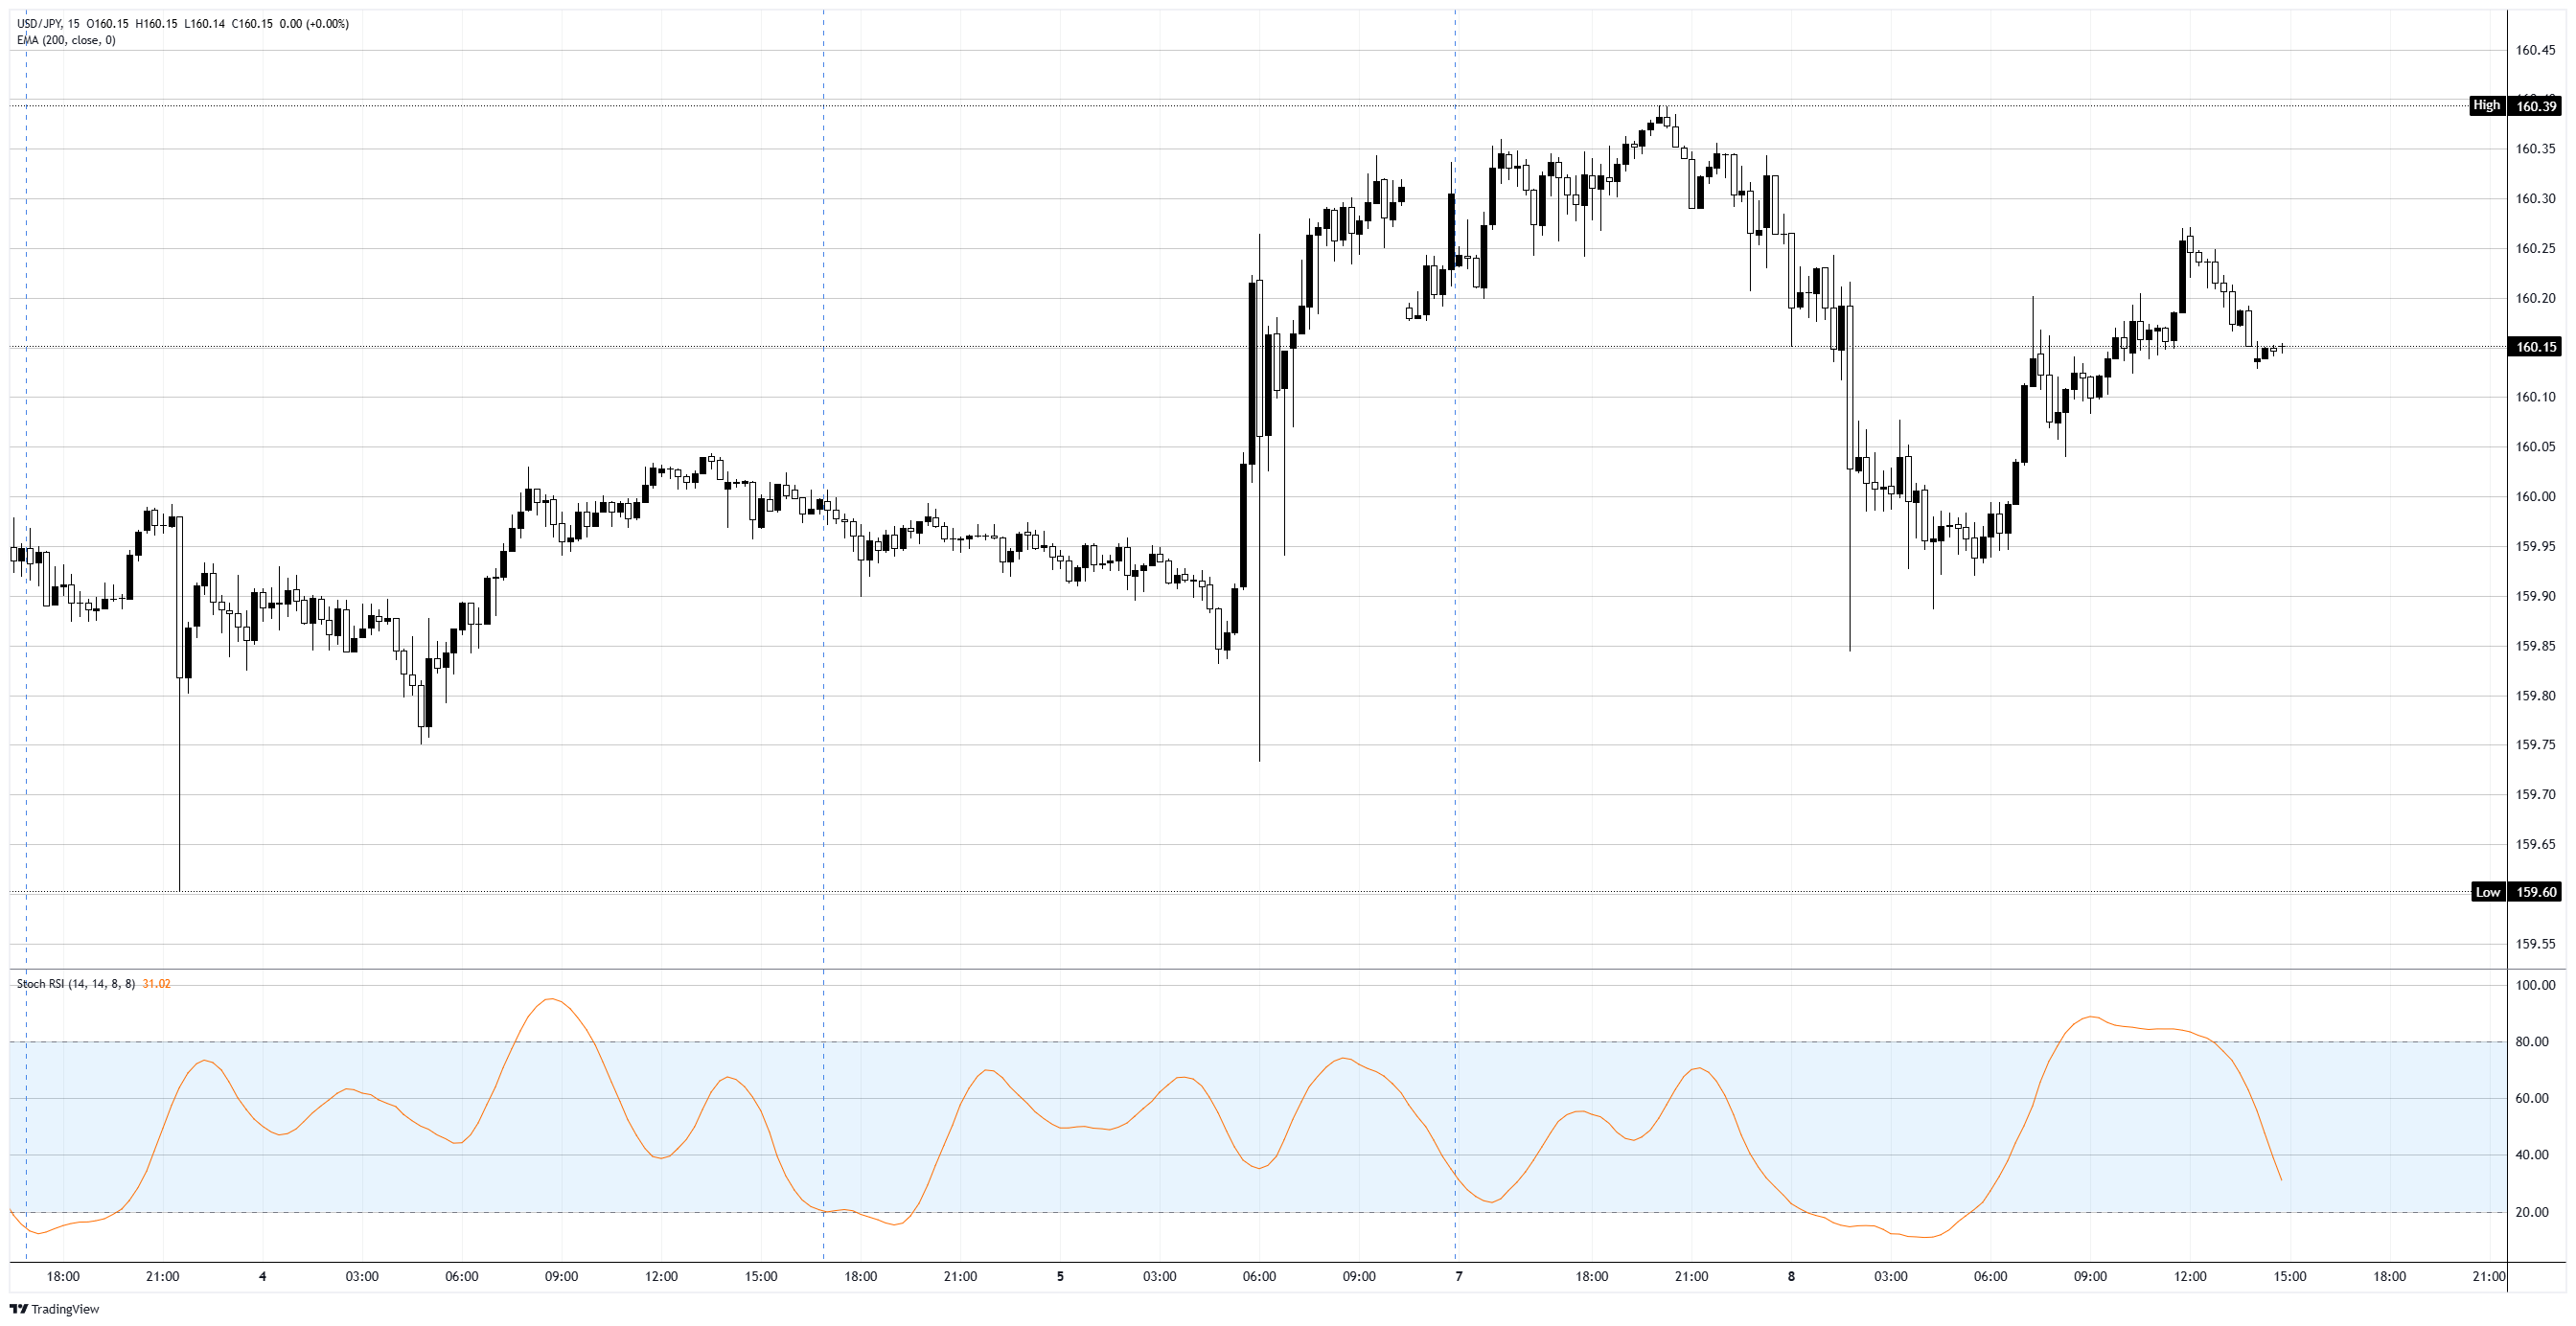
Monday's price action showed the tension. The pair slipped under 160.00 during the session as the renewed Iran-Israel escalation triggered a brief risk-off bid for the Yen, before buyers reclaimed the figure and pushed it back toward 160.00 by the European afternoon. Even a genuine geopolitical scare could only buy the Yen a few hours.
Intervention math is back on the desk
This is where it gets interesting. The 160 zone is not arbitrary: it is roughly where Japan's Ministry of Finance (MoF) stepped in during April with a sharp reversal of several hundred pips that bore all the hallmarks of official action. With Prime Minister Takaichi and finance officials already issuing verbal warnings, the market is once again testing how much disorderly weakness Tokyo will tolerate. The catch is that intervention without a fundamental shift tends to be a volatility event, not a trend change, and traders increasingly treat it that way. A BoJ hike on June 18 would help the cause far more than spot intervention, which is why this week's data matters mostly for what it does to the Dollar side of the equation.
The daily Stochastic Relative Strength Index (Stoch RSI) is buried in overbought territory near 93, a warning that the grind higher is stretched even if the trend is intact. The 200-period Exponential Moving Average (EMA) on the daily chart sits far below near 156.00, underscoring just how extended the move has become.
Trade setup
Resistance is the story above. The 160.50 area marks the April intervention zone, with the 161.00 handle the next magnet if it clears. Support sits at the 160.00 figure, then 159.50 and 159.00 beneath.
Bias is cautiously higher while the rate and energy backdrop holds, but this is not a level to chase. The asymmetry is awkward: upside is capped by intervention risk and overbought momentum, while a downside flush could come fast and hard if Tokyo acts or US Consumer Price Index (CPI) on Wednesday somehow disappoints. Selling strength near 160.50 with tight risk makes more sense than buying the figure, with the BoJ decision next week the real event.
USD/JPY 15-minute chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















