EUR/USD Price Forecast: On verge of downward-trendline breakout
- EUR/USD ticks lower to near 1.1550 as the US Dollar recovers.
- Traders have trimmed hawkish Fed bets due to weak US NFP data.
- Eurozone’s Sentix Investor Confidence turns positive to 0.9 in August.
The Euro (EUR) trades slightly lower at around 1.1550 against the US Dollar (USD) during the European trading session on Monday. The EUR/USD pair edges down as the US Dollar holds onto its early recovery, which, according to market experts, lacks conviction, as traders have dialed down hawkish Federal Reserve (Fed) bets after the United States (US) Nonfarm Payrolls (NFP) data release.
Fed hike case softens as US jobs data underwhelm
Analysts at Rabobank argue that Friday’s US employment report has further eroded the case for additional Fed tightening, noting that “the case for a Fed hike is weakening, but it is certainly not yet done for.” They highlight that the “headline payrolls number disappointed, with a -23,000 jobs print and a 37,000 downward revision to the June estimate,” underscoring a softer tone in the labour market. Rabobank adds that their US strategist had already observed that “employment growth has been slowing for several months,” and that the latest release “confirmed that downside risks to the labour market have not disappeared entirely since the three insurance cuts last year.” In their view, this evolving backdrop “could strengthen the argument of the Fed’s doves,” even if the policy debate remains open.
This week, the major trigger for the US Dollar will be the US Consumer Price Index (CPI) data for July, which will be released on Wednesday.
On the Eurozone front, the Sentix Investor Confidence data, a key indicator of Investor morale, has come in surprisingly positive at 0.9 in August from -3.1 in July.
EUR/USD Technical Analysis
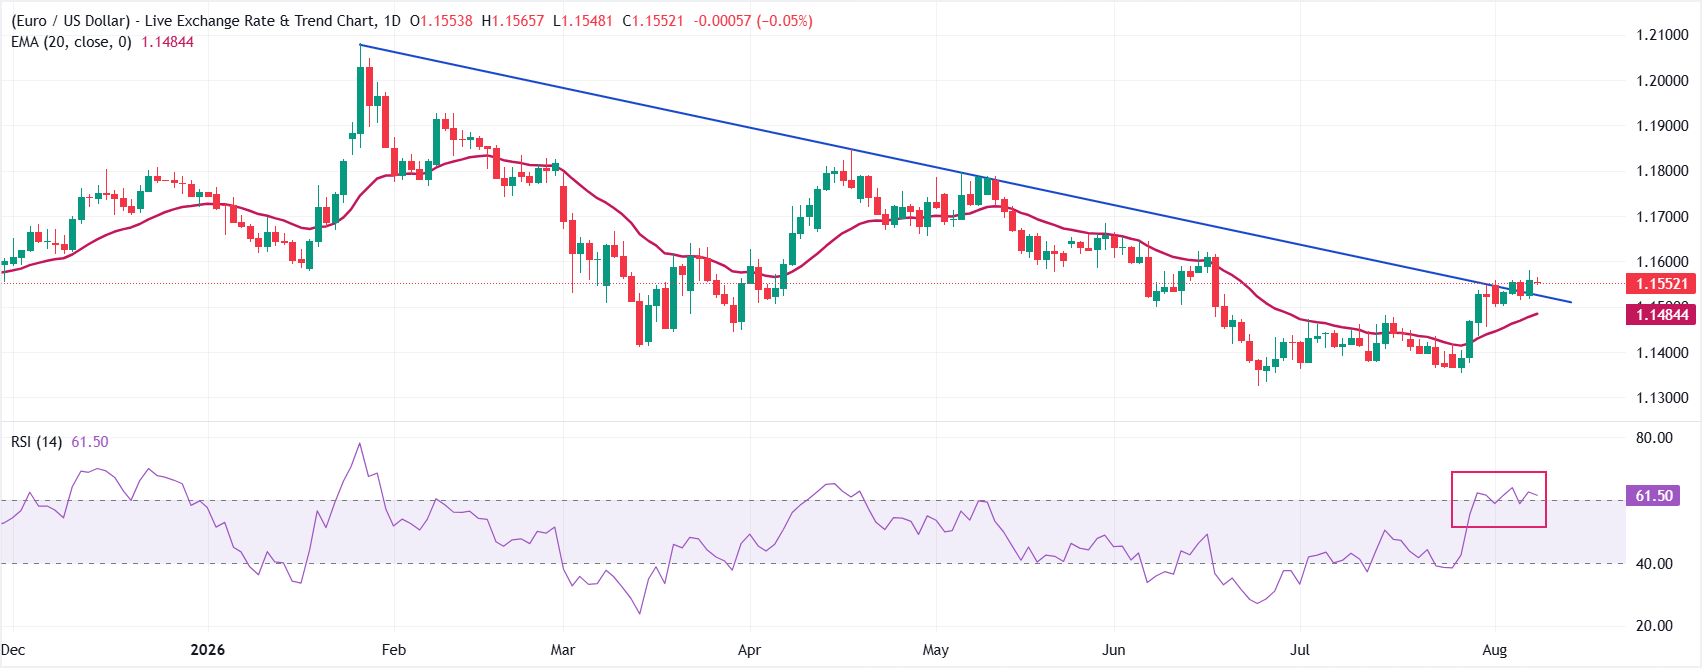
EUR/USD trades around 1.1550, holding significantly above the 20-day exponential moving average (EMA) at 1.1484 and slightly above the downward-sloping trend line around 1.1520, keeping the near-term bias bullish.
The Relative Strength Index (14) around 61 suggests constructive upside momentum, though still shy of overbought conditions, hinting that bulls retain control as long as spot remains anchored above the former trend-line cap.
On the downside, immediate support is seen at the trend-line break area near 1.1520, with the 20-day EMA at 1.1484 providing a deeper cushion if a pullback extends. Looking up, the pair could extend the advance towards the June 5 high at 1.1644 if it manages to hold above the August 7 high at 1.1581.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.
















