Dow Jones Industrial Average retests its floor as consumer confidence sinks
- DJIA retests 51,100 for a third time in September as consumer confidence sinks.
- Conference Board confidence index at 81.9, the lowest since 2014.
- US consumer spending seen up 0.8% in August, from 0.2% in July.
The worst US consumer confidence reading since 2014 should have been enough to break the Dow Jones Industrial Average's September floor near 51,100, and the floor held for a third time. The Conference Board's index fell to 81.9 from 88.6 against a forecast near 89, and households told the survey they expect business conditions and the job market to weaken over the next six months.
Their view of current business conditions turned negative for the first time since September 2024. Job openings came in light as well, at 7.08M in August against a 7.23M forecast. The survey closed on September 23, before the 10-year Treasury yield's latest climb to its highest since 2007.
Saving September would take a 3.6% day
The Dow is down about 3.5% in September with one session left, and a monthly loss would end a five-month winning streak. The S&P 500 is down 0.2% over the same stretch.
Treasury yields set new highs again on Tuesday, with the 30-year at its highest since 2002 and the 10-year near 5.26%. Those rates set the price of mortgages, car loans and company debt, which is how they reach the Dow's housing, consumer and industrial members. The Fed raised rates on September 16 for the first time since 2023, and futures still lean toward another quarter-point increase on October 28.
Wednesday also ends the third quarter, and the Dow is down almost 2% for it. Softer household and hiring numbers would usually pull yields lower, so Tuesday's climb, on a day with two soft reports, points to inflation as the bigger worry for bond buyers. The Dow has moved with yields all month.
Confidence is a survey and spending is a receipt
Wednesday brings August personal income and spending at 12:30 GMT, together with the core Personal Consumption Expenditures (PCE) price index, forecast up 0.3% MoM. Private payrolls from Automatic Data Processing (ADP) come out first at 12:15 GMT, forecast at 70K, and the Chicago purchasing managers' index follows at 13:45 GMT, forecast at 51.2 from 47.1. By Wednesday's forecast, those same gloomy households raised their spending 0.8% in August.
Weekly jobless claims on Thursday at 12:30 GMT are forecast at 200K. The Institute for Supply Management (ISM) factory survey is due at 14:00 GMT, with the headline index expected at 55 and prices paid at 72.3, and Nike (NKE), a Dow member, reports after the close. September payrolls land on Friday, forecast at 90K after 162K in August, with the jobless rate steady at 4.1%. Firm spending and payroll numbers leave the Fed free to hike again in October.
That leaves the Dow needing weaker jobs data, since a soft payroll figure is the likeliest thing on the calendar to pull yields off their highs.
Technical levels
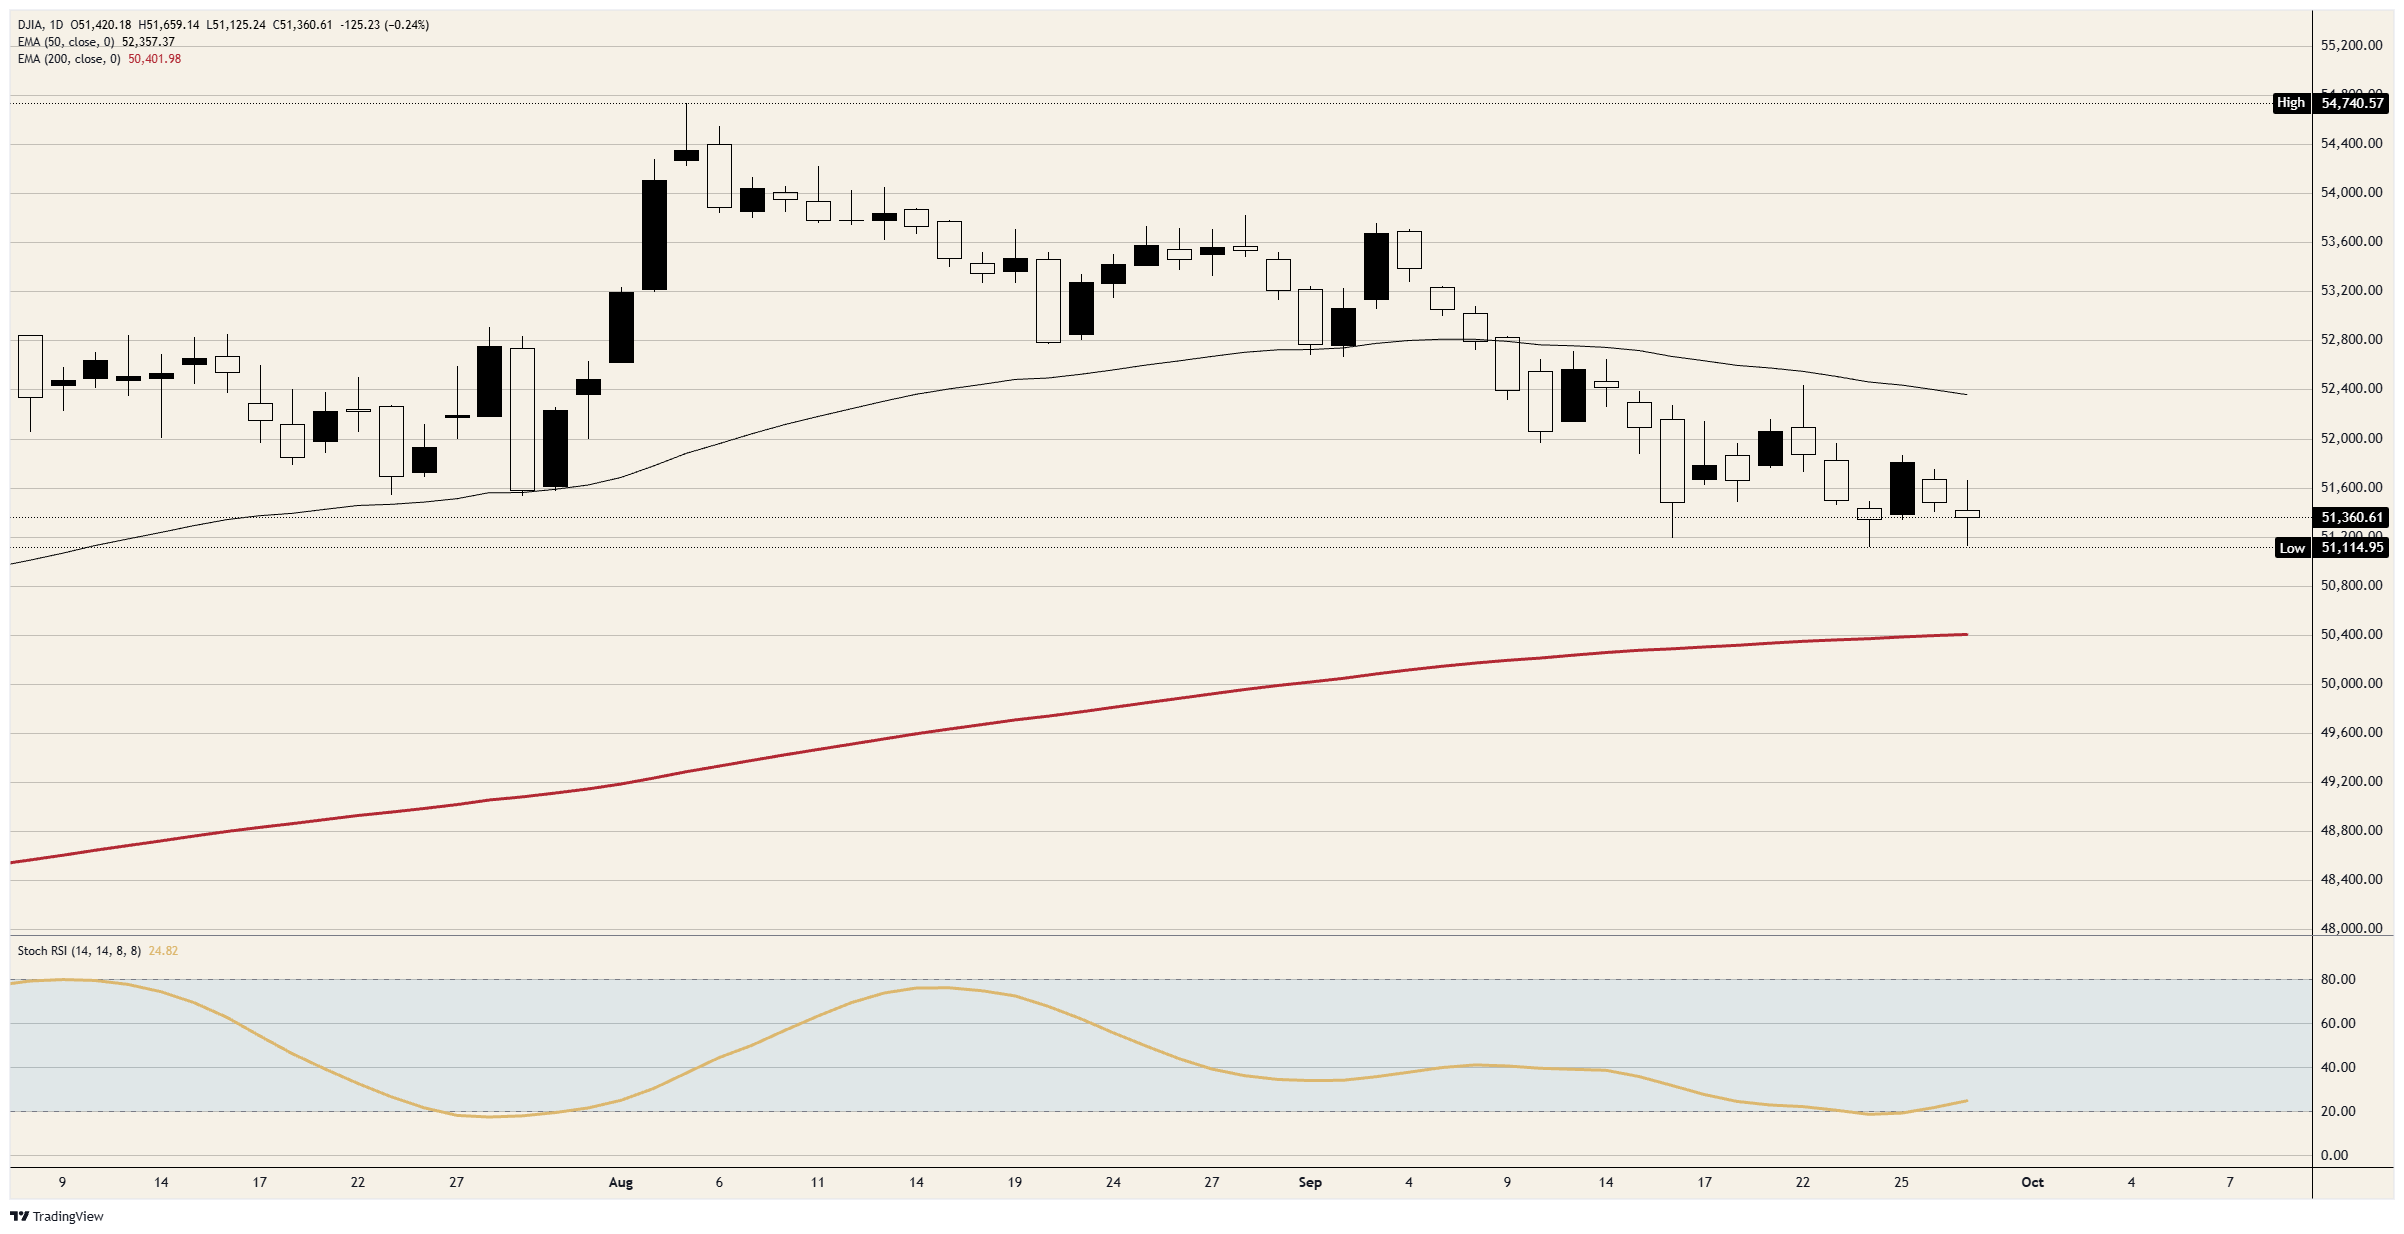
Resistance: The 51,800 area capped Friday's rebound and Monday's high. Above it, 52,000 is the level the Dow lost on September 22, the first of three straight declines.
Support: The 51,100 area has held three times in September, on September 16, September 24 and Tuesday. Below it, the 200-day Exponential Moving Average (EMA) near 50,400 is the next floor.
Bias: Short below 51,800, with a daily close under 51,100 as the first objective and the 200-day EMA near 50,400 as the second. The daily Stochastic Relative Strength Index (Stoch RSI) near 25 has turned up from the low 20s, so a bounce into 51,800 could come first. A daily close above 52,000 cancels the call.
Dow Jones daily chart
Dow Jones FAQs
The Dow Jones Industrial Average, one of the oldest stock market indices in the world, is compiled of the 30 most traded stocks in the US. The index is price-weighted rather than weighted by capitalization. It is calculated by summing the prices of the constituent stocks and dividing them by a factor, currently 0.152. The index was founded by Charles Dow, who also founded the Wall Street Journal. In later years it has been criticized for not being broadly representative enough because it only tracks 30 conglomerates, unlike broader indices such as the S&P 500.
Many different factors drive the Dow Jones Industrial Average (DJIA). The aggregate performance of the component companies revealed in quarterly company earnings reports is the main one. US and global macroeconomic data also contributes as it impacts on investor sentiment. The level of interest rates, set by the Federal Reserve (Fed), also influences the DJIA as it affects the cost of credit, on which many corporations are heavily reliant. Therefore, inflation can be a major driver as well as other metrics which impact the Fed decisions.
Dow Theory is a method for identifying the primary trend of the stock market developed by Charles Dow. A key step is to compare the direction of the Dow Jones Industrial Average (DJIA) and the Dow Jones Transportation Average (DJTA) and only follow trends where both are moving in the same direction. Volume is a confirmatory criteria. The theory uses elements of peak and trough analysis. Dow’s theory posits three trend phases: accumulation, when smart money starts buying or selling; public participation, when the wider public joins in; and distribution, when the smart money exits.
There are a number of ways to trade the DJIA. One is to use ETFs which allow investors to trade the DJIA as a single security, rather than having to buy shares in all 30 constituent companies. A leading example is the SPDR Dow Jones Industrial Average ETF (DIA). DJIA futures contracts enable traders to speculate on the future value of the index and Options provide the right, but not the obligation, to buy or sell the index at a predetermined price in the future. Mutual funds enable investors to buy a share of a diversified portfolio of DJIA stocks thus providing exposure to the overall index.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















