Crude Oil fades another war spike as the ceasefire dies its daily death
- WTI Crude Oil trades near $71.00, down 1%, after a morning spike to $72.83 was sold back to the session low inside two hours.
- The International Energy Agency forecasts the first annual decline in worldwide demand since 2020, recasting the war as demand destruction rather than a supply squeeze.
- President Trump repeats that the ceasefire is over and Tehran denies rumours of fresh talks, yet the risk premium shrinks with every rerun.

West Texas Intermediate (WTI) Crude Oil trades at $70.98 on Friday, down 1%, after a European-morning climb to $72.83 met a wall of New York selling that drove the barrel to a $70.70 session low inside two hours. The escalation premium built off the $68.00 base earlier in the week is still intact on paper, and Friday's tape is eating it in real time, on a day when the news flow should have paid sellers to stay home.
A war that no longer clears the headline bar
The raw material of a supply scare is all present and accounted for. US forces have struck Iranian targets more than 170 times in two days, Tehran has fired ballistic missiles at a base in Jordan and attacked commercial vessels around the Strait of Hormuz, and tanker traffic through the chokepoint has slowed to a trickle while hundreds of stranded ships await clearance.
President Trump repeated on Friday morning that the ceasefire is over, recycling Wednesday's declaration in a social media post, while Iranian sources rejected rumours that a fresh round of talks is scheduled for next week. Qatar and Pakistan are working to drag both sides back to the table, Oman and Turkey are fielding calls from Tehran, and Washington maintains that technical talks continue regardless. Iran also buried its former supreme leader on Friday, a succession moment that in any prior decade would have added dollars to the barrel on its own.
The market sold all of it. Thursday's tape cooled on a claim that Iran had called to negotiate, Friday's push above $72.50 lasted roughly the length of a lunch order, and each escalation now buys fewer dollars per barrel and holds them for less time than the one before it. Positioning explains part of the decay; a market that spent June erasing its entire wartime premium has little appetite to rebuild it on rhetoric alone.
The International Energy Agency turns the bull case inside out
Friday's monthly report from the International Energy Agency (IEA) put a number on what the tape already suspected: worldwide demand for Crude Oil and refined products is set to fall by 1 million barrels per day in 2026, the first annual decline since 2020, with the contraction skewed heavily toward the products and regions the Hormuz closure hit hardest. Supply is healing faster than consumption, having rebounded by 4.1 million barrels per day in June to 98.8 million as flows through the Strait resumed, though output remains 9.4 million barrels per day below pre-war levels.
The agency's forward math is worse for bulls than its history. The balance swings back to surplus toward the end of the year and into a significant 2027 overhang if transit volumes keep recovering, and the entire projection is explicitly contingent on a lasting peace that nobody is currently signing. De-escalation therefore fast-forwards the glut, renewed escalation deepens the demand destruction, and only a full, sustained loss of the Strait genuinely re-prices supply. Traders have now watched two shutdowns of the waterway fail to stick.
Beneath the headline, the report describes a crude market that is loose and a products market that is not, with refinery margins and gasoline cracks running at multi-year highs while damaged Gulf refining capacity limps back online. That squeeze rewards refiners rather than the barrel itself; for WTI, tight products are a consolation prize, not a bid.
Next week trades on Washington data, not Gulf rhetoric
June's US Consumer Price Index (CPI) lands Tuesday at 12:30 GMT, and it matters for the barrel twice over: May's 4.2% YoY headline was driven substantially by war-inflated energy costs, and a hot repeat would keep the Fed hawkish and the Dollar firm, a standing headwind for Crude Oil. The Fed chair testifies at 14:00 GMT on Tuesday and Wednesday, with US retail sales due Thursday at 12:30 GMT.
On the supply side, the weekly Energy Information Administration (EIA) inventory report lands Wednesday at 14:30 GMT and the Baker Hughes rig count arrives later Friday at 17:00 GMT. The genuine red-band release remains unscheduled: Hormuz tanker-tracking data has replaced the calendar as the market's real tape, and it prints continuously.
Crude Oil technical levels
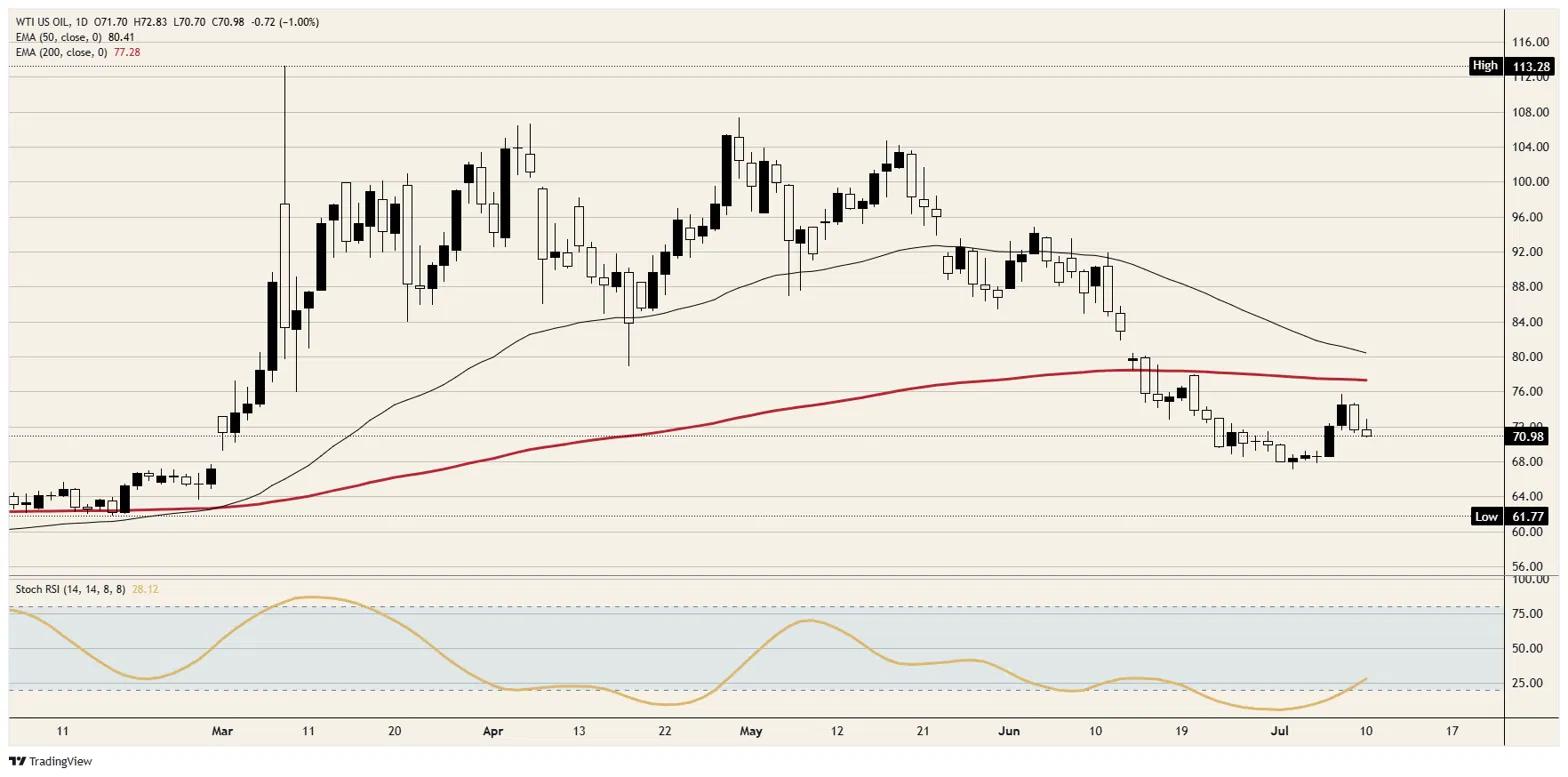
Resistance: Friday's rejected spike at $72.83 caps the tape under the $73.00 handle. Above it the air stays thin until $76.00, where June's breakdown began, with the falling 200-day Exponential Moving Average just behind at $77.28.
Support: The session low at $70.70 defends the $70.00 handle. Below that, the late-June base at $68.00 is the level the entire rebound is built on, and a daily close beneath it would put the February trough near $62.00 back on the map.
Bias: Lower. Sellers are meeting strength on schedule while $73.00 caps, and although the daily Stochastic Relative Strength Index curling up from oversold near 28 argues against chasing weakness, the path of least resistance runs back toward $68.00; only a daily close above $73.00 forces shorts to reconsider.
WTI daily chart
WTI Oil FAQs
WTI Oil is a type of Crude Oil sold on international markets. The WTI stands for West Texas Intermediate, one of three major types including Brent and Dubai Crude. WTI is also referred to as “light” and “sweet” because of its relatively low gravity and sulfur content respectively. It is considered a high quality Oil that is easily refined. It is sourced in the United States and distributed via the Cushing hub, which is considered “The Pipeline Crossroads of the World”. It is a benchmark for the Oil market and WTI price is frequently quoted in the media.
Like all assets, supply and demand are the key drivers of WTI Oil price. As such, global growth can be a driver of increased demand and vice versa for weak global growth. Political instability, wars, and sanctions can disrupt supply and impact prices. The decisions of OPEC, a group of major Oil-producing countries, is another key driver of price. The value of the US Dollar influences the price of WTI Crude Oil, since Oil is predominantly traded in US Dollars, thus a weaker US Dollar can make Oil more affordable and vice versa.
The weekly Oil inventory reports published by the American Petroleum Institute (API) and the Energy Information Agency (EIA) impact the price of WTI Oil. Changes in inventories reflect fluctuating supply and demand. If the data shows a drop in inventories it can indicate increased demand, pushing up Oil price. Higher inventories can reflect increased supply, pushing down prices. API’s report is published every Tuesday and EIA’s the day after. Their results are usually similar, falling within 1% of each other 75% of the time. The EIA data is considered more reliable, since it is a government agency.
OPEC (Organization of the Petroleum Exporting Countries) is a group of 12 Oil-producing nations who collectively decide production quotas for member countries at twice-yearly meetings. Their decisions often impact WTI Oil prices. When OPEC decides to lower quotas, it can tighten supply, pushing up Oil prices. When OPEC increases production, it has the opposite effect. OPEC+ refers to an expanded group that includes ten extra non-OPEC members, the most notable of which is Russia.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















