August UK inflation report expected to show rising inflation
- UK inflation is expected to accelerate to 3.1% YoY in August from 2.9% in July, driven in part by higher energy prices.
- Core inflation is also expected to pick up, while further energy and food price pressure looms.
- The data comes one day before the BoE’s decision, with policymakers expected to keep rates unchanged.
The United Kingdom (UK) Office for National Statistics (ONS) will publish the highly anticipated Consumer Price Index (CPI) data for August on Wednesday at 06:00 GMT.
The inflation report could trigger volatility in the British Pound (GBP), as it comes just one day before the Bank of England (BoE) monetary policy decision. The central bank is expected to keep its policy rate unchanged at 3.75% on Thursday, but another acceleration in price pressure could strengthen expectations of an interest rate hike in the coming months.
What to expect from the next UK inflation report?
The UK Consumer Price Index is expected to rise 3.1% YoY in August, up from 2.9% in July, moving further away from the BoE’s 2% target. On a monthly basis, CPI is expected to increase by 0.5% in August, following a 0.3% rise in July.
Core inflation, which excludes the volatile energy, food, alcohol and tobacco components, is also expected to accelerate to 2.7% YoY from 2.6% previously. A simultaneous increase in headline and core inflation could fuel concerns at the BoE about persistent price pressure.
The expected acceleration in headline inflation comes as the consequences of the conflict in the Middle East continue to feed through to UK energy costs. UK Finance notes that transport prices rose 9.1% YoY in July and that pump prices increased again in August, with a litre of unleaded petrol reaching its highest level since November 2022.
Inflationary pressure could also persist beyond the August report. UK energy regulator Ofgem has confirmed another 4% increase in the energy price cap from October, following the increase implemented in July.
Risks also appear to be spreading to food prices. The latest Worldpanel by Numerator data showed that grocery price inflation accelerated to 2.3% YoY in the four weeks to September 6, from 2.1% in the previous report. Meanwhile, the Food and Drink Federation (FDF) expects food and non-alcoholic drink inflation to reach 3.9% in December before exceeding 6% in 2027, due in part to higher energy costs, logistical disruptions and weather conditions.
This pressure could further complicate the disinflation process. The BoE projected in July that headline inflation would peak at around 3.2% in the fourth quarter of 2026, while judging that risks to its inflation outlook were tilted to the upside. Bloomberg Economics now estimates that higher energy costs could push UK inflation above 4% in 2027.
How will the UK Consumer Price Index report affect GBP/USD?
Wednesday’s release is particularly important for GBP/USD as it comes on the eve of the BoE’s monetary policy decision. Economists widely expect the central bank to keep its policy rate unchanged at 3.75%. All 65 economists surveyed in a Reuters poll conducted between September 4 and 8 expect the BoE to remain on hold on Thursday, while 57 of them anticipate rates staying unchanged through the end of the year.
Markets, however, are taking a more hawkish view. According to Morningstar, interest rate markets see a potential first BoE rate hike as early as November and are pricing in three increases by mid-2027.
Divisions within the Monetary Policy Committee (MPC) add to the importance of the inflation report. At the July meeting, three of the nine committee members voted for a 25-basis-point (bps) rate increase, up from two members previously.
The key debate for the BoE, however, remains whether the energy shock is generating more persistent second-round inflation effects. According to Reuters, citing HSBC UK economist Elizabeth Martins, the BoE has indicated that it would consider a policy move if second-round effects emerged, but current conditions are unlikely to be enough for policymakers supporting unchanged rates to switch their votes.
A report showing headline and core inflation above expectations could nevertheless change the picture. Such a surprise would reinforce concerns that energy-related pressures are beginning to spread more broadly through the economy and could increase the likelihood of a rate hike in the coming months. In this scenario, the British Pound could attract fresh demand, pushing GBP/USD higher.
Conversely, softer-than-expected inflation, particularly in the core measure, would strengthen the argument that the energy shock remains largely temporary and is not yet generating persistent domestic price pressure. This could reduce expectations of BoE monetary tightening and weigh on the British Pound.
A release broadly in line with expectations could quickly shift attention toward the composition of the report, particularly services inflation, as well as the BoE’s vote split and policy message on Thursday. With a September rate hike still considered unlikely, the key question for markets could be whether the acceleration in August inflation is strong enough to bring the next rate increase closer.
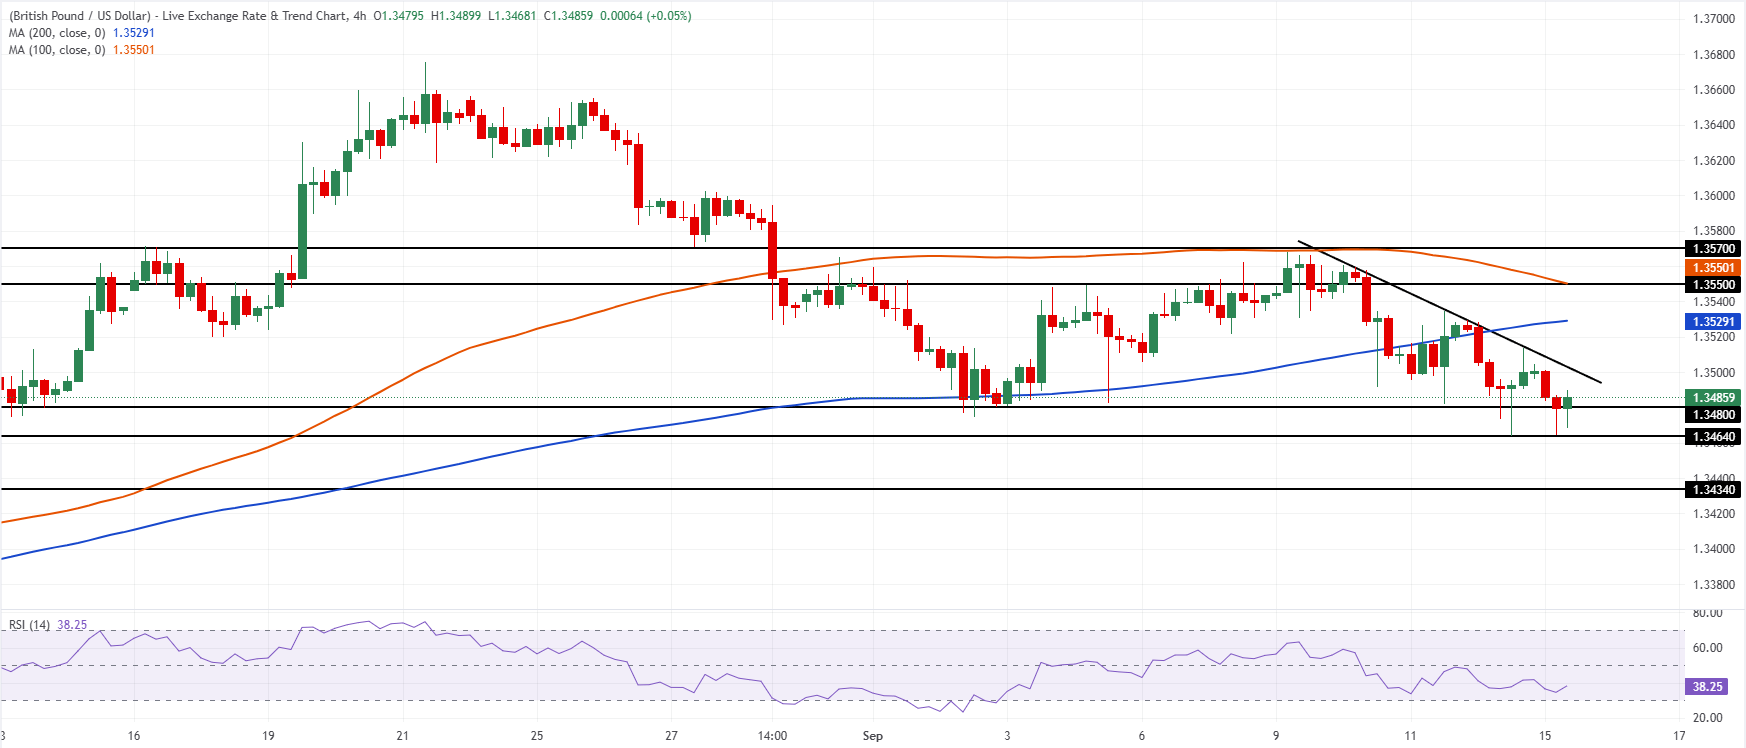
On the 4-hour chart, GBP/USD keeps a bearish near-term bias as it holds beneath the 200-period Simple Moving Average (SMA) at 1.3529 and a confluence of resistance around 1.3550 marked by the 100-period SMA and a horizontal cap, while a downward-sloping trendline continues to weigh on rallies. The Relative Strength Index (14) hovers in the high-30s, hinting that downside momentum remains in place even as price stabilizes just above nearby supports.
On the topside, initial resistance appears at the 200-period SMA around 1.3529, with a denser barrier near 1.3550 where the 100-period SMA aligns with horizontal resistance, ahead of the 1.3570 level and the overarching descending trendline. On the downside, immediate support is seen at 1.3480, with further cushions at 1.3464 and 1.3434; a clear break below this support band would open the door to an extension of the current bearish phase.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Indicator
Consumer Price Index (YoY)
The United Kingdom (UK) Consumer Price Index (CPI), released by the Office for National Statistics on a monthly basis, is a measure of consumer price inflation – the rate at which the prices of goods and services bought by households rise or fall – produced to international standards. It is the inflation measure used in the government’s target. The YoY reading compares prices in the reference month to a year earlier. Generally, a high reading is seen as bullish for the Pound Sterling (GBP), while a low reading is seen as bearish.
Read more.Next release: Wed Sep 16, 2026 06:00
Frequency: Monthly
Consensus: 3.1%
Previous: 2.9%
Source: Office for National Statistics
The Bank of England is tasked with keeping inflation, as measured by the headline Consumer Price Index (CPI) at around 2%, giving the monthly release its importance. An increase in inflation implies a quicker and sooner increase of interest rates or the reduction of bond-buying by the BOE, which means squeezing the supply of pounds. Conversely, a drop in the pace of price rises indicates looser monetary policy. A higher-than-expected result tends to be GBP bullish.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.















