AI selloff widens: Why Asia can diversify the next phase of the AI trade
Key points
The current selloff isn’t “AI is over” — it’s a rotation from AI pioneers priced for perfection toward AI enablers with nearer-term cashflows and pricing power.
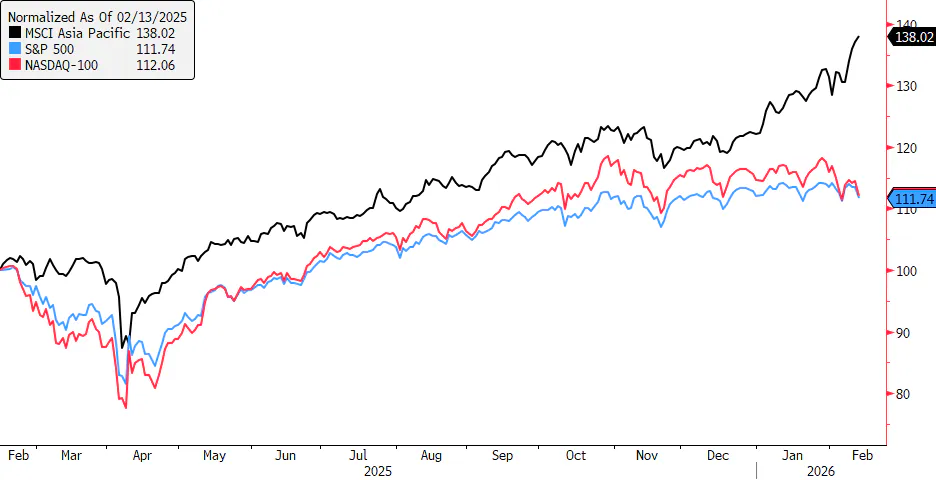
Asia’s resilience reflects its heavier exposure to upstream AI infrastructure (memory, foundries, assembly/packaging) versus the US market’s heavier exposure to downstream software and services now being scrutinised for disruption risk.
Asia can act as a diversifier when correlations fall — but investors should be alert to concentration risk within Asia indices (a few mega names dominate) and the fact that Asia is not immune if the selloff becomes broad global risk-off.
Where the AI dispersion trade is hitting
The AI selloff is no longer confined to a single corner of tech. The market is increasingly pricing dispersion and separating likely AI beneficiaries from businesses where AI could compress margins or automate away fee pools.
So far, the pressure has been most visible in:
- Software: renewed scrutiny on pricing power and whether new AI tools commoditise workflows.
- Wealth management / brokers: concerns that AI-driven automation lowers switching costs and compresses advisory and platform fees.
- Insurance: fear that underwriting, claims and distribution become more automated and competitive.
- Logistics and transport: questions around how quickly AI and automation reprice efficiency, pricing and labour costs across the value chain.
- Real estate services/other intermediaries: areas where AI can reduce the need for manual processing, documentation and brokerage-like functions.
That widening “who gets disrupted?” narrative is what’s driving rotation, and it helps explain why parts of Asia are holding up better, given their heavier exposure to upstream AI infrastructure rather than downstream service models.
A profit-capture rotation, not an “anti-AI” move
Markets rarely abandon a transformative theme overnight. What they do abandon is the most crowded expression of that theme when the narrative shifts from excitement to scrutiny.
The latest leg of the AI selloff has broadened beyond a handful of high-flying tech names into pockets of the market that look most exposed to AI-driven business model disruption — particularly software and select service industries.
At the same time, that fear is showing up as a surprising tailwind for parts of Asia.
A cleaner way to frame the current rotation is:
US – downstream AI (apps, software, services)
The US market has the deepest concentration in the downstream layers—where AI’s promise is enormous, but so is the monetisation and disruption debate:
- Who loses pricing power as AI commoditises workflows?
- Which fee pools shrink as automation expands?
- Does AI capex pay back fast enough—and for whom?
In other words, the market is asking whether AI expands the pie or forces the winners to give the pie away to customers.
Asia – Upstream AI (compute and components)
Asia’s exposure is more upstream—the infrastructure that has to be built regardless of which applications dominate:
- Components and advanced manufacturing capacity that sit beneath the AI stack.
- The physical supply chain that enables scaling models in the real world.
When the market worries about AI disrupting business models, downstream feels it first. When the focus shifts to what must be built either way, upstream often behaves differently.
Performance divergence: MSCI Asia Pacific Index vs S&P 500 vs Nasdaq 100
Source: Bloomberg
Asia isn’t one trade: Korea/Taiwan vs Japan
This is where the “Asia as diversifier” story becomes investable rather than theoretical.
Korea and Taiwan: The purest “AI infrastructure beta”
Korea and Taiwan are the cleanest expression of upstream AI buildout. They tend to respond to:
- The pace of global AI hardware demand.
- Supply tightness and pricing power in key components.
- Capex cycles and utilisation rates.
These markets can be resilient when infrastructure demand is strong, but they’re also cyclical and can swing when global tech sentiment turns.
Japan: AI spend and adoption, with less immediate disruption risk
Japan adds something different, and arguably more interesting in this phase of the narrative. Japan can capture AI upside through adoption and implementation rather than pure “app-layer disruption”:
- Industrial AI and automation: productivity upgrades in manufacturing, robotics, sensors, precision machinery, and process optimisation.
- Enterprise adoption: AI as a tool to offset labour constraints, improve efficiency, and modernise operations—often in areas where change is incremental and execution-driven.
- More entrenched sector mix: parts of Japan’s equity market are anchored in industries where disruption is slower and where relationships, regulation, and operational complexity create inertia.
That doesn’t mean Japan has no disruption risk. It means the near-term equity story is more often AI as a productivity catalyst than AI as an existential pricing threat.
The Asia opportunity is real — but don’t ignore the caveats
A credible diversification pitch includes the risks.
Risk 1: Concentration inside Asia indices
Asia’s equity indices have become increasingly top-heavy.
- Taiwan’s benchmark has a large weight in a single foundry leader.
- Korea’s index is heavily influenced by a small number of memory and hardware champions.
What this means: “Buying Asia” can unintentionally become “buying a handful of chip names.” Diversification improves when the portfolio has multiple drivers, not simply a different postcode.
Asia isn’t immune — it’s just differently exposed
Even if Asia is less exposed to certain AI-disrupted service models, it can still be hit through:
- Global risk-off episodes (funding conditions, USD strength, volatility spikes).
- Synchronised tech drawdowns (when investors cut risk broadly).
- Down-cycles in semiconductors (inventory, pricing, demand shocks).
The excerpt itself notes that some Asia-listed software and IT services names fell alongside US peers during the selloff.
Risk 3: The AI buildout is cyclical too
Upstream beneficiaries can enjoy pricing power — until they don’t. Memory pricing, foundry utilisation and capex cycles can turn quickly.
Bottom line: Asia can diversify the type of AI exposure, not eliminate AI exposure.
Closing: Asia is not a “safe haven” — It’s a different set of drivers
The most useful way to think about Asia in this AI selloff is not as a bet that “Asia wins.”
It’s a recognition that Asia’s role in the AI ecosystem, and the region’s broader equity composition, can provide diversification by driver at a moment when the US market is repricing concentrated leadership.
Read the original analysis: AI selloff widens: Why Asia can diversify the next phase of the AI trade
Author

Saxo Research Team
Saxo Bank
Saxo is an award-winning investment firm trusted by 1,200,000+ clients worldwide. Saxo provides the leading online trading platform connecting investors and traders to global financial markets.

















