US Dollar Index extends its winning streak as Fed speakers line up behind hikes
- DXY extends its run to near 101.40, its highest since late July, as Fed speakers back hikes.
- Initial jobless claims at 197K against a 201K forecast.
- Durable goods orders on Friday, forecast at -0.4% after 1.1%.
The Dollar Index has won back about 90% of what it lost between the late-July top and the August low. It reached 101.40 on Thursday, its highest since late July, and is heading for a fourth straight gain.
Three Fed officials spoke on Thursday and all three said more tightening may be needed. The futures market had been paying for that since the Fed raised rates to 3.75-4.00% on September 16. It's possible the Fed is further from its next move than the Dollar implies, though none of the three officials who spoke said so.
A 4K beat on jobless claims, and three speakers who didn't need it
New York Fed President Williams said in London it is reasonable to expect one more increase this year. Cleveland Fed President Hammack said the risks to inflation lean higher and that the longer it stays above target, the harder and more costly the return to 2%. Philadelphia Fed President Paulson, like President Hammack a voter this year, said further modest increases may be needed.
The US data gave none of them a reason to back off. Initial jobless claims came in at 197K against a 201K forecast and 198K the week before, and new home sales rose 6.4% in August after a 4.3% fall. Futures put better-than-even odds on an October hike, and another hike widens the gap between what Dollar deposits earn and what the Euro and the Yen earn.
Friday brings the orders data. Durable goods orders are forecast at -0.4% after 1.1%, and orders excluding transportation at 0.6% after 0.4%, with the University of Michigan's household inflation expectations at 14:00 GMT forecast at 4.6% for the year ahead. President Williams and President Hammack are both scheduled to speak again on Friday, so the market gets a second hearing from two officials it has already priced.
A 31-year high in Japanese rates, and the Yen still falls
The other half of the move is outside the US. The Euro traded at a two-month low against the Dollar in Asia on Thursday, and the Pound near a three-month low. USD/JPY traded near 158.00 as Tokyo came back from three days of holidays. That's despite the Bank of Japan (BoJ) raising its rate to 1.25% on September 18, a hike traders read as too small to start a run of them.
Japan's finance ministry bought ¥15.4 trillion of Yen between July 30 and August 26. The risk of a repeat keeps traders more cautious above 158.00 than the BoJ rate does. The Euro is 57.6% of the Dollar Index and the Yen 13.6%, so a two-month low in the Euro moves the index about four times as much as the same step in the Yen.
Levels for the Dollar Index
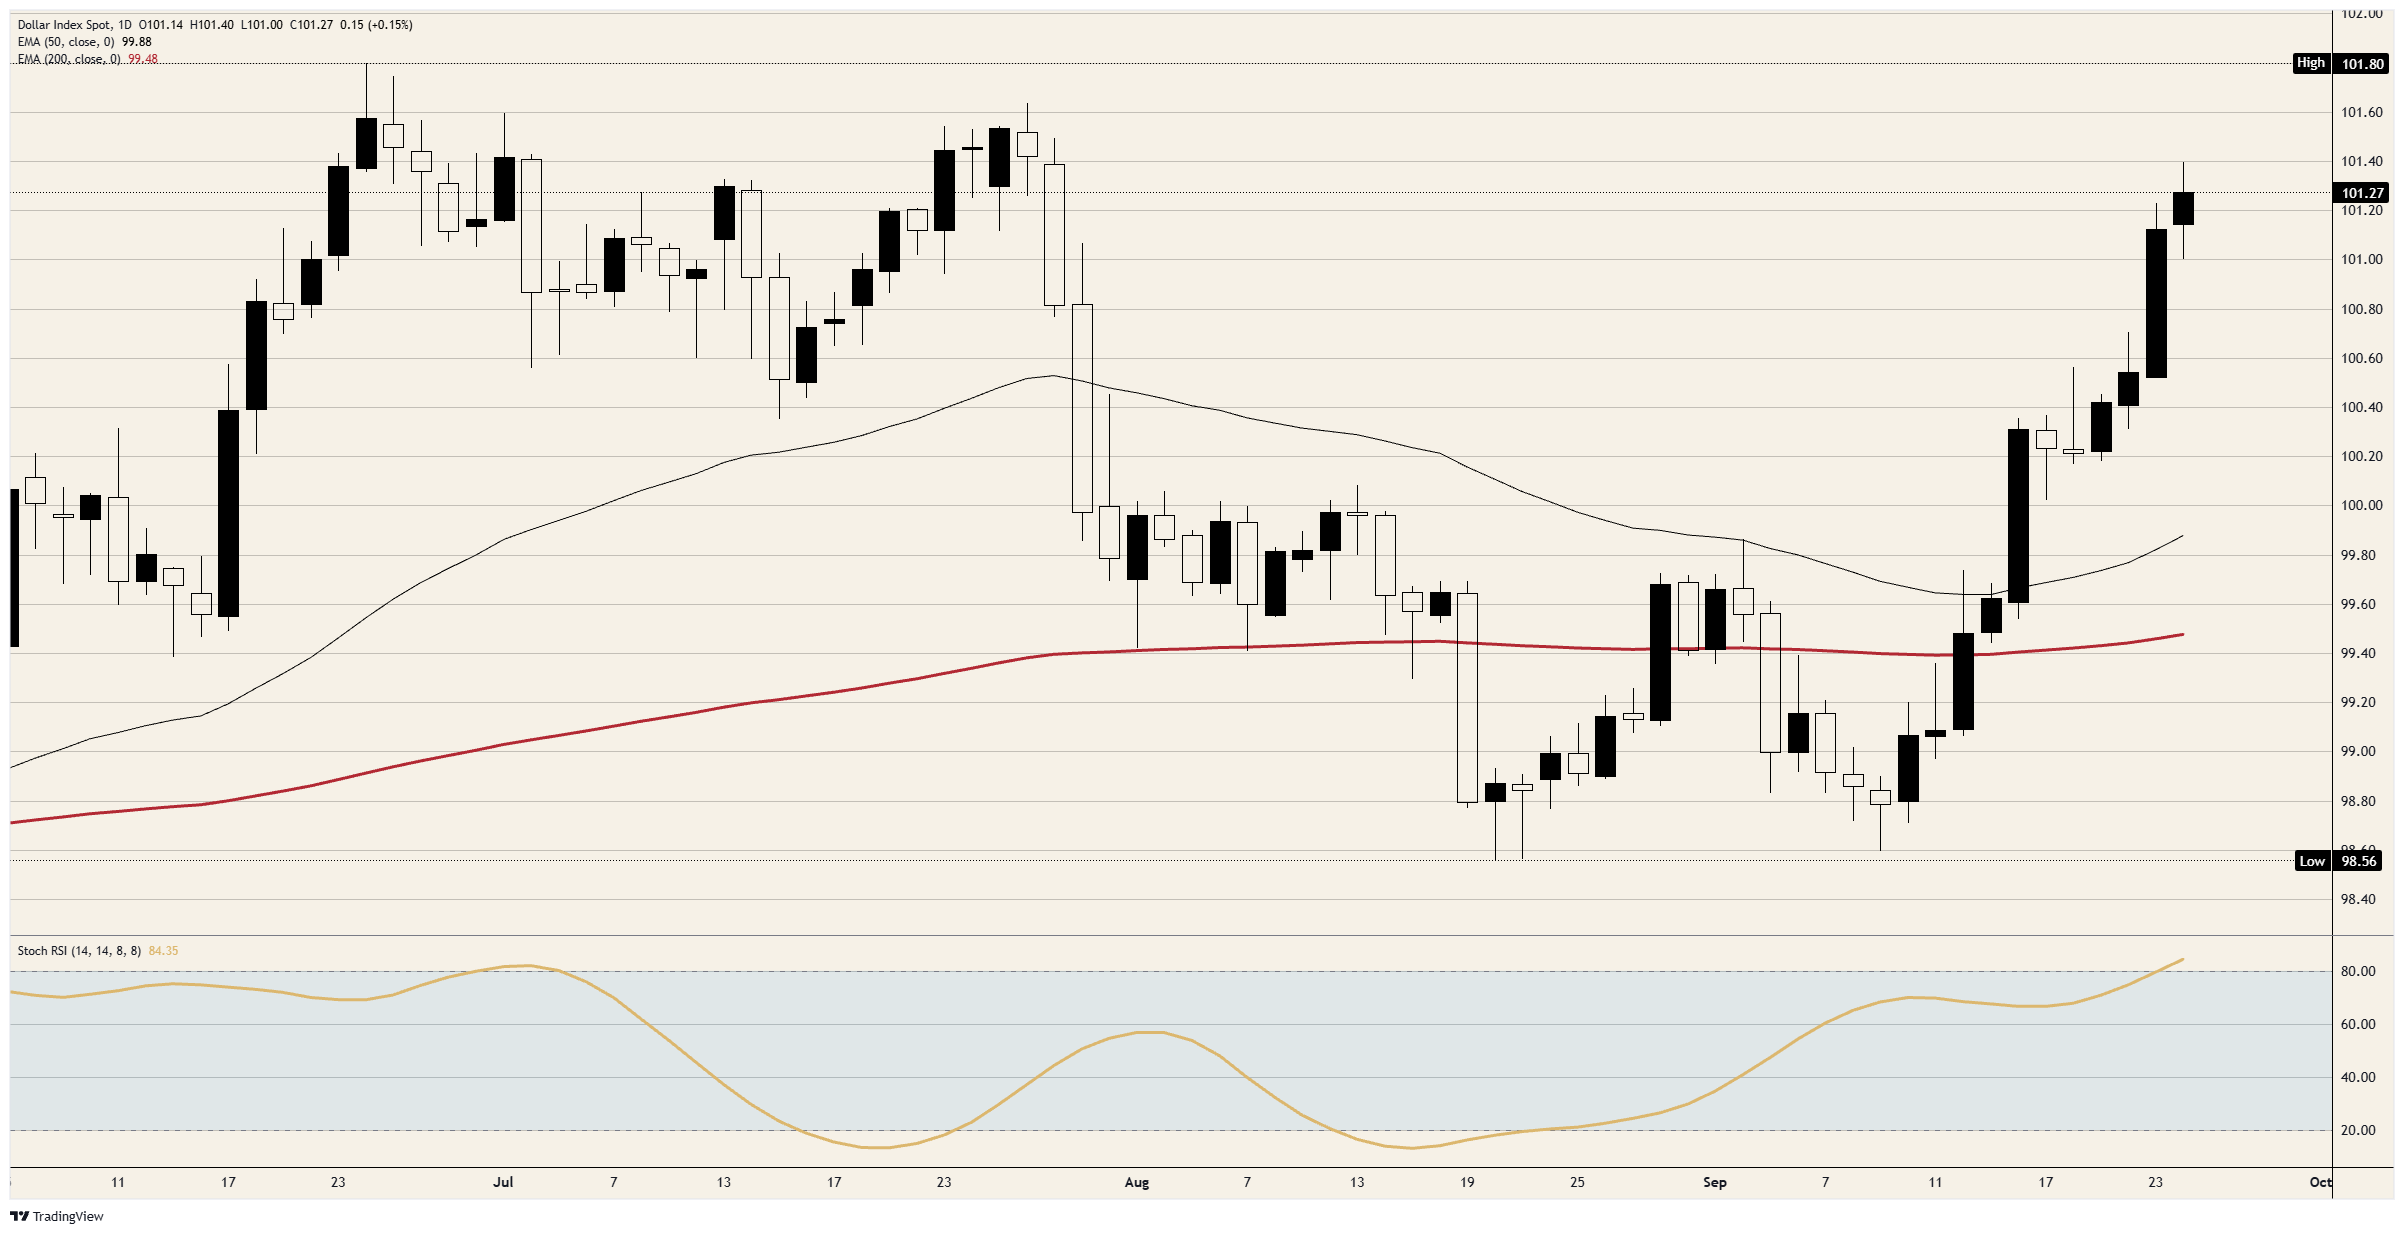
Resistance: Thursday's high near 101.40 is the highest since late July and came in under the late-July top just above 101.50, set on July 28 before the index turned lower. Above that, the June peak near 101.80 is the top of the range on the daily chart.
Support: 101.00 is the level Wednesday's run went through, and Thursday's low held right on it. Below that, 100.50 is where Wednesday's rally started.
Bias: The setup sits with the bulls above 101.00. The late-July top just above 101.50 comes first and the June peak near 101.80 after it. Momentum on the daily Stochastic Relative Strength Index (Stoch RSI) is at about 84, its first reading above 80 since early July, so the run is stretched and could pause without turning. A daily close below 100.50 ends the long case.
DXY daily chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.