The Pound climbs back to the top of its range as bond yields ease
- GBP/USD climbs back above 1.3250 as bond yields ease off multi-decade highs.
- Traders price about an 85% chance of a Bank of England hike on November 5.
- Fed minutes due Wednesday, from a 12-0 hike with 16 of 18 seeing another.
Tuesday's rise in GBP/USD came from the Dollar side. The pair was flat through Bank of England (BoE) external member Mann's warning on inflation, then gained at the same two points in the session as EUR/USD, leaving EUR/GBP close to unchanged. GBP/USD trades just above 1.3250, back near the top of the range it has held since September 24.
Treasury yields came off Monday's 24-year high, and Brent slipped below $100 a barrel as Gulf Crude Oil exports recovered. Lower US yields cut what investors earn for holding Dollars, and cheaper Crude Oil eases the inflation worry that pushed those yields up. Brent still costs close to 40% more than before the war, which makes it cheap only by September's standards.
Four BoE votes to cut in February, three to hike in September
External member Mann said on Tuesday that above-target inflation has become embedded in Britain. She expects it to reach about 4% around the turn of the year, when most pay deals are struck. Mann voted for a quarter-point hike to 4% in July and September, alongside Chief Economist Pill and external member Greene. The UK's Bank Rate has been 3.75% since December 2025, and traders price about an 85% chance of a hike on November 5.
That pricing is part of why GBP/USD has held its range while EUR/USD fell to a 17-month low on Monday. The European Central Bank (ECB) has raised rates twice since the war began on February 28 and the BoE not at all, and it's the Euro that made the new low. A November hike is close to fully priced, so GBP/USD has little more to gain from the BoE unless its speakers point to a second one.
One switched vote only turns the BoE's 6-3 into 5-4
Britain has no data on the calendar through Friday. External member Greene speaks on Thursday at 09:15 GMT and Deputy Governor Lombardelli at 13:00 GMT. Lombardelli voted to hold on September 17. The November hike traders price needs two of that six-member majority to change sides, so any sign she's one of them adds to the Pound's rate support.
The Federal Open Market Committee (FOMC) minutes, due Wednesday at 18:00 GMT, cover the September 16 hike to 3.75%-4.00%, which passed 12-0. Futures put an October hike near 20%, so minutes that show support for another move soon would lift the Dollar and send GBP/USD back toward the bottom of its range. It's possible the minutes show a committee less eager than its projections, though 16 of the 18 participants wrote down another hike this year.
Where the Pound's range ends
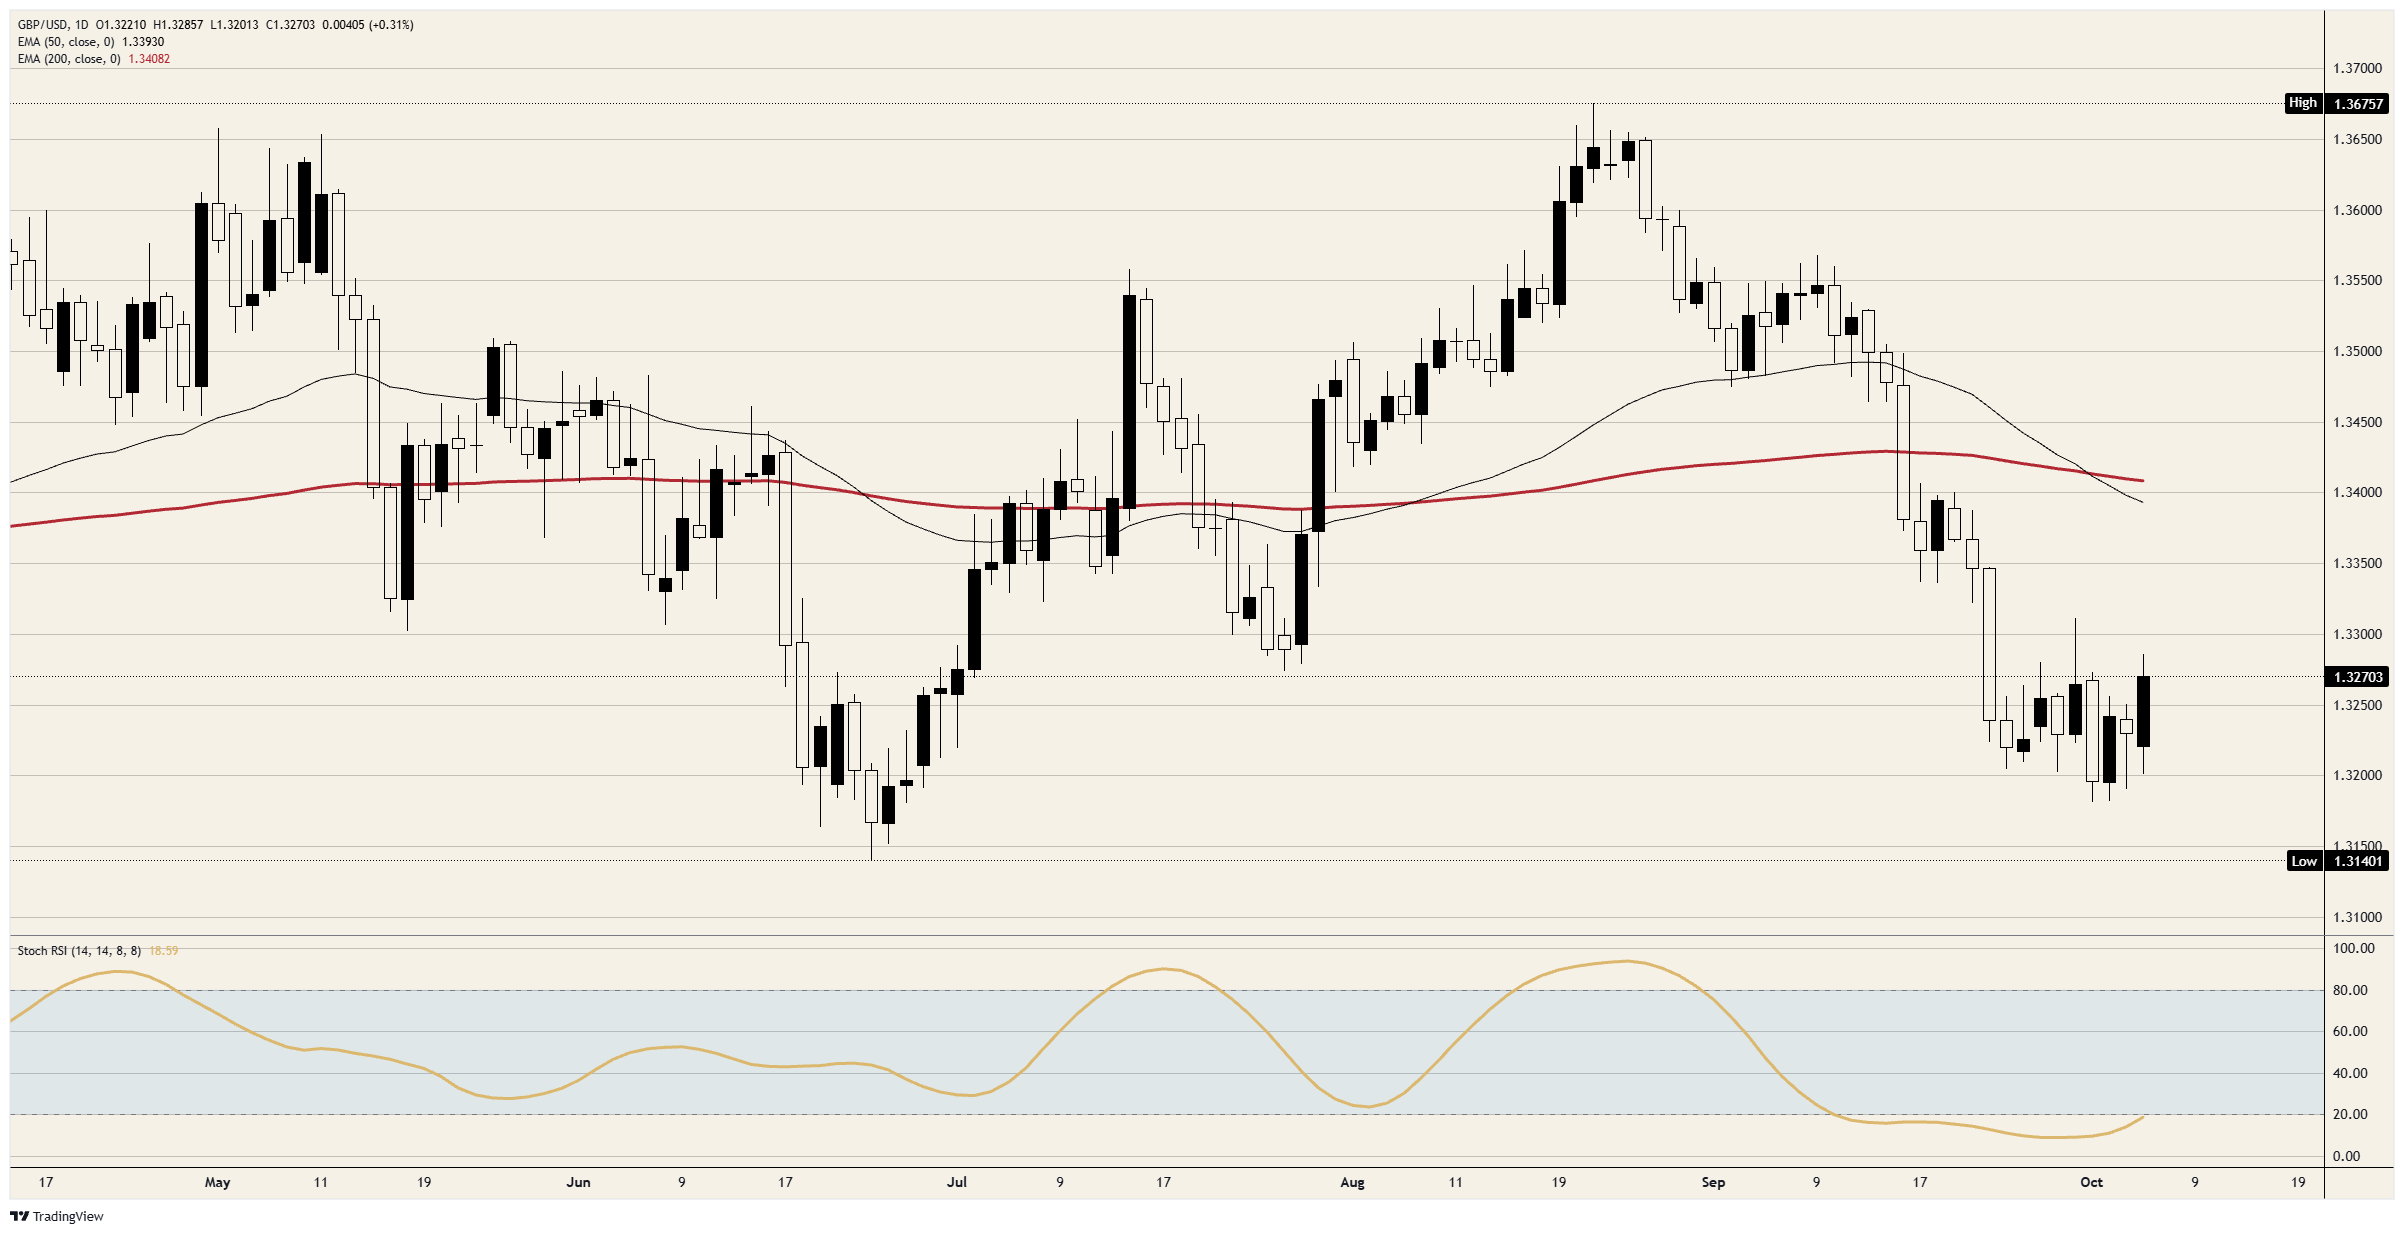
Resistance: Tuesday's high, just under 1.3300, is the highest since September 30, when a spike to just above 1.3300 marked the top of the range. 1.3350 is where the September 23 drop began.
Support: Every daily close from October 1 to Monday came in below 1.3250, which makes it the first floor now that the pair trades above it. October 1 and October 2 both bottomed just under 1.3200, the base of the range.
Bias: The lean is long while 1.3250 holds on a closing basis, with 1.3300 the first objective and 1.3350 the second. The daily Stochastic Relative Strength Index (Stoch RSI) has climbed for three sessions to near 19 and is about to cross back above 20, where it hasn't been since September 10. A daily close back under 1.3200 ends the call.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.