Indian Rupee gains further on RBI’s fresh measures to lower US Dollar’s demand
- The Indian Rupee advances further against the US Dollar on RBI’s new measures.
- India’s retail CPI grew faster than expected in September, bolstering the case for another RBI hike.
- Fed officials advocate for more interest rate hikes to tame inflation.
The Indian Rupee (INR) extends the Monday’s advance against the US Dollar (USD) on Tuesday, driven by the announcement of fresh Reserve Bank of India’s (RBI) US Dollar-related measures to shore up the domestic currency. In the opening session, the USD/INR pair tumbles 0.6% to near 95.00, the lowest level seen in over a month.
RBI unveils broad FX-support package
Analysts at MUFG highlight that the RBI has unveiled a “broad package of measures” to ease pressure on the INR, including “a special dollar window to meet dollar requirements by three state-run oil companies.” They add that the central bank has “stopped the re-booking of any FX derivative contract involving rupee that had been cancelled,” while also “introducing an FX risk reserve requirement on transactions that exceed $2mn,” underscoring a more stringent approach to managing currency risk.
A Reuters report has shown that Chinese authorities also used similar tools previously to discourage one-way bets against the Chinese Yuan (CNY).
Hot India retail CPI figures build case for more RBI hikes
India’s retail Consumer Price Index (CPI) data for September showed on Monday that inflationary pressures grew at a faster-than-expected pace. The CPI data arrived at 5.54% Year-on-Year (YoY), higher than 5.4% estimates and the previous reading of 4.83%. Inflationary pressures have increased significantly due to a significant increase in food prices, but are still within the RBI's tolerance band of 2%-6%.
Economists at Societe Generale point out that “inflation has now risen every month since January and remained above the RBI’s 4% target for four consecutive months,” underscoring that the recent upturn “is no longer merely a temporary food-price disturbance.” They add that “more concerning, however, is the evidence that inflation is becoming increasingly broad-based,” with price pressures extending beyond volatile food components. Against this backdrop, Societe Generale notes that “with the RBI projecting inflation at 6.0% in 3QFY27 and 5.7% in 4QFY27, the September print strengthens the case that the October rate increase marks the beginning, rather than the end, of the tightening cycle.”
US CPI data in focus
This week, the US CPI data for September is expected to have a significant influence on the US Dollar. The data on Wednesday will likely show that the headline inflation rose to 3.7% Year-on-Year (YoY) from 3.4% in August. The core CPI – which excludes volatile food and energy items – is seen arriving at 2.5% YoY, higher than the previous reading of 2.4%.
The inflation data is expected to impact the Federal Reserve’s (Fed) interest rate expectations. Fed officials have already signaled more interest rate hikes, warning of persistent inflation risks.
Hammack leans hawkish as inflation mindset fears bolster Dollar
Fed’s Hammack delivered a notably more hawkish tone, with the 8.4/10 FXS Speechtracker score standing well above the 7.5/10 historical average, underscoring a stronger-than-usual push for tighter policy. The emphasis on the need for higher interest rates, a restrictive stance to secure the 2% target, and concern that an inflationary mindset is becoming ingrained—amid neutral financial conditions and broad, demand-driven price pressures including from AI—signals a preference for swift, smaller rate moves to reinforce the Fed’s anti-inflation credibility. Hammack’s focus on clarifying the reaction function and warning that firms are planning price hikes beyond cost increases points to a Fed bias toward further tightening, a backdrop that is typically supportive for the Dollar and negative for risk-sensitive currencies.
The FXS Fed Sentiment Index rose by 0.59 points to 138.92, reinforcing that the overall Fed tone remains firmly in hawkish territory, well above the neutral 100 threshold. The combination of an elevated index level and an above-baseline FXS Speechtracker score suggests that recent Fed communication, exemplified by Hammack, continues to lean toward tighter policy, a configuration that tends to underpin the Dollar while weighing on the Euro and other major peers.
USD/INR Technical Analysis
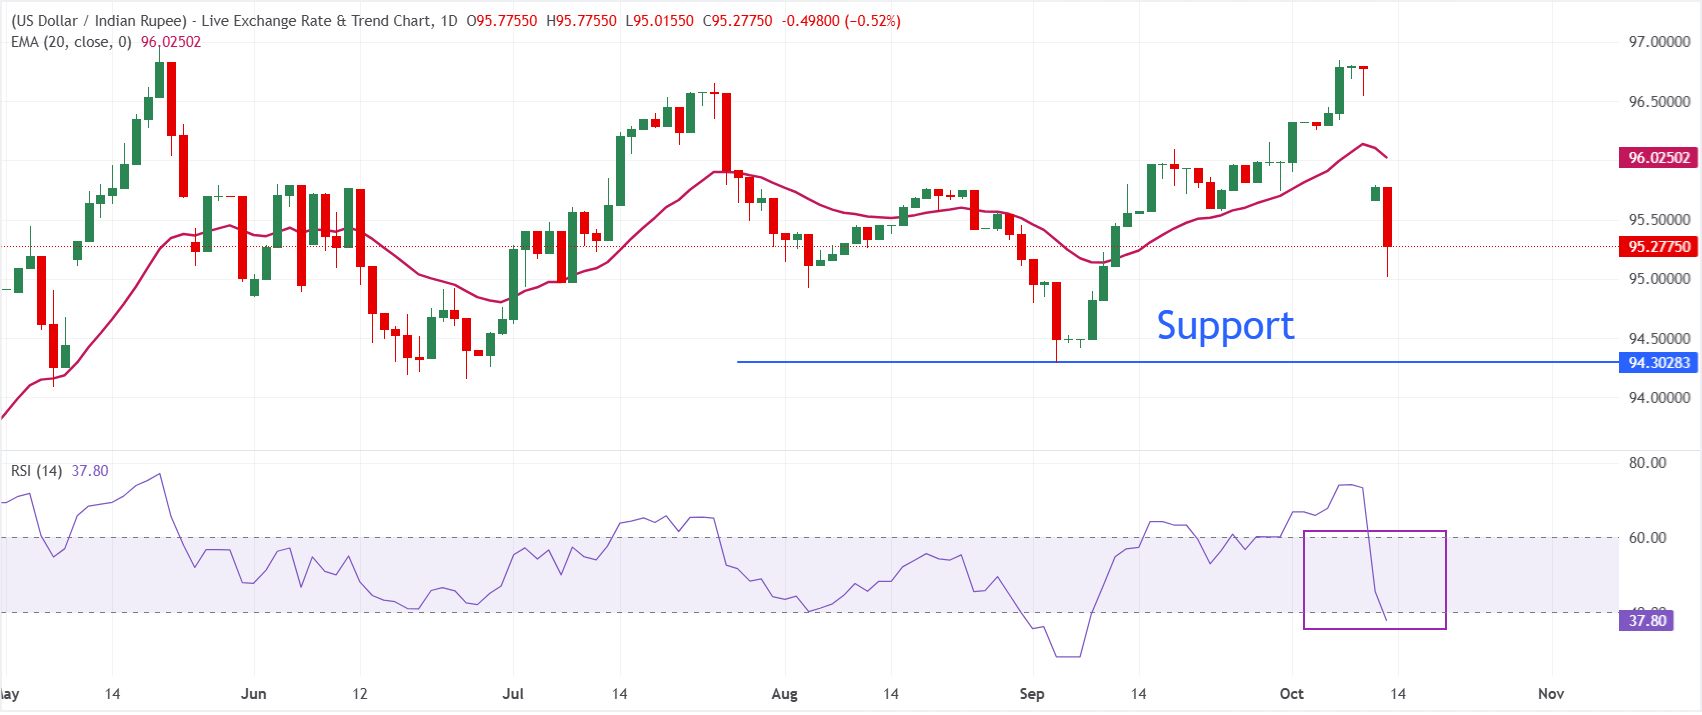
In the daily chart, USD/INR trades at 95.28. The pair remains under near-term bearish pressure as price holds below the 20-period exponential moving average (EMA) at 96.02, keeping the short-term trend capped.
The Relative Strength Index (RSI) at 37.8 stays below the neutral 50 line, hinting that bearish momentum is still in play, even though the market is not yet in oversold territory.
On the topside, immediate resistance is located at the 20-period EMA near 96.03, and a sustained break above this barrier would be needed to ease the current downside bias and open the way for further recovery. Looking down, the pair could extend its decline towards the September low near 94.30.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.