Why Gold and the Dollar are rising together today
Friday's jobs report was the most gold-friendly US data in months. Payrolls rose by 29,000 against about 85,000 to 90,000 expected, revisions cut 60,000 jobs from July and August, unemployment rose to 4.2 percent, and wages grew 0.1 percent on the month. October hike odds fell to about 20 percent or less, from about 70 percent earlier in the week. My gold price prediction for October 2026 remains intact.
Gold rose to about $4,239 at the open and then settled $40.00 lower at $4,162.30, ending the week down 3.6 percent. Silver settled at $60.42, down 6.7 percent on the week.
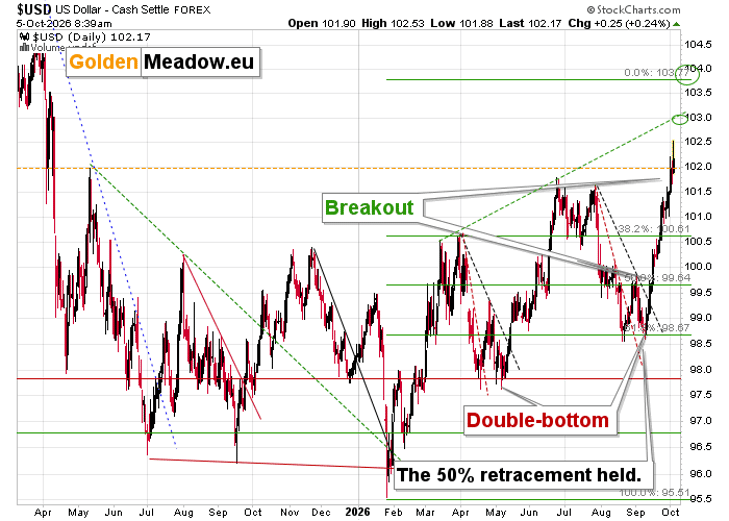
This morning, gold is up about $33 near $4,196, silver is up much more than gold, and the USD Index is also higher, trading above Thursday's high near 102.5 in Asia. Gold and the dollar rising together is the question of the day, and I'll answer it below. First, Friday.
The second failure in three sessions
On Friday, I wrote: "If a weak report fails to lift gold, it will be the second failure on bullish news in three sessions."
That is what happened. The report gave gold everything it usually wants: a weaker labor market, the slowest annual wage growth since May 2021, and a sharp drop in the odds of the next hike. Gold took the gain at the open and gave all of it back, and more, by the settlement.
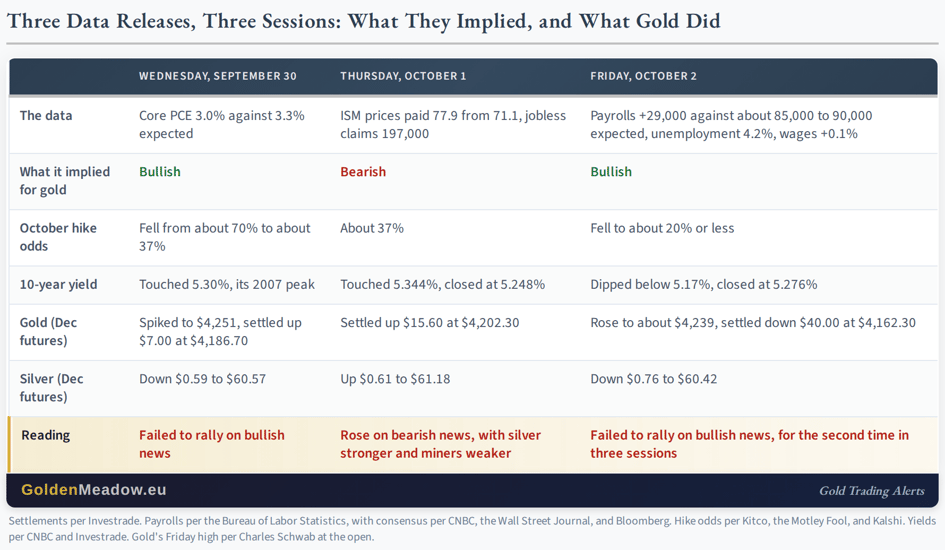
The explanation is the mechanism from Friday's alert. I wrote: "If the long end keeps rising, a softer Fed will most likely not lift the metal." On the jobs report, the 10-year yield dipped below 5.17 percent, then reversed and closed at 5.276 percent, higher on the day. The front end priced a softer Fed, the long end did not, and gold followed the long end.
Why stocks and Gold reacted in opposite directions
The same report sent the S&P 500 up 0.74 percent and the Nasdaq up 1.19 percent, while gold fell $40. Both reactions make sense once you separate the two ends of the bond market.
Stocks took their cue from the Fed. A company's value depends on what it will earn and on what it costs to finance the business, and the cost of money over the next year or two is anchored by the Fed's policy rate. Friday's report cut the odds of an October hike to about 20 percent or less, which lowered the expected cost of money in the near term. It also did not look like a recession: the unemployment rate rose largely because more people looked for work, participation rose to a four-month high, and the broadest measure of underemployment fell to its lowest since January 2025. A softer Fed without a broken economy is the combination stocks like most.
Gold took its cue from the long end. It pays no income, so its competition is what a long-term Treasury pays. That yield dipped below 5.17 percent on the release and closed at 5.276 percent, higher on the day, for the reasons I described on Friday: oil and diesel keep the inflation risk high, and the Treasury has a lot of debt to sell. On the same morning, the softer Fed made the financing outlook for companies cheaper, and the higher long yield made holding gold more expensive.
That is the configuration to watch. When the front-end falls and the long end rises, stocks tend to rally while gold falls on the same news. Gold needs both ends to fall together, with the dollar weakening. That happened on September 3, when gold rose 2.8 percent in a session, and it lasted one day.
Why Gold and the Dollar are rising together today
Gold usually falls when the dollar rises, so today's move needs an explanation. There are three parts to it.
First, the dollar's rise is about Europe, not about US interest rates. The euro fell to about 1.116, its lowest since May 2025, on fiscal worries in France, a selloff in European bonds, and reports that Spain is preparing for an early election. The euro is the largest part of the USD Index, so the index rose. That kind of dollar strength does not raise what an American investor earns on a Treasury, and gold's competition, the long-term US yield, is slightly lower this morning.
Second, oil is lower. Gulf exports are recovering, the G7 agreed on Friday to release 100 million barrels of crude and diesel from emergency stocks, and Saudi Aramco cut its November prices for Asia to the deepest discount since 2020. Cheaper oil lowers inflation expectations, which eases the long end, and that is the channel gold has followed all fall.
Third, gold priced in euros is rising more than gold priced in dollars. European investors facing stress in their own bond markets buy gold as a hedge, and that demand shows up in the dollar price as well. The same thing happened during the 2010 euro debt crisis, when gold and the dollar rose together for months, but at that time the Fed held rates at zero and was buying bonds. Today the Fed is still in a hiking cycle, and the 30-year yield is near its highest in 24 years.
So, today's move is a currency-specific dollar rally next to an oversold bounce in gold after a 3.6 percent weekly decline, and one large bank called gold oversold over the weekend. Neither changes the trend. The trend in gold has been set by US long-term yields and by the dollar's US-driven moves, and on Friday, when the US data moved, gold fell.
The practical takeaway: when gold and the dollar rise together, check which currency is driving the dollar. If it is the euro or the yen, the move says little about US rates and little about gold's trend.
Technically, the USD Index soared above its May 2025 high and is now verifying this breakout. Gold might slide once it’s clear that the USD Index held its ground.
Where this leaves us
Gold failed to rally on the weakest jobs report in months, the second failure on bullish news in three sessions, because the long end of the bond market kept rising. Today it is rising with the dollar, because the dollar's gain is about Europe and oil is easing, while silver leads the bounce as it led every bounce before a top this fall.
Friday's data told gold to rally, and it fell. Today's dollar told gold to fall, and it rose. The signal is in Friday's reaction.
Want free follow-ups to the above article and details not available to 99%+ investors? Sign up to our free newsletter today!
Author

Przemyslaw Radomski, CFA
Gold Price Forecast
Przemyslaw Radomski, CFA (PR) is a precious metals investor and analyst who takes advantage of the emotionality on the markets, and invites you to do the same. His company, Sunshine Profits, publishes analytical software that any

















