|

Tech rebounds, worries remain the same
The week started on a surprisingly, though cautiously, optimistic note ahead of a series of major central bank decisions and big company earnings.

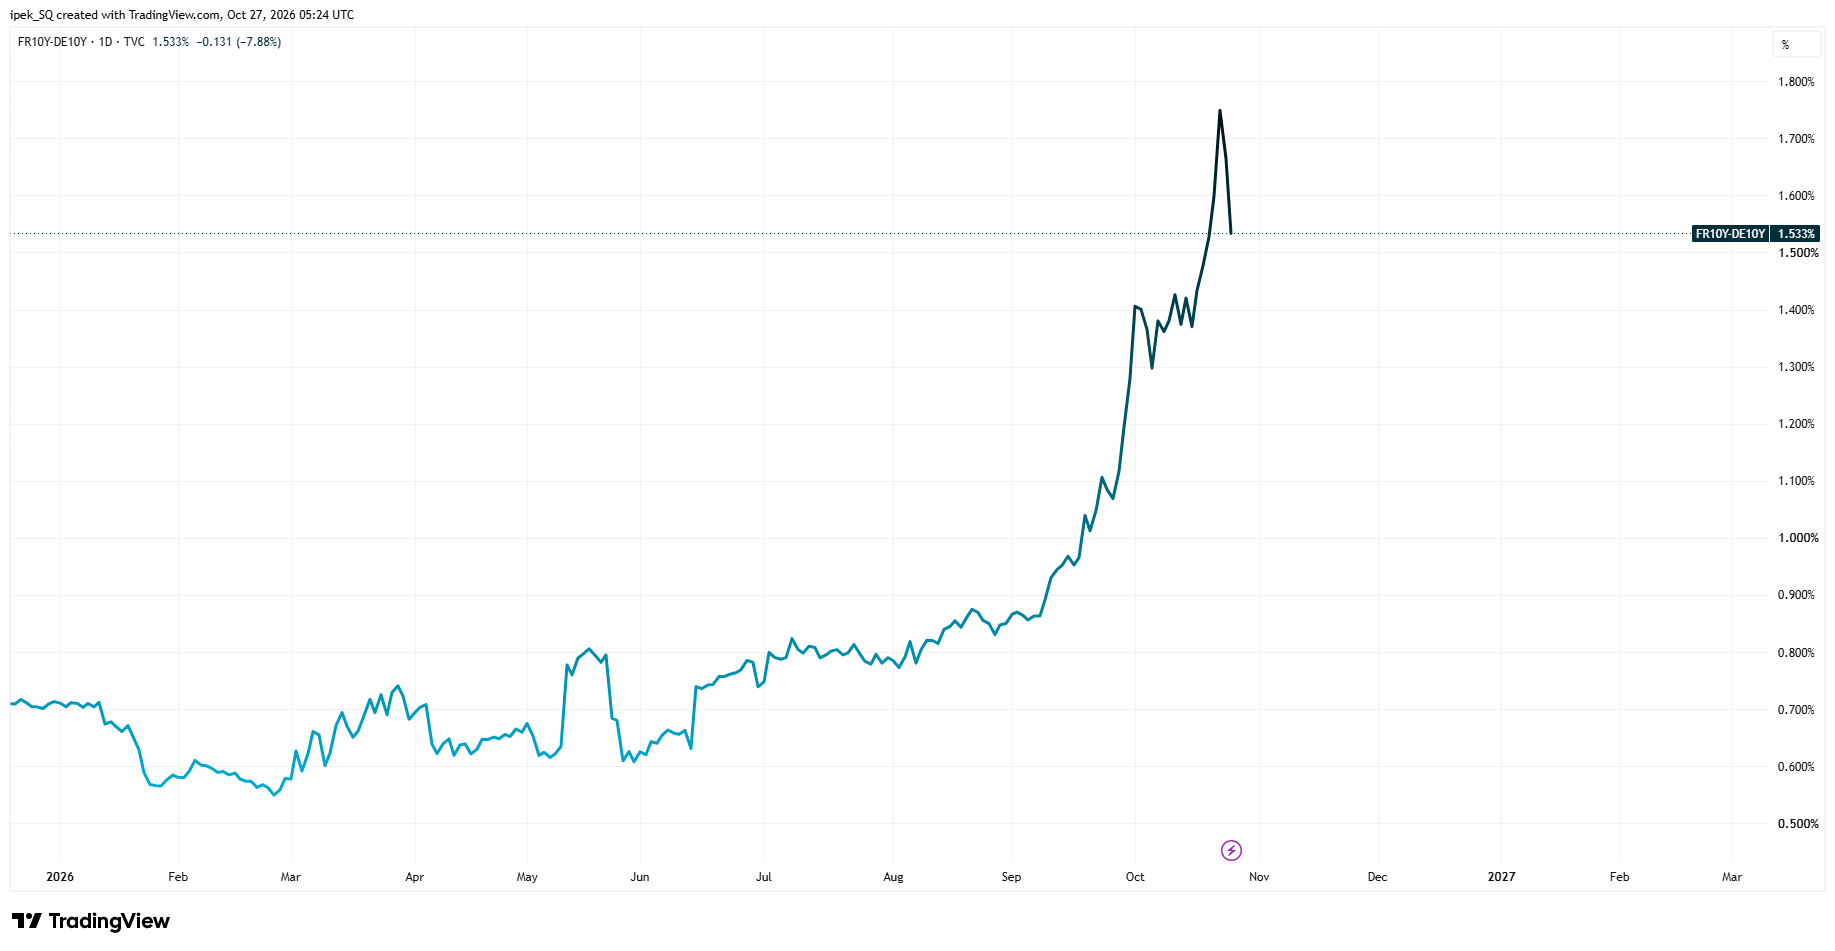
First, the French 10-year yield dropped to 4.90% despite a weekend of heavy protests. Moody’s surprise decision NOT TO downgrade France’s credit rating on Friday played a bigger role than the impasse in French politics. That’s partly because credit ratings can affect the value of bonds used as collateral: a higher rating can mean a lower haircut, allowing investors to borrow more against their holdings and potentially earn extra returns. So the for-now stable rating, though with a negative outlook attached, helped ease the pressure yesterday, also narrowing the spread versus the German bond yield to 153bp from as much as 176bp last week. The CAC 40 jumped along with other major European indices.
Chart

US indices also gained, though on both sides of the Atlantic Ocean, companies with exposure to Brazil underperformed as the MSCI Brazil ETF tanked as much as 27% in pre-market trading — yes, 27% — and finished the day with a 20% loss following Lula’s surprise victory in the weekend’s presidential election. The drop was mostly driven by worries about fiscal discipline under Lula and the reversal of the bullish trade ahead of the election, when investors bet on a victory by his opponent, Flávio Bolsonaro — son of former president Jair Bolsonaro — on expectations of tighter fiscal discipline and more market-friendly policies. However, the latter refused to concede and said he would seek to annul the result… bringing back uncomfortable memories of contested elections and raising questions about what could go WRONG around the upcoming US midterms next week!


Read the full article here.

Author

Ipek Ozkardeskaya

Ipek Ozkardeskaya began her financial career in 2010 in the structured products desk of the Swiss Banque Cantonale Vaudoise. She worked in HSBC Private Bank in Geneva in relation to high and ultra-high-net-worth clients.


More from Ipek Ozkardeskaya
Share:

Editor's Picks

AUD/USD eyes 100-SMA hurdle near 0.7035 as hawkish RBA counters firmer USD

AUD/USD regains positive traction on Tuesday and climbs to 0.7030 during the Asian session, reversing the previous day's corrective slide from a one-month high as hawkish RBA rate expectations continue to support the Aussie. Spot prices, however, remain below the 100-day SMA pivotal resistance amid a firmer US Dollar as traders brace for Australia’s September CPI report on Wednesday ahead of the Fed rate decision.

USD/JPY sticks to modest gains above 157.50 as traders await Fed, BoJ meetings

USD/JPY attracts buyers for the third straight day, recovering further from a one-month low ahead of Wednesday’s FOMC decision and the BoJ policy update on Friday. Meanwhile, expectations that the BoJ may hold off on aggressive rate hikes weigh on the Japanese Yen, and the US Dollar advances to a nearly two-week high, supporting the currency pair.

Gold bears flirt with $4,000 amid sustained USD buying ahead of FOMC decision

Gold meets with a fresh supply during the Asian session, stalling the previous day's modest bounce from the vicinity of a three-month low amid a firmer US Dollar. The precious metal, however, defends the $4,000 psychological mark as traders now seem hesitant and opt to wait for the outcome of the two-day FOMC policy meeting on Wednesday.

Pi Network stalls as weak crypto sentiment caps recovery

Pi Network (PI) holds steady above $0.0760 at press time on Tuesday, stalling after a roughly 2% rebound the previous day. The broader market's weak sentiment and reduced trading volume weigh on the PI token. The technical outlook is bearish, with price capped below a long-term resistance trendline and weak momentum.

France tests the Euro's nerve: What the OAT spread is telling FX traders
France's 10-year borrowing premium over Germany hit its widest since the 2011 debt crisis last week. With public spending above 57% of GDP, unrest on the streets and a presidential election next spring, cuts look unlikely. If Paris cannot trim, the bill may be paid quietly through financial repression.
What November 3 means for the Fed's rate path and the US Dollar

The USD faces a decisive period ahead of the November 3 midterm elections. While markets anticipate another interest rate increase from the Fed in December, the battle for control of Congress could reshape fiscal policy expectations and, indirectly, the path of US monetary policy in 2027.















