Tariff talks torpedoes markets again
USD: Mar '25 is Down at 108.500.
Energies: Mar '25 Crude is Down at 71.58.
Financials: The Mar '25 30 Year T-Bond is Down 21 ticks and trading at 113.23.
Indices: The Mar '25 S&P 500 emini ES contract is 8 ticks Lower and trading at 6020.25.
Gold: The Feb'25 Gold contract is trading Down at 2843.20.
Initial conclusion
This is not a correlated market. The USD is Down and Crude is Down which is not normal, and the 30 Year T-Bond is trading Lower. The Financials should always correlate with the US dollar such that if the dollar is Higher, then the bonds should follow and vice-versa. The S&P is Lower and Crude is trading Lower which is not correlated. Gold is trading Lower which is not correlated with the US dollar trading Down. I tend to believe that Gold has an inverse relationship with the US Dollar as when the US Dollar is down, Gold tends to rise in value and vice-versa. Think of it as a seesaw, when one is up the other should be down. I point this out to you to make you aware that when we don't have a correlated market, it means something is wrong. As traders you need to be aware of this and proceed with your eyes wide open. Asia traded Higher with the exception of the Shanghai and Singapore exchanges. All of Europe is trading Higher except the London exchange which is fractionally Lower.
Possible challenges to traders
-
Jolts Job Openings is out at 10 AM EST. This is Major.
-
Factory Orders m/m is out at 10 AM EST. This is Major.
-
RCM/TIPP Economic Optimism - tentative. This is Major.
-
FOMC Member Bostic Speaks at 10 AM EST. This is Major.
-
FOMC Member Daly Speaks at 2 PM EST. This is Major.
Traders, please note that we've changed the Bond instrument from the 10 year (ZN) to the 2 year (ZT). They work exactly the same.
We've elected to switch gears a bit and show correlation between the 2-year Treasury notes (ZT) and the S&P futures contract. The YM contract is the Dow Jones Industrial Average, and the purpose is to show reverse correlation between the two instruments. Remember it's likened to a seesaw, when up goes up the other should go down and vice versa.
Yesterday the ZT Migrated Higher at around 7 AM EST with no economic news in sight. The Dow moved Lower at the same time. Look at the charts below and you'll see a pattern for both assets. The Dow moved Lower at 7 AM EST and the ZT moved Higher at around the same time. These charts represent the newest version of Bar Charts, and I've changed the timeframe to a 15-minute chart to display better. This represented a Long opportunity on the 2-year note, as a trader you could have netted about 20 plus ticks per contract on this trade. Each tick is worth $7.625. Please note: the front month for ZT is now Mar '25 and the Dow is now Mar '25. I've changed the format to filled Candlesticks (not hollow) such that it may be more apparent and visible.
Charts courtesy of barcharts
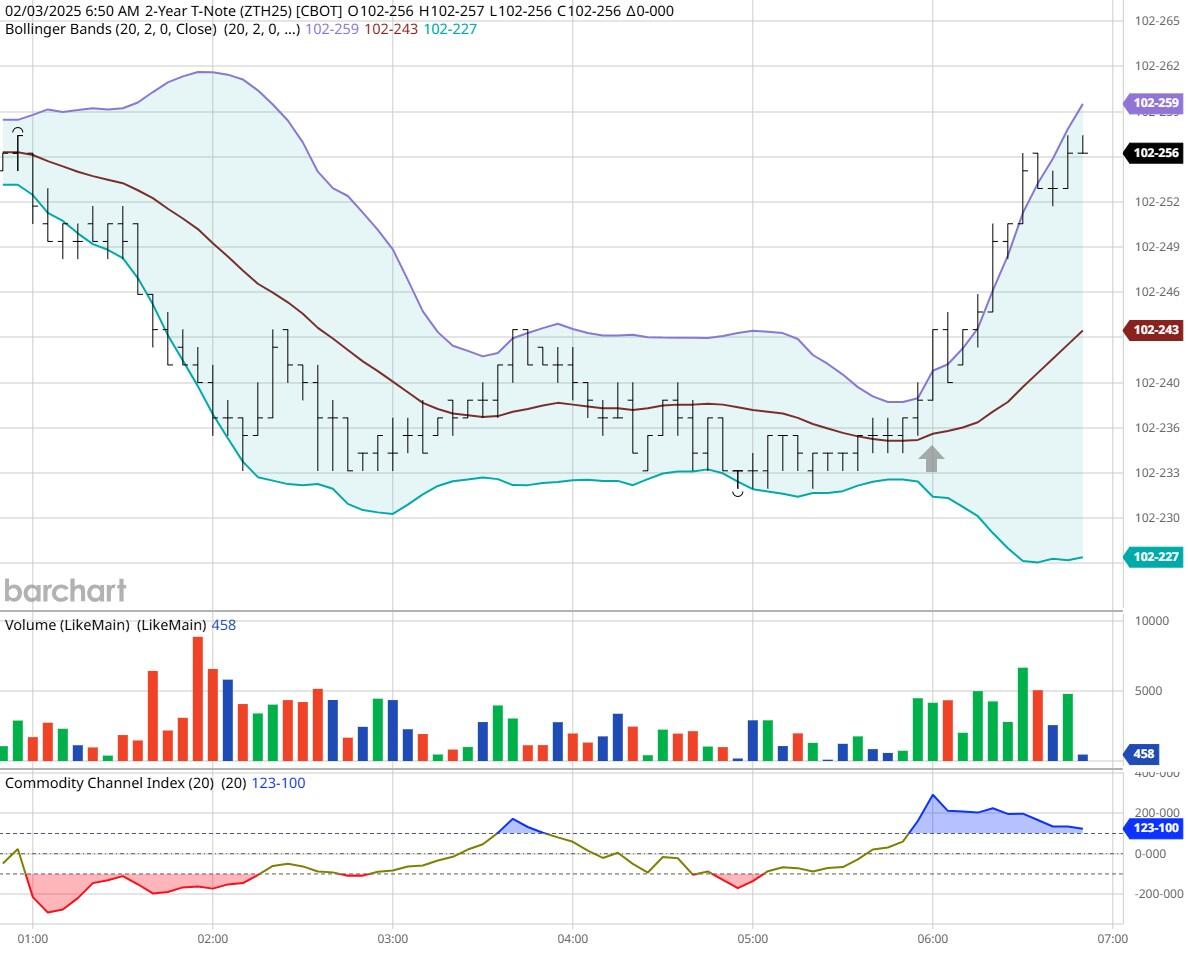
ZT -Mar 2025 - 2/03/25
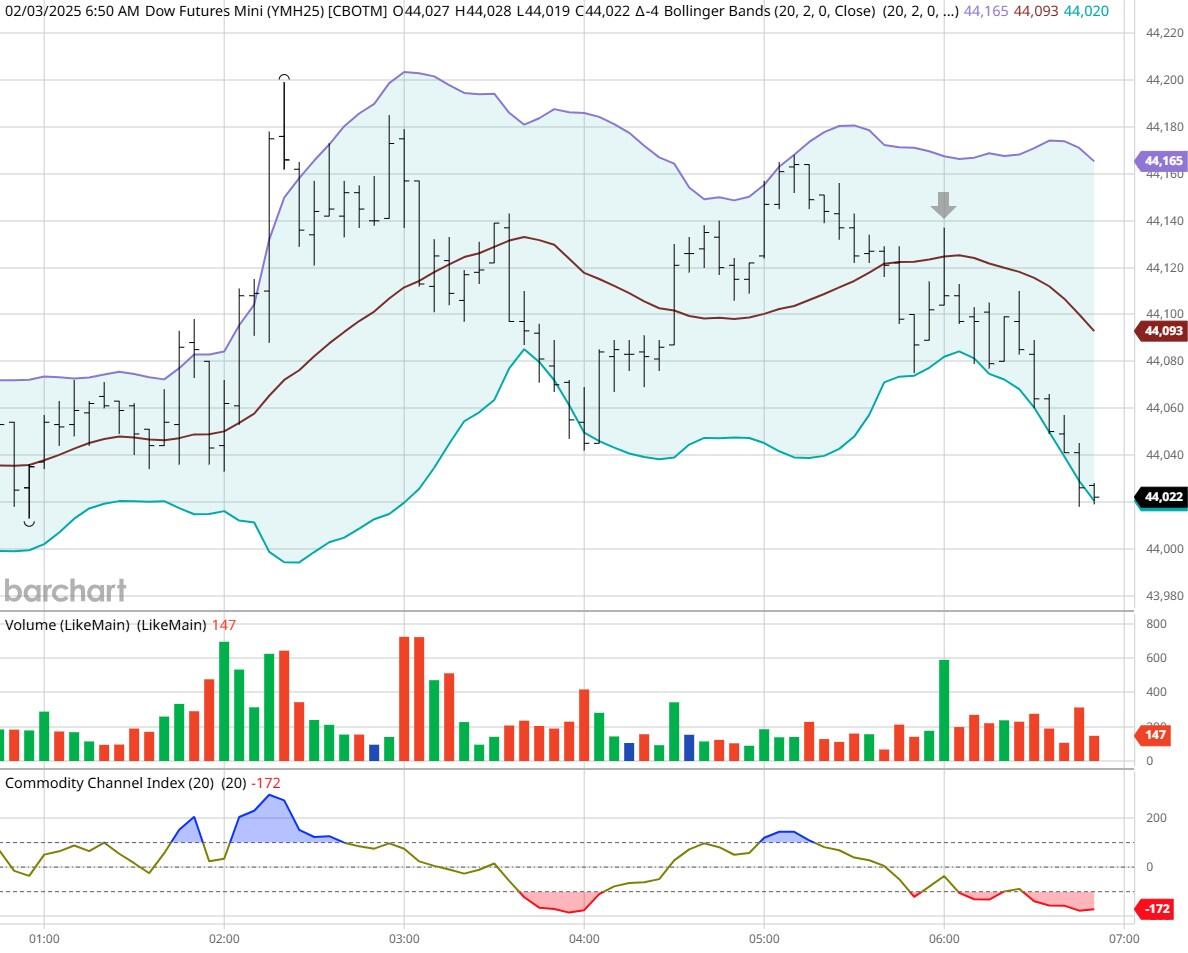
Dow - Mar 2025- 2/03/25
Bias
Yesterday we gave the markets a Downside bias as just about every instrument we use for Market Correlation purposes was trading Higher and this usually reflects a Down Day. The markets didn't disappoint as the Dow closed Lower by 123 points and the other indices traded Lower as well. Today we aren't dealing with a correlated market, and our bias is Neutral or Mixed.
Could this change? Of Course. Remember anything can happen in a volatile market.
Commentary
Yesterday was a continuation of what we witnessed on Friday. There is no speculation on tariffs for Mexico, Canada and China. The markets opened Lower and remained in negative territory the entire session. This will no doubt lead to Higher prices that we the consumer will pay. The markets traded much Lower yesterday but Mexico decided to hold off increasing tariffs by one month so that helped somewhat but have no doubt this will become a full-scale trade war, and no one wins that. Latest update: tariffs are postponed for one month for Canada and Mexico. Could this change? You bet. Want to learn Market Correlation and determine market direction hours before the Opening Bell?
Author

Nick Mastrandrea
Market Tea Leaves
Nick Mastrandrea over 20 years experience in trading and formerly held a NASD Series 7. He currently holds a NJ Life, Health and Variable Authority. Nick is a published writer and his work has appeared in Futures Magazine, TraderPlanet and others.

















