|

NFPs expectations

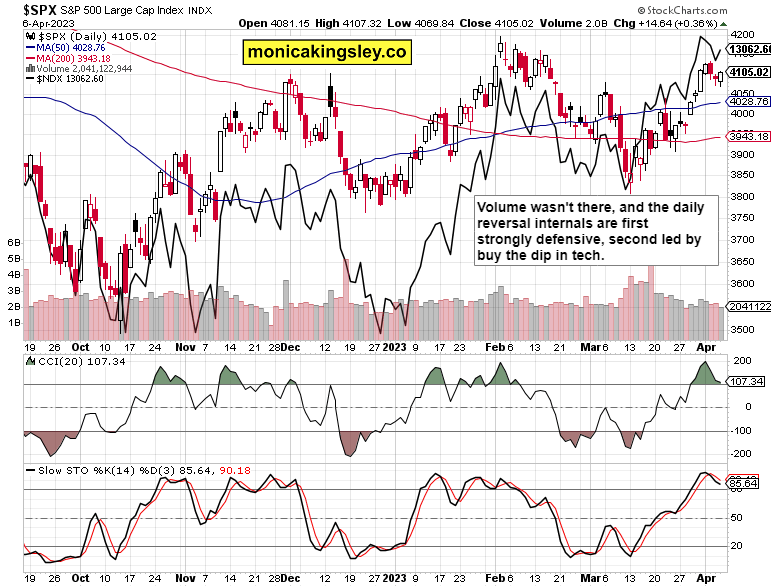
S&P 500 bears missed a good opportunity Friday, and for all the anticipated deterioration in unemployment claims, couldn‘t keep the pressure on. Niether semiconductors, nor financials, nor Russell 2000 were enthusiastic, let alone value stocks – industrials and materials were limping too, testifying to the defensives led daily reversal (utilities and consumer staples, followed then by healthcare). Above all, tech had a good day, but the advance-decline line turned barely positive, new highs new lows are lagging, and only advance-decline volume saved the day.

Bottom line, the bear market rally upswing is still suspect, and stocks are overvalued both on E and P/E basis given that no no landing is ahead.

Conversely, today‘s non-farm payrolls can be counted on to prove disappointing to the bulls. Anything above 240K (even with all the adjustments and other statistical tools employed), can‘t be expected, and given the most recent JOLTS, I wouldn‘t be surprised by at best a low 200K figure, or more probably by a data point starting with 1xxK.

And given the finally again „bad is bad“ dynamic, it means that S&P 500 is likely to react to the figure risk-off, with a downswing once trading gets underway again.
SPX

Happy (Catholic) Easter holidays if you celebrate & enjoy the long weekend!

Author

Monica Kingsley

Monica Kingsley

Monicakingsley

Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.


More from Monica Kingsley
Share:

Editor's Picks

AUD/USD stays defensive below 0.7150 after Chinese data

AUD/USD remains on the back foot below 0.7150 in the Asian session on Tuesday, close to an over three-week low touched the previous day. US bond yields hold near multi-year highs ahead of the FOMC meeting and oil-driven inflation risks, supporting the US Dollar and weighing on the currency pair. Mixed Chinese activity data for August also fail to inspire the Aussie.

USD/JPY extends gains toward 155.00 amid USD resurgence

USD/JPY keeps pushing higher toward 155.00 early Tuesday, looking for more upside, as traders await the FOMC and BoJ meetings this week. Meanwhile, Fed rate-hike bets and oil-driven inflation risks keep US bond yields near multi-year highs, supporting the US Dollar and the pair. That said, a more hawkish repricing of the BoJ normalization path might continue to underpin the Japanese Yen and could limit USD/JPY's upside. .

Gold struggles near multi‑week low as Fed hike bets and geopolitical risks boost USD

Gold drifts lower for the second straight day, and trades around the $4,265-$4,264 region, down 0.80% during the first half of the European session on Tuesday. The commodity remains within striking distance of an over one-month low, which it touched on Monday, as traders keenly await the crucial two-day FOMC policy meeting, starting later today.

Dogecoin clings to EMA support as recovery lacks conviction
Dogecoin (DOGE) hovers around $0.083 at the time of writing on Tuesday after finding support around the key support zone the previous day. Quiet institutional demand, along with mixed derivatives positioning, suggests fading interest in the dog-themed meme coin.
Markets slide as FOMC approaches
The US Dollar remains strong as markets turn increasingly cautious ahead of the FOMC. Stocks are tumbling, while Gold and Silver are moving lower under pressure from the stronger Dollar. The Japanese Yen is weaker again, while Crypto is correcting. BTC is approaching a key technical test and could fall below its 50-week moving average, while ETH remains above $2,405.
Venezuela’s 65-billion-barrel Oil deal could reshape America’s inflation fight
The United States (US) has secured unprecedented access to part of Venezuela’s vast Oil reserves. The timing is particularly significant as the war with Iran is disrupting Middle Eastern supplies, keeping energy prices elevated and reviving concerns about inflation.















