EUR/USD Weekly Forecast: Market players await fresh clues
- Fresh Middle East tensions spell caution but have no relevant impact on mood.
- United States Consumer Price Index may revive volatility in the upcoming days.
- EUR/USD in a lost battle to recover its bullish strength.
The EUR/USD pair finishes an uneventful week unchanged, just a handful of pips above the 1.1400 mark. Financial markets held cautiously throughout the week, trapped between little macroeconomic guidance and tensions in the Middle East.
What’s happening between the United States and Iran?
Washington and Tehran reached an agreement, the Memorandum of Understanding (MoU), in mid-June. The 14-point document aimed to end the Middle East conflict by establishing a 60-day ceasefire in which both parts agreed to continue negotiating to reach complete peace.
Yet, the sticky points that generated tensions remain in place: on the one hand, the United States (US) wants Iran to drop all nuclear developments. On the other hand, Iran wants full control of the Strait of Hormuz. Both firmly oppose each other's requests, and there is no progress in negotiations towards such points.
But the US and Iran are not the only players. Israel and Lebanon are also part of the conflict and the historical conflict between them seems nowhere near changing status.
Over the last few days, a series of cross-attacks around the Strait of Hormuz and US President Donald Trump stating that the MoU was over fueled concerns about a steeper escalation, although not enough to trigger panic. Nevertheless, the US Dollar (USD) came under pressure.
As commented in previous updates, market sentiment can be easily measured through Oil prices. By Friday, the barrel of West Texas Intermediate (WTI) trades at around $71.50, barely up on a weekly basis, a sign that concerns are present, but not enough to trigger relevant market reactions.
Hopes for a resolution of the conflict are little, yet with stable Oil prices and more or less fluid transit through the Strait of Hormuz, the Middle East war is not much of a concern for speculative interest.
Mixed signs from Europe
Data coming from the European Union was mixed. The Eurozone Sentix Investor Confidence Index improved to -3.1 in July, from -13.4 in June. May Retail Sales were up a modest 0.2%, better than the previous -0.3%, although slightly worse than the 0.3% expected. More relevant, the Producer Price Index (PPI) in the same period rose 5.9% YoY, higher than the previous 5% and the expected 5.7%.
More or less stable economic developments alongside continued inflationary pressures seem to be the new norm, although the PPI uptick did not take its toll on the Euro, given that it is May data. Markets, however, may become more concerned if inflation continues its bullish route in June, when Oil prices receded amid the MoU. More concerning, and a probable panic trigger, would be July data if price pressures remain up despite the latest war developments.
What's up with the US?
The US macroeconomic calendar included the ISM Services Purchasing Managers’ Index (PMI), which came in at 54 in June as expected, yet slightly below the previous 54.5. On a positive note, the Prices Paid sub-index retreated from 71.3 in May to 67.7, hinting at easing inflationary pressures.
Additionally, the Federal Open Market Committee (FOMC) released the June meeting Minutes, which leaned hawkish, as expected. Policymakers unanimously agreed to maintain interest rates unchanged while seeing elevated inflation risks.
Finally, the Federal Reserve (Fed) announced the leadership and objectives of its task forces to advance the conduct of monetary policy on Thursday. “The Fed's commitment to price stability and maximum employment is unwavering. As is our resolve to pursue our mandate with rigor,” said Chairman Kevin Warsh.
What’s next in the docket
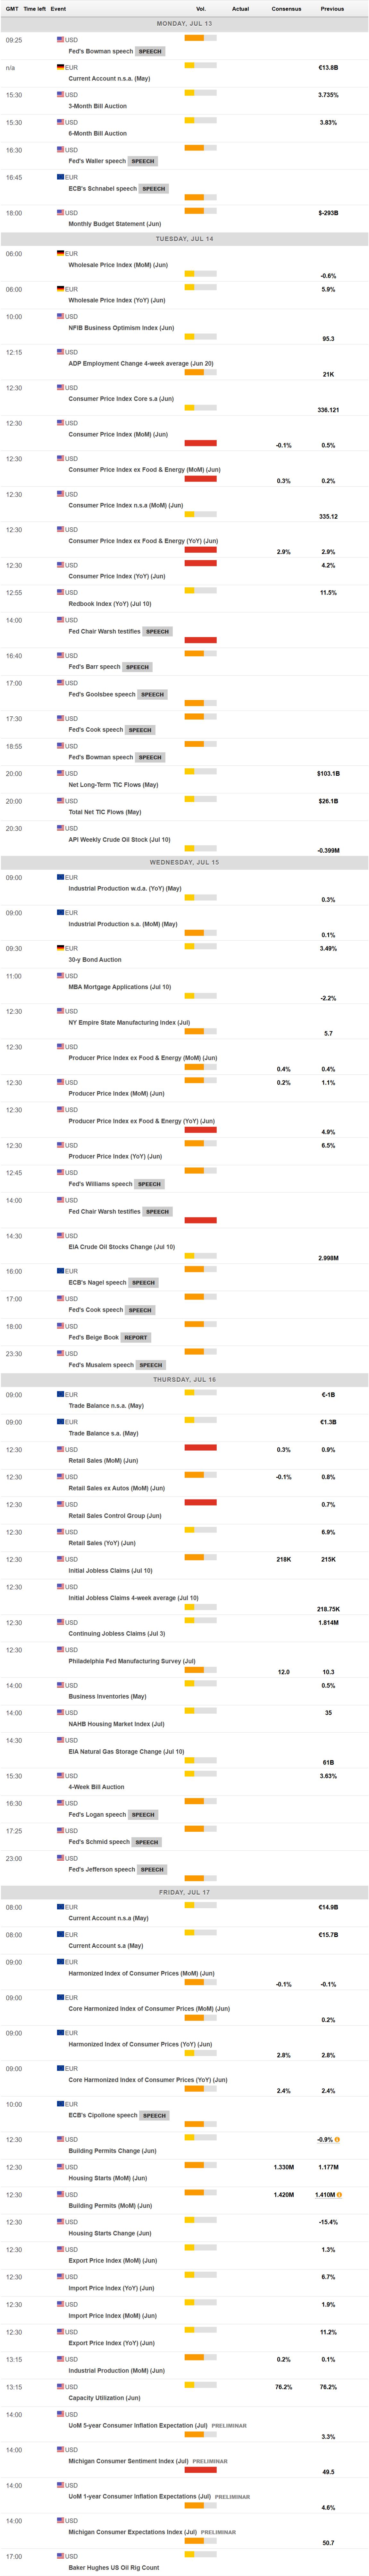
The most relevant event these days is the release of the US Consumer Price Index (CPI) on Tuesday, followed by Fed Chair Kevin Warsh’s testimony before Congress on Tuesday and Wednesday. Other than that, the country will publish June Retail Sales and the preliminary estimate of the July Michigan Consumer Sentiment Index.
The Eurozone calendar has little to offer, but the May Trade Balance and the final estimate of the June Harmonized Index of Consumer Prices (HICP).
Fed and European Central Bank (ECB) officials will be on the wires throughout the week, although the odds of them saying something relevant are low.
EUR/USD Technical Outlook:
The daily chart for the EUR/USD pair shows bears retain control. The pair remains below all its moving averages, while the 20‑day Simple Moving Average (SMA) at 1.1439 acted as intraday resistance throughout the week. The moving average maintains its downward slope below the longer ones, with the 100‑day SMA at 1.1604 and the 200‑day SMA at 1.1646. Technical indicators stabilized below their midlines, hinting at waning downside pressure but do not yet challenge the prevailing bearish structure.
On a weekly basis, EUR/USD is also bearish, as it holds below the short-term 20-period SMA at 1.1593 while remaining above the long-term SMAs. The price action suggests a corrective phase within a broader uptrend, with the 14-period Relative Strength Index (RSI) hovering near 42, hinting at subdued bullish momentum, and the negative 14-period Momentum reading reinforces fading buying interest.
On the topside, initial resistance emerges at the 20‑day SMA around 1.1439, followed by the 100‑day SMA at 1.1604 and then the 200‑day SMA near 1.1646, where a more significant supply zone converges. The 1.1400 mark stands as immediate support ahead of the recent multi-week low in the 1.320 price zone. A clear breach of the latter exposes the 1.1200 mark, en route to the 1.1000 psychological threshold.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.