Banks kick off earnings season, are you fading the CPI fear?

It is the start of earnings season for US equities, with major banks reporting this week. Let’s see how bank earnings pair up with the much anticipated CPI data on Tuesday morning.
After last week’s sudden Thursday dip and subsequent rebound on Friday to close at all-time highs in the $SPX, I hope the weekend has you feeling relaxed and rejuvenated. I say that because this week could provide some elements of fireworks; given the economic data on tap and the beginning of the Q2 earnings season.
The Banks.
In the second half of last week, our analyses focused on interest rates and the banks. In case you missed it, we were specifically looking at interest rates via TLT and banks via KBE. Friday was a great day for the banks...could this be a harbinger of things to come for bank earnings?
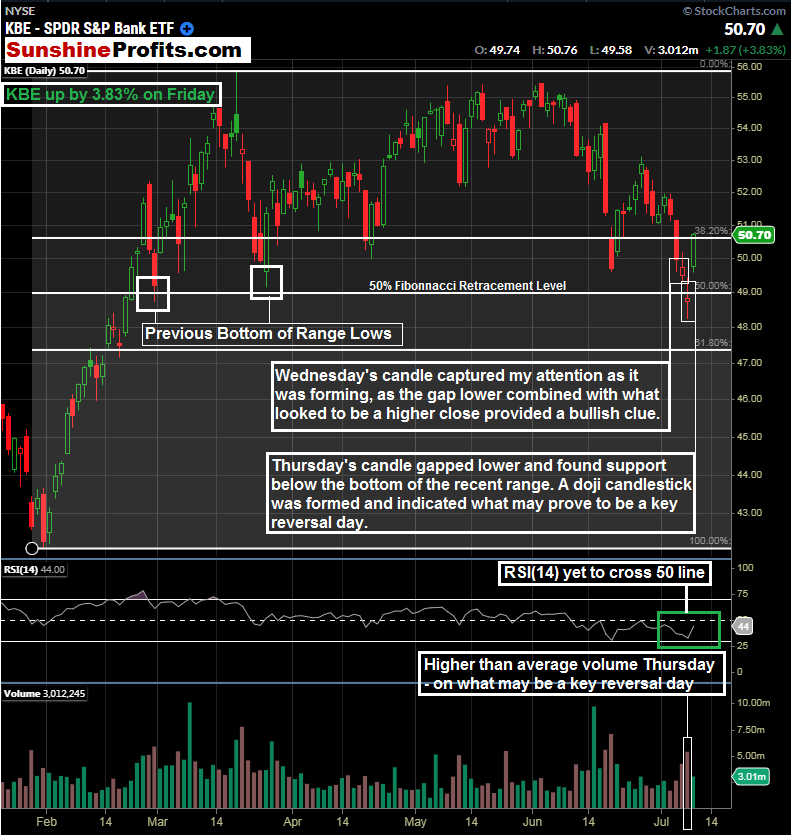
Figure 1 - KBE S&P 500 Bank ETF January 18, 2021 - July 9, 2021, Daily Candles Source stockcharts.com
Please refer to the July 6th publication where we analyzed KBE in depth. I think there are so many reasons to like the banks here. If you are a premium subscriber, you received an alert email on Wednesday regarding some intraday trading activity and levels.
Note that the RSI(14) has not even crossed the 50 line yet. These levels could indicate that there is still time to get on board the banks ahead of earnings. Some folks are fundamentally predicting a big bank's earnings season this week.
For example, we have Sam Stovall, chief investment strategist at CFRA Research looking for the second-best YOY quarterly gain in the last 25 years for the banks.
KBE tacked on 3.83% on Friday. If you recall, part of the reason we initially started to love the banks (KBE) was that it had pulled back over 9% from its 2021 highs; as the S&P 500 had continued to make new highs.
Putting that together with the technical action late last week and heading into earnings, it could be a great place to continue to be. We will be looking for exit levels in the coming days and weeks, with Premium Subscribers receiving the intraday alerts.
Interest Rate Action and Reaction
As banks surged on Friday ahead of earnings, interest rates rose along with them. That is part of a goldilocks scenario for banks. Has the time for banks come and the turn in interest rates along with it?

Figure 2 - Ten-Year Treasury Note Yield January 7, 2020 - July 9, 2021, Daily Candles Source stockcharts.com
Ten-year note yields rose on Friday in tandem with bank stocks. Please see the July 7th and July 8th publications for more detail on $TNX.
So far this morning, it has been a quiet session in equities and bonds. Since we have CPI data on tap for tomorrow at 8:30 AM, it is to be expected.
Our interest rate analysis led us to TLT and a potential long-term head in shoulders pattern being created. As bond yields rose on Friday, TLT fell nicely.
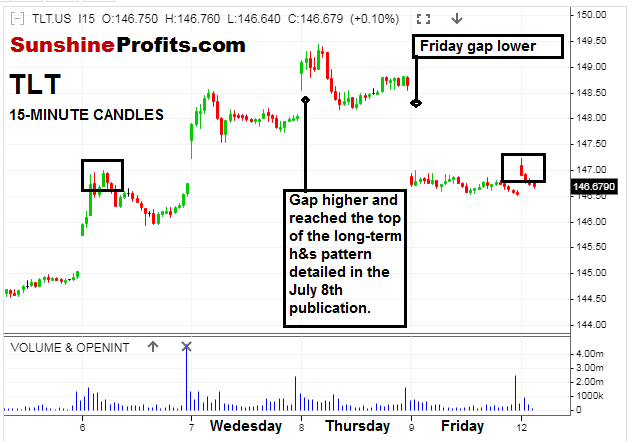
Figure 3 - TLT iShares 20+ Year Bond ETF July 2, 2021 - July 12, 2021, 10:35 AM, 15-Minute Candles Source stooq.com
The 15-minute candles in TLT show an exhaustion gap up to levels we were watching on Thursday; and a gap lower on Friday. Notice what may be a short-term head and shoulders pattern forming here on the intraday charts that coincides with the long-term head and shoulders pattern that we identified. I like to call this the matching pattern within the pattern. More on that another time.
This morning, we do see the equities beginning to gain a bit of steam and the bond yields dropping slightly. We have CPI data tomorrow morning, so it could be a quiet session as traders look to tomorrow's CPI release.
Are you fading the CPI data fear? Is it possible that tomorrow’s inflation data release is not so bad, and that the inflation is indeed transitory, as the Fed has spoken about on multiple occasions? I think there is a possibility of this, and it has never been a good idea to fight the Fed.
I like the idea of being long the banks and short bonds (higher interest rates) heading into tomorrow’s CPI release and this week’s bank earnings releases.
Want free follow-ups to the above article and details not available to 99%+ investors? Sign up to our free newsletter today!
Author

Rafael Zorabedian
Gold Price Forecast
After spending years as an active trader across several capital markets, Rafael earned his stripes as a former futures and options broker specializing in equity indices, energies, metals, and soft commodities.

















