Bank of Japan preview: The slow path to higher rates
The Bank of Japan is expected to keep rates unchanged on 31 July after last month’s 25bp hike to 1.00%. While some see scope for a faster tightening cycle and an October hike, we doubt any modest hawkish shift will materially boost the yen or alter the USD/JPY outlook.
Most agree that rates need to be higher
When raising the policy rate to 1.00% last month, the BoJ retained its tightening bias and concluded that a further removal of monetary accommodation would be required. As always, the timing of such an adjustment would depend on developments in economic activity, prices, and financial conditions.
Since that meeting in mid-June, the BoJ has seen strong retail sales figures and, perhaps most importantly, a buoyant Tankan business survey for the second quarter. Here, business optimism has returned to levels last seen in 2018 and likely provides comfort to the BoJ’s view that the virtuous cycle between company profits, higher wages, consumption and prices is ongoing.
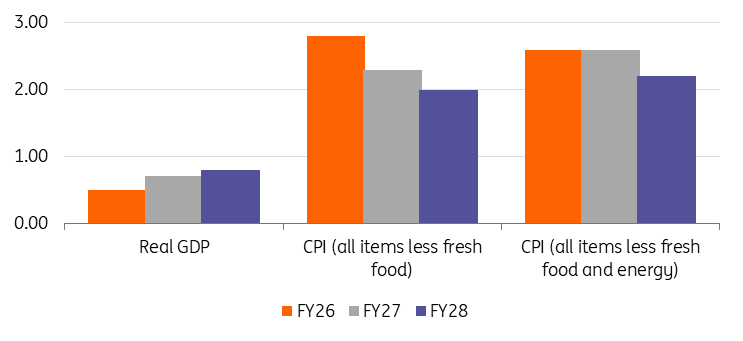
While the BoJ does acknowledge downside risks to growth from the Middle East conflict and higher energy prices, most expect it to stick to the script that higher demand from the global AI capex build-out continues to support global demand. This probably means there will not be too many changes to the BoJ’s forecast for modest GDP increases when it publishes its latest Outlook Report on Friday.
BoJ outlook report April 2026 forecasts
What about inflation?
Excluding fresh food, energy and institutional factors, Japanese CPI has dropped from a peak of 3.6% YoY last summer to a low of 2.1% in May. In addition to previous government measures to lower the cost of living, such as a consumption tax cut and lowering the cost of education, July to September this year will see the government providing subsidies for electricity and gas bills to offset the energy shock.
Again, no major changes are expected in the BoJ’s forecasts for inflation over the coming years, which continue to point to stable inflation near 2.0% over the longer term.
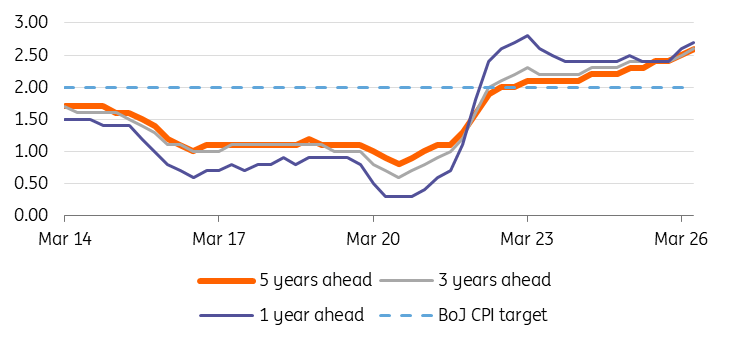
That said, the BoJ has noted the risk of business-to-business inflation spreading through the economy and should have taken notice of inflation expectations sourced through the Tankan survey. Here, All Enterprises see inflation at 2.6% YoY five years ahead – firmly above the BoJ’s 2% target.
The BoJ will also be well aware of import prices running at 30% YoY in June (highest since 2022) and the yen at the weakest levels since the 1980s.
Tankan All enterprises inflation expectations July 26
The decision
Weakness in the yen after the (not unsurprising) ineffectiveness of the BoJ’s FX intervention in April/May this year has led some to speculate that the BoJ will accelerate its tightening cycle. Many of the BoJ board believe that Japan’s neutral policy rate is closer to 2.00% and it’s just a question of how quickly it is taken there.
Recent source reports suggest some BoJ members could favour the next hike as early as September or October as opposed to the gradual six-monthly schedule of the next hike coming in December.
Arguments for the faster hike also seem to be coming from the bond market, where the two-to-10 year JGB curve has steepened beyond the highs seen in 2010, which some are attributing to the BoJ being behind the curve.
However, the BoJ will find some solace from Break-Even-Inflation (BEI) rates, where Japanese 10-year rates have recently pulled back to 2.00% and point to investors taking the view that the BoJ has inflation under control.
As to the decision, anything other than an unchanged 1.00% policy rate would be a surprise. There could be some interest in the voting patterns. Governor Kazuo Ueda is expected to return after a recent illness, bringing the Policy Board back to nine. The focus will be on whether any of the board members will vote for back-to-back hikes. Kajime Nakata did so in January this year and could be a candidate to do so again this week. A bigger surprise would be whether the other two hawks, Junko Nakagawa and Naoki Tamura, join him.
Governor Ueda’s press conference will be of interest, but unless he hints about the need for a faster tightening cycle, markets look unlikely to react. Remember that representatives of the Cabinet Office attend these meetings and BoJ minutes reflect their views that Japan’s ‘transition to a growth-oriented economy is crucial’. Understandably, investors see the BoJ exposed to more government oversight on monetary policy than many in their G10 central banking peer group.
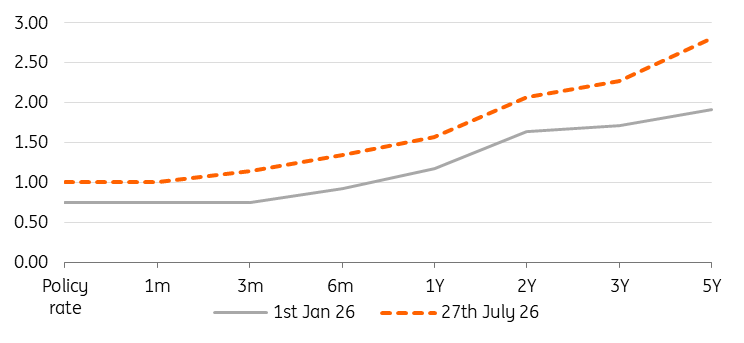
Latest expectations for the BoJ policy path
Market implications
Energy prices and the Fed reaction function look to be the bigger driver of USD/JPY over the coming months, rather than a potentially more hawkish BoJ. And Wednesday’s FOMC meeting will have a big say here. Barring a surprisingly dovish Fed meeting, or a sudden drop in Brent back to $70/bl, we expect to stay bid near 163/164 into the BoJ meeting.
There is an outside risk of USD/JPY making a run at 165 if Governor Ueda is insufficiently hawkish in his press conference, but the risk of FX intervention remains. Here the BoJ spent $70bn in late April/early May and has remaining FX reserves of $1.09 trillion. Without doubt, Japanese authorities would prefer to sell USD/JPY into a falling market for greater effectiveness, but likely would be called into action should the 165 area be challenged.
As to the longer-term outlook for USD/JPY, we have a year-end forecast at 158 on a baseline view that the Fed does not hike.
There is also speculation that the Japanese government is looking at measures to support the yen by encouraging Japanese investors to keep more money at home.
Changes in portfolio allocation policy for Japan’s GPIF pension fund look hard to make. But any concrete adjustments to products like Japan’s New ISA (NISA) to allow investors to hold more domestic assets, like JGBs, would be a big deal. This comes after 2024 NISA reforms opened up global equity markets to retail Japan and weighed on the yen.
JBGs view any hold as no more than a brief pause, with long rates at 4%
The 5yr Japanese Government Bond (JGB) yield prints at 2%, a level we view as the medium-term target for the Bank of Japan policy rate. The 2yr yield prints at 1.5%, which in fact is quite tame, at just 50bp over the policy rate. The forwards pitch the policy rate at 2% two years forward. What we glean from this is an upside expectation for the BoJ policy rate, but at a relatively slow rate. We link this to angst showing up in both the JPY and longer tenor JGB yields.
The 10yr yield at 2.7% discounts a material expectation for an eventual normalisation in the BoJ rate. The 5/10yr segment, at 70bp, is in turn relatively steep. There is a degree of pain being felt by long tenor yields, linked back to quite a slow rate hike build from the BoJ. We can see the same in the 30yr and 40yr yields which are pitched in the 4% area. Remarkably, that's where the US 30yr yield was just two years ago.
So the carry spread (policy rate vs 2yr yield) is relatively tame, while the full curve shape is quite steep. We identify a tension between these two outcomes, as it points to a low expectation of significant hikes in the coming quarters (carry spread). At the same time, the steepness of the curve points to the BoJ being behind the curve, and not protecting the back end enough.
Should the BoJ indeed hold and stall, then expect longer tenor yields to remain elevated with upside pressures. Finally, we deploy Tona in our rates pressure model for the BoJ, where we identify ongoing pressures for hikes.
Author

ING Global Economics Team
ING Economic and Financial Analysis
From Trump to trade, FX to Brexit, ING’s global economists have it covered. Go to ING.com/THINK to stay a step ahead.