US Treasury yields climb as Oil spike revives CPI jitters
- US 10-year yield jumps as WTI surge revives inflation fears.
- Weak NFP trims Fed hike bets before key CPI release.
- Iran talks setback boosts Oil and supports Dollar recovery.
US Treasury yields rose on Monday as traders braced for the release of US inflation figures this week, following a worse-than-expected Nonfarm Payrolls report last Friday. Headlines that read “Iran rules out talks with Trump, says will wait until his term ends in 2029,” poured cold water on negotiations for a swift reopening of the Strait of Hormuz.
US yields rise as Hormuz deal hopes fade, Oil surges and traders brace for inflation data
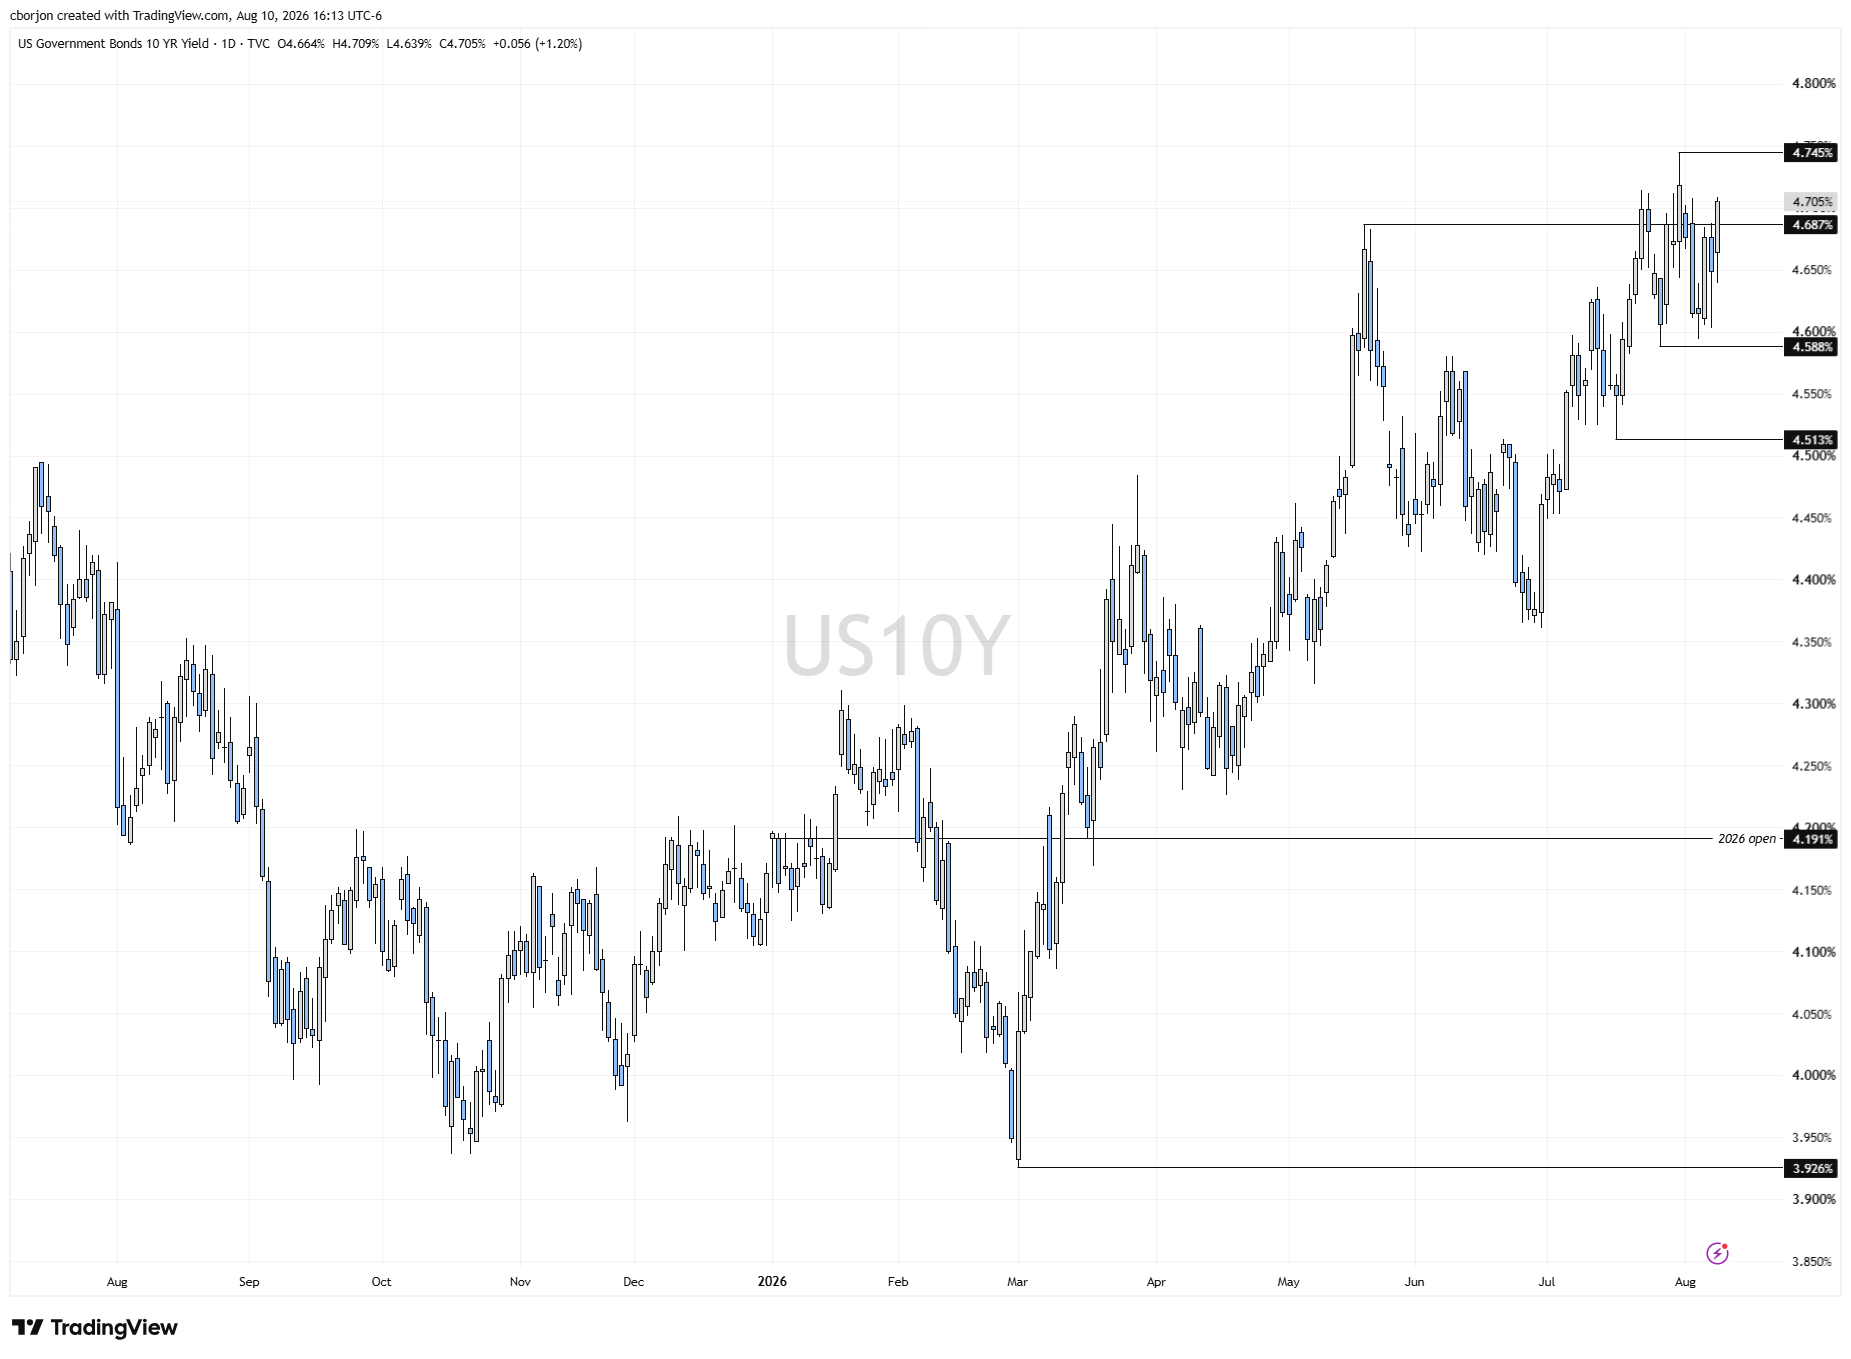
High energy prices sent US yields higher across the curve. The US 10-year benchmark note increases nearly six basis points to 4.705%, as West Texas Intermediate (WTI), the US crude benchmark, soars over 6.70% to $82.29.
July’s Consumer Price Index (CPI) is expected to decline slightly from 3.5% to 3.4% YoY. The core CPI, which excludes volatile items, is also projected to decrease from 2.6% to 2.5% YoY. The following day, on August 13, the Producer Price Index is similarly expected to ease.
The last US jobs report revealed some cracks, with the economy slashing 23K jobs, while the numbers for May and June were revised downward by 100K. This prompted investors to trim their hawkish bets on the Federal Reserve and now expect the US central bank to keep rates steady at 3.50%-3.75% towards the end of the year.
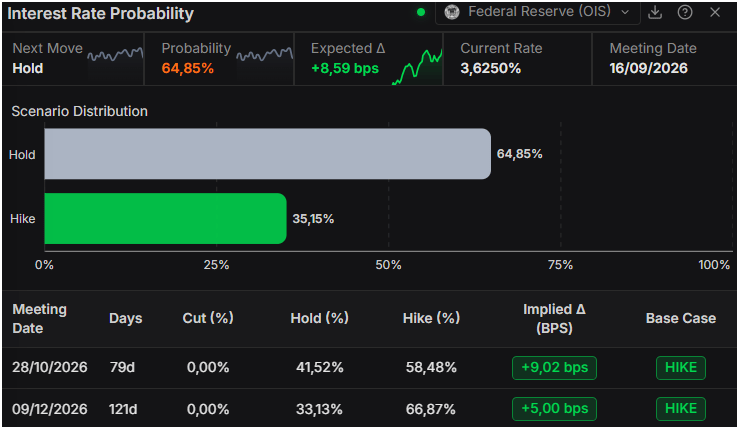
Prime Terminal data revealed that the chances of the Fed keeping rates unchanged at the September meeting stand at 65%, while the chances of a 26-basis-point rate hike stand at 35%.
The US Dollar Index (DXY), which tracks the performance of the buck’s value against six currencies, is up 0.20% at 99.81.
Alongside the release of US inflation data, traders are eyeing Initial Jobless Claims for the week ending August 8 and the University of Michigan (UoM) Consumer Sentiment.
US 10-year Treasury yield chart
Interest rates FAQs
Interest rates are charged by financial institutions on loans to borrowers and are paid as interest to savers and depositors. They are influenced by base lending rates, which are set by central banks in response to changes in the economy. Central banks normally have a mandate to ensure price stability, which in most cases means targeting a core inflation rate of around 2%. If inflation falls below target the central bank may cut base lending rates, with a view to stimulating lending and boosting the economy. If inflation rises substantially above 2% it normally results in the central bank raising base lending rates in an attempt to lower inflation.
Higher interest rates generally help strengthen a country’s currency as they make it a more attractive place for global investors to park their money.
Higher interest rates overall weigh on the price of Gold because they increase the opportunity cost of holding Gold instead of investing in an interest-bearing asset or placing cash in the bank. If interest rates are high that usually pushes up the price of the US Dollar (USD), and since Gold is priced in Dollars, this has the effect of lowering the price of Gold.
The Fed funds rate is the overnight rate at which US banks lend to each other. It is the oft-quoted headline rate set by the Federal Reserve at its FOMC meetings. It is set as a range, for example 4.75%-5.00%, though the upper limit (in that case 5.00%) is the quoted figure. Market expectations for future Fed funds rate are tracked by the CME FedWatch tool, which shapes how many financial markets behave in anticipation of future Federal Reserve monetary policy decisions.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.