UoM Consumer Sentiment Index expected to decline in October amid high Oil prices
- The Preliminary Michigan Consumer Sentiment Index is forecast to decline for a third consecutive month in October.
- Crude Oil prices picked up ahead of the release amid concerns of renewed Middle East tensions.
- The US Dollar Index maintains upward pressure near its 2026 peak in the 102.50 region ahead of the release.
The University of Michigan (UoM) will release the preliminary estimate of the United States (US) October Consumer Sentiment Index on Friday. The UoM report, which analyses US consumers’ feelings about their personal finances, business conditions, and purchasing plans, is expected to decline for a third consecutive month, as market analysts anticipate a reading of 47.6 following the 48.1 printed in September. The September reading was the second-lowest historical level, barely above the historic low of 44.8 posted in May.
Alongside headline Consumer Sentiment, the UoM releases 1-year and 5-year Consumer Inflation Expectations, currently at 4.6% and 3.4%, respectively. The Federal Reserve (Fed) vouches for inflation to remain around 2%, hence, the recent decision to tighten monetary policy by hiking the benchmark interest rate by 25 basis points (bps). Indeed, UoM’s report is nothing more than a reflection of consumers’ expectations of price pressures and is far from an official figure. Still, the numbers reflect American reality as the Middle East war pushes energy prices higher.
What to expect from October’s UoM Consumer Sentiment Index report?
The Middle East war has been the market’s main driver. What started as a conflict between Iran and Israel ended up being a regional crisis that includes the US. The blockage of the Strait of Hormuz resulted in Oil prices soaring to multi-year highs and resulting in outrageous energy-related inflation. The conflict, which started in February, has seen different stages, with hopes for a quick resolution fading as time goes by.
Investors remain distrustful despite crude Oil flows in the Persian Gulf returning to near pre-war levels. Oil prices are back up, with West Texas Intermediate (WTI) futures up roughly 5% on Thursday after US President Donald Trump said he no longer wants a deal with Iran, while discussing resuming large-scale military operations on Iran in the upcoming weeks.
His comments do little to build confidence among Americans seeing persistently elevated energy and food prices. Still, it’s worth mentioning that price pressures moved off their yearly peaks. The latest Personal Consumption Expenditures (PCE) Price Index rose a seasonally adjusted 3.4% in the year to August, down from the 4% posted earlier in the year. Core PCE during the same period rose 3%, still above the Fed’s goal but again easing from its 2026 peak.
The recent spike in Oil prices is likely to maintain inflation expectations elevated and hence, confidence subdued.
When will the UoM Consumer Sentiment Index be released, and how could it affect the US Dollar?
The University of Michigan will release the Consumer Sentiment Index and Consumer Inflation Expectations on Friday at 14:00 GMT. As previously noted, market players anticipate sentiment will continue to deteriorate in October. Ahead of the announcement, the US Dollar Index (DXY) holds well above the 102 mark, not far below this year’s peak achieved in October at 102.53.
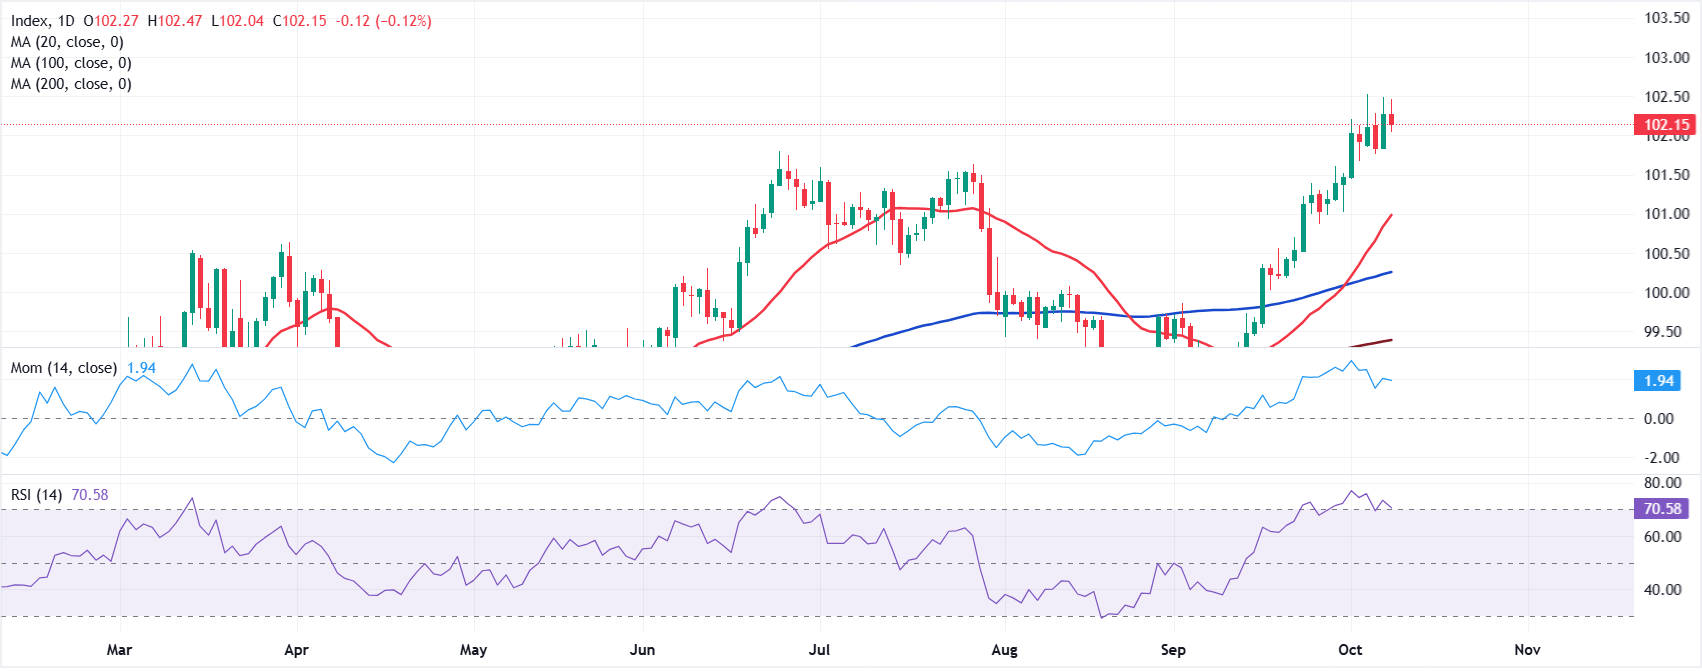
Valeria Bednarik, Chief Analyst at FXStreet, notes: “The US Dollar (USD) benefits from both risk aversion amid fears of an escalation of the Middle East war and speculation that the Fed will have to hike interest rates again before the year ends. From a technical perspective, and according to the daily chart, the DXY is overbought but still bullish. The Relative Strength Index (RSI) indicator consolidates at extremes, yet off its recent peak. Furthermore, the index develops above all its moving averages, with the shorter 20-day Simple Moving Average (SMA) accelerating north after crossing above the longer 100-day and 200-day SMAs, usually a sign of building directional momentum.”
Bednarik adds: “The mentioned peak in the 102.50 region provides immediate resistance, with gains beyond it exposing the 103.00 threshold ahead of the 103.45 area. The weekly low at 101.76 is the first support level to watch, with additional declines exposing the 101.30 price zone. The closer the index approaches 101.00, the higher the chances buyers reappear.”
Economic Indicator
UoM 1-year Consumer Inflation Expectations
The University of Michigan's Inflation Expectations gauge captures how much consumers anticipate prices will change over the coming 12 months. It comes out in two rounds—a preliminary release that tends to pack a bigger punch, followed by a revised update two weeks later.
Read more.Next release: Fri Oct 09, 2026 14:00 (Prel)
Frequency: Monthly
Consensus: -
Previous: 4.6%
Source: University of Michigan
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.