The Euro edges lower as Frankfurt's hike takes effect the day Washington votes
- EUR/USD edges lower to close near 1.1540, down 0.1%, its fourth loss in four sessions
- The ECB's move to 2.50% takes effect on Wednesday, the day the Fed votes at 18:00 GMT
- Eurozone ZEW sentiment fell to 25.8 against a 39.9 forecast, with banking the one sector up
EUR/USD closed Tuesday near 1.1540, down 0.1%. It fell on the day the European Central Bank (ECB) raised its deposit rate to 2.50% and in each of the three sessions since. That increase takes legal effect on Wednesday, the same day the Fed is expected to raise its own rate for the first time since July 2023. Wednesday's Asian and London hours are the last before it does, and the Euro arrives with its own central bank's second hike of the year already in hand. It has not helped.
Two hikes from Frankfurt, none yet from Washington, and a lower Euro
A currency pair prices the gap between what two central banks are expected to pay. The ECB has raised its deposit rate twice since June, to 2.50%, and the Fed's range still tops out at 3.75%. Wednesday takes that ceiling to 4.00%, which widens the gap to a point and a half on the day the ECB's quarter-point becomes official. Futures then have the Fed at 4.25% or higher by March and, more likely than not, at 4.50% or higher by June, while investors see the ECB's next move in December at the earliest.
Both banks are raising rates for the same reason, a barrel of Crude Oil above $100.00 after Saudi Arabia shut its pipeline around the Strait of Hormuz, and the two economies sit on opposite sides of it. The United States is a net exporter of petroleum and the Euro area imports nearly all of its Crude Oil. The same price that lets the Fed raise rates into a growing economy makes the ECB raise them into an import bill. The Dollar Index sits just under 100.
The ECB President called last Thursday's decision an easy one, the vote was unanimous, and the Council's own forecasts have inflation at 3.0% this year and 2.5% next, with growth upgraded to 0.9% this year and 1.4% next. EUR/USD traded near 1.1600 on June 11, the day the ECB's first hike landed. It closed at 1.1538 on Tuesday, and the Fed has yet to raise anything.
Higher rates lifted one sector in the survey, and it was the banks
The Centre for European Economic Research (ZEW) survey of Eurozone investor sentiment fell to 25.8 in September against a forecast of 39.9 and 31.4 in August, and the German reading came in at 34.7 against 42.5. Current conditions improved, to -13.9 from -21.5 for the Eurozone and to -47.1 from -61.1 for Germany, so the economy looks better than it did and the outlook worse. The survey's authors blame energy prices tied to the war and what they call hybrid attacks. Germany's 10-year yield has traded at its highest since 2011 since the ECB decision, which is the bond market pricing the hikes that the survey says the economy is not ready for.
The one sector the survey found improving was banking, up 8.2 points to 52.9, which is the sector that collects the rate everyone else pays. Cars sat at -22.6 and steel at -16.7. A survey like that is the constraint on the ECB delivering the December hike investors expect, which puts the Euro's rate path, not the Dollar's, at risk of being trimmed.
Frankfurt gets the hour before Washington
Eurozone industrial production for July lands at 09:00 GMT on Wednesday, forecast down 0.2% after a flat June, and two Governing Council members speak at 12:15 GMT and 13:00 GMT. The ECB President speaks at 17:00 GMT, one hour before the Fed decides. The Council said on Thursday that it will not commit to a path in advance, and its President said it did not discuss what comes next. It has had six days.
The Fed's decision comes at 18:00 GMT, with the quarter-point priced at 92.5%, a second hike by December and a third by March. The press conference follows at 18:30 GMT, after American retail sales at 12:30 GMT, forecast up 0.8%. On Thursday the ECB's chief economist speaks at 07:00 GMT, final August inflation lands at 09:00 GMT with the core rate forecast steady at 2.4%, and the Bank of England decides at 11:00 GMT. Eurozone finance ministers meet on Friday.
Levels and bias
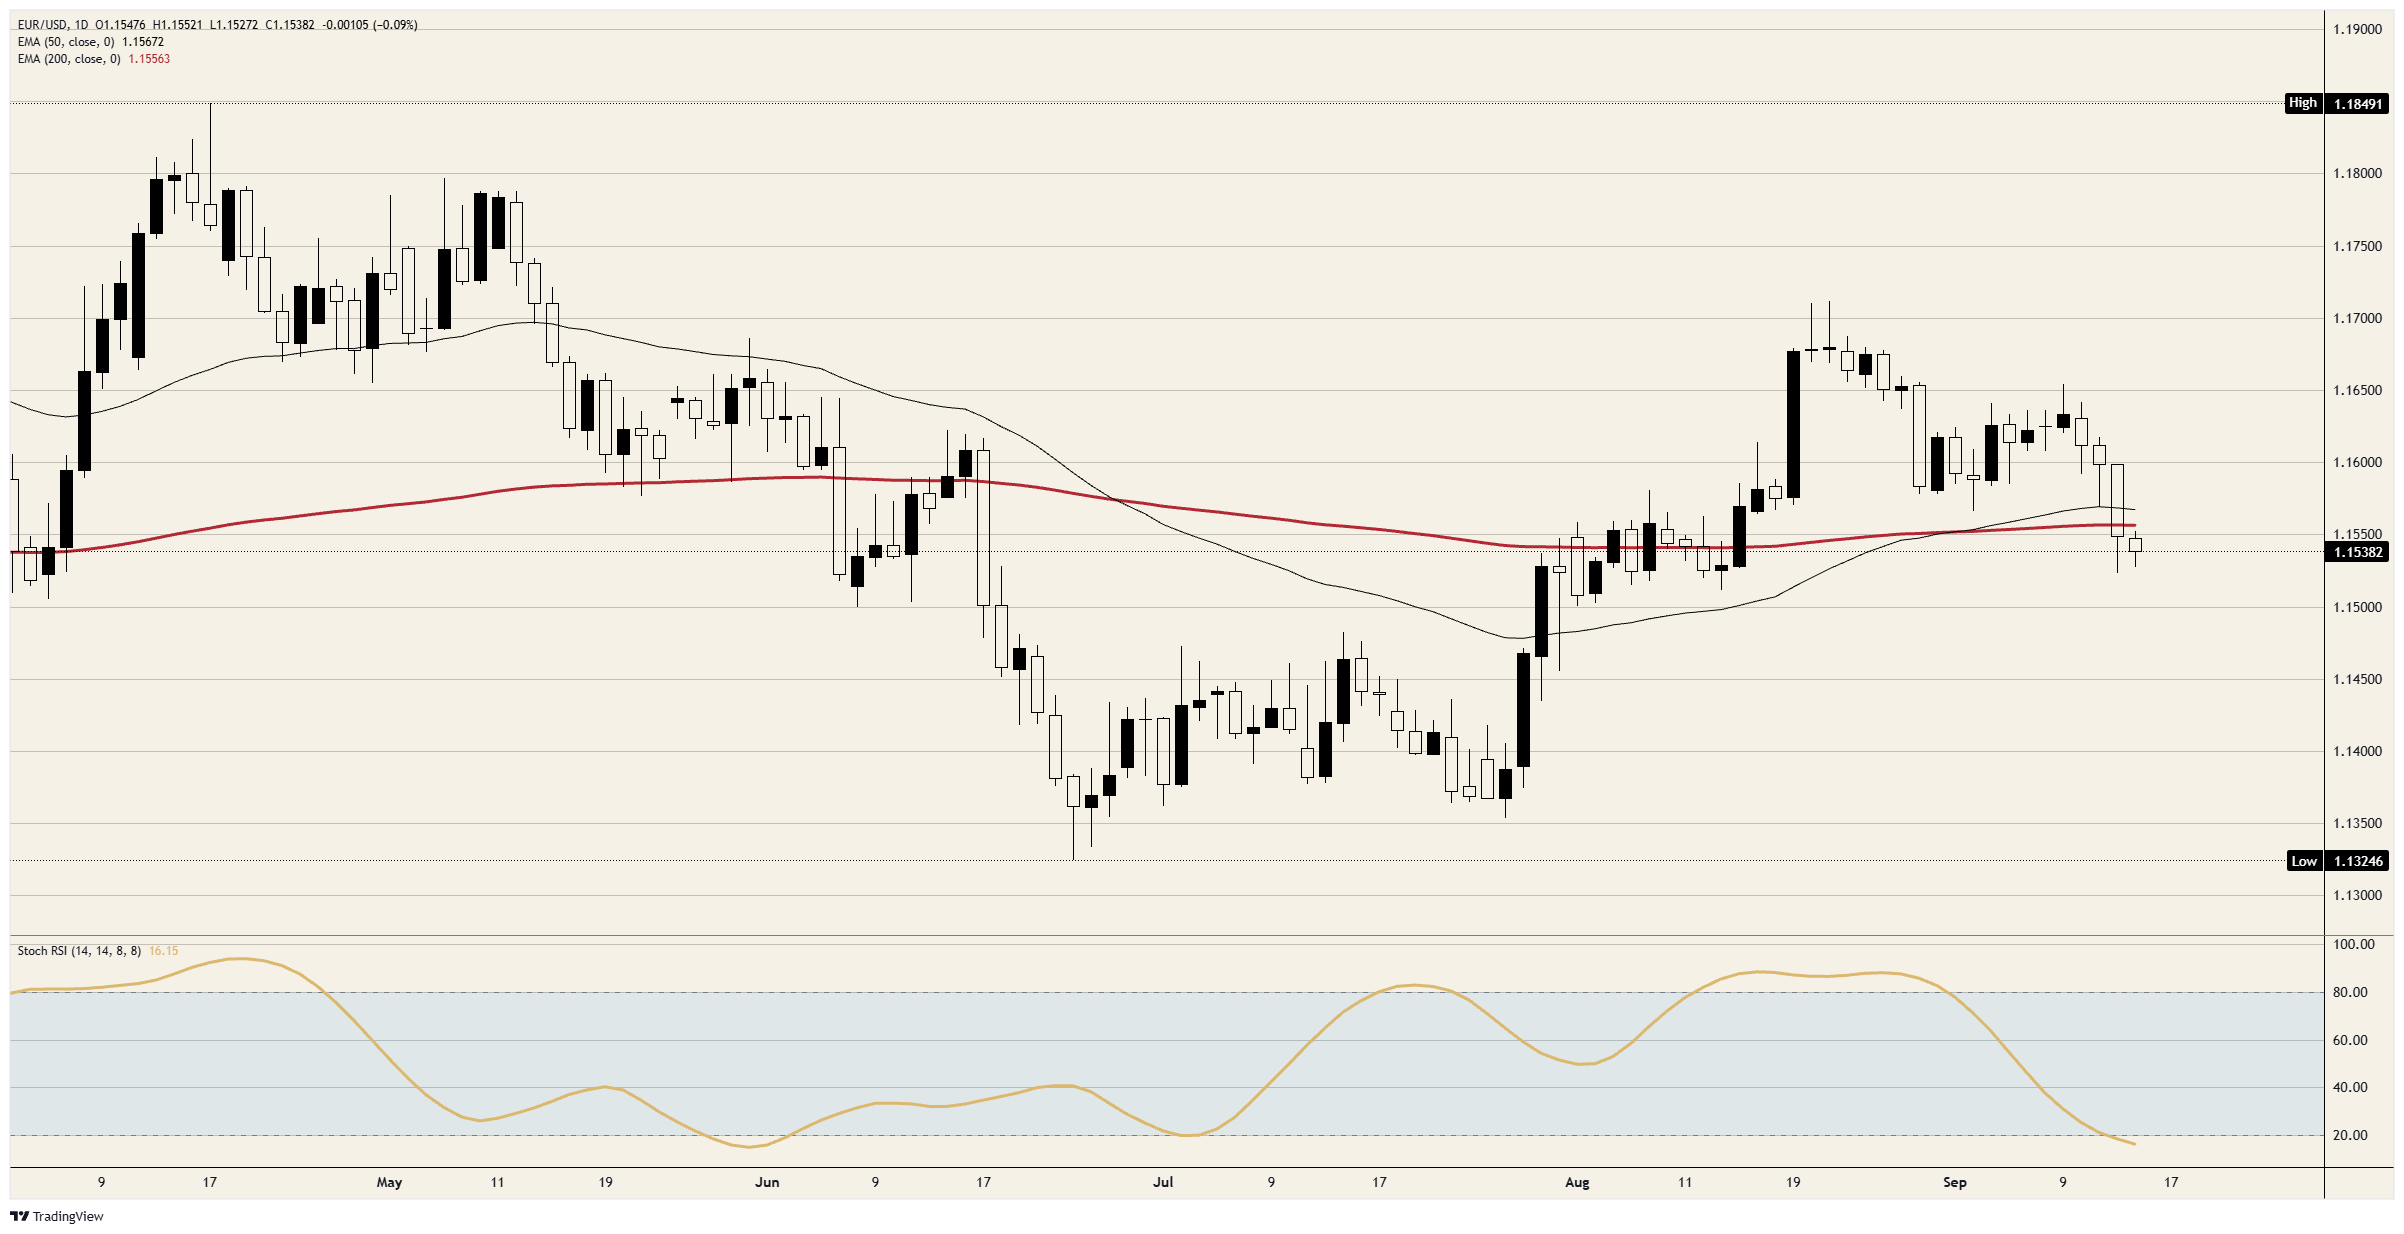
Resistance: Monday's high just under 1.1600 is the first hurdle. The 50-day and 200-day Exponential Moving Averages (EMA) sit just above 1.1550, within 11 pips of each other, and Tuesday's close beneath both was the first since the mid-August breakout. The September highs just under 1.1650 sit behind them.
Support: Tuesday's low sits 27 pips above 1.1500, and 1.1500 itself is the mid-August base, the last place the pair found buyers before the August rally. The late-July low near 1.1450 is the next level beneath it.
Bias: Bearish while the moving averages just above 1.1550 cap, with 1.1500 the first objective and 1.1450 the second. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, reads near 16, beneath the 20 line where the late-July selling stopped. A daily close back above 1.1600 voids the case.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















