Mexican Peso appreciates sharply amidst a soft US Dollar on Thursday
- Mexican Peso gains as February's lower-than-expected inflation fuels speculation of an upcoming Banxico rate cut.
- Mixed signals from Mexico's CPI data leave markets anticipating key Banxico decision on March 21.
- Cooling US job market and widening trade deficit add complexity to Fed's policy outlook as Powell reiterates cautious stance.

The Mexican Peso posted minuscule gains against the US Dollar after Mexico’s National Statistics Agency (INEGI) revealed that inflation cooled in February. Therefore, speculation for the Bank of Mexico's (Banxico) first rate cut looms large. This should weigh on the emerging market currency and underpin the USD/MXN pair. Hence, the exotic pair exchanges hands at 16.88, down 0.13%.
Mexico’s Consumer Price Index (CPI) for February was lower than expected on monthly and annual figures. Nevertheless, underlying CPI came as expected in MoM data, a tick higher compared to January’s reading, but inflation dipped in the annual readings. It remains to be seen whether the conditions are met for Banxico’s first rate cut at the March 21 meeting, and there’s a tranche of data to be released ahead of that date.
In the United States, the job market is cooling. Americans filing for unemployment claims rose above estimates, aligned with the previous week’s data, suggesting the labor market is getting more balanced. At the same time, the US trade deficit widened in January as imports grew more than in December.
At the time of this writing, US Fed Chair Jerome Powell is testifying before the US Senate Banking Committee on Capitol Hill. He is echoing some of Wednesday’s comments, saying that if the economy evolves as expected, the Fed will carefully remove its restrictive policy stance.
Daily digest market movers: Mexican Peso boosted by broad US Dollar weakness
- Mexico’s inflation was 4.40% YoY, below estimates of 4.42% and January’s 4.88%. On a monthly basis, CPI was down from 0.11% to 0.09%.
- Excluding volatile items, the so-called Core CPI rose by 4.64% above forecasts but lower than the previous reading of 4.76%, while monthly figures were aligned with estimates of 0.49%, up from 0.40%.
- Mexican data released previously:
- On Wednesday, Mexico’s consumer confidence index was 47.0 in February when adjusted for seasonal factors. The unadjusted index was 47.1.
- On Monday, Mexico’s economic docket revealed that Gross Fixed Investment in December remained flat MoM. Nevertheless, on an annual basis, it dipped from 19.2% to 13.4%.
- A Reuters poll sees the Mexican Peso depreciating 7% to 18.24 in 12 months from 16.96 on Monday, according to the median of 20 FX strategists polled between March 1-4. The forecast ranged from 15.50 to 19.00.
- A Reuters poll shows 15 analysts estimate that inflation will slow down in February, corroborating bets that the Bank of Mexico (Banxico) could cut rates as soon as the March 21 meeting.
- Mexico’s General Election campaign started on March 1. Polls suggest the ruling party’s nominee, Claudia Sheinbaum, maintains her lead over Xochitl Galvez. Parametria’s poll shows Sheinbaum's support at 49%, while Galvez, the opposition candidate, stands at 29%.
- Banxico’s private analytics poll projections for February were revealed. They expect inflation at 4.10%, core CPI at 4.06%, and the economy to grow 2.40%, unchanged from January. Regarding monetary policy, they see Banxico lowering rates to 9.50% and the USD/MXN exchange rate at 18.31, down from 18.50.
- During Banxico’s quarterly report, policymakers acknowledged the progress on inflation and urged caution against premature interest rate cuts. Governor Victoria Rodriguez Ceja said adjustments would be gradual, while Deputy Governors Galia Borja and Jonathan Heath called for prudence. The latter specifically warned against the risks of an early rate cut.
- Banxico updated its economic growth projections for 2024 from 3.0% to 2.8% YoY and maintained 1.5% for 2025. The slowdown is blamed on higher interest rates at 11.25%, which sparked a shift in three of the five governors of the Mexican Central Bank, who are eyeing the first rate cut at the March 21 meeting.
- Economic trade issues between Mexico and the US could depreciate the Mexican currency if the Mexican government fails to resolve its steel and aluminum dispute with the United States. US Trade Representative Katherine Tai warned the US could reimpose tariffs on the commodities.
- US economic data hurt the prospects for a higher USD/MXN, with buyers failing to keep the exchange rate above 17.00.
- The political race is almost defined in the United States after Super Tuesday. Former President Donald Trump leads the Republicans with 995 delegates, shy of the 1,215 needed. On the Democratic side, US President Joe Biden leads with 1,497 delegates, short of the 1,968 needed.
- The Initial Jobless Claims for the week ending March 2 were 217K, surpassing estimates and the previous reading of 215 K.
- The US Balance of Trade was $-67.4 billion, exceeding estimates of $-63.5 billion and higher than December’s $-64.2 billion.
- As Fed Chair Jerome Powell testifies, the CME FedWatch Tool shows traders increased their bets for a 25-basis-point rate cut in June from 52.7% a week ago to 71.9%.
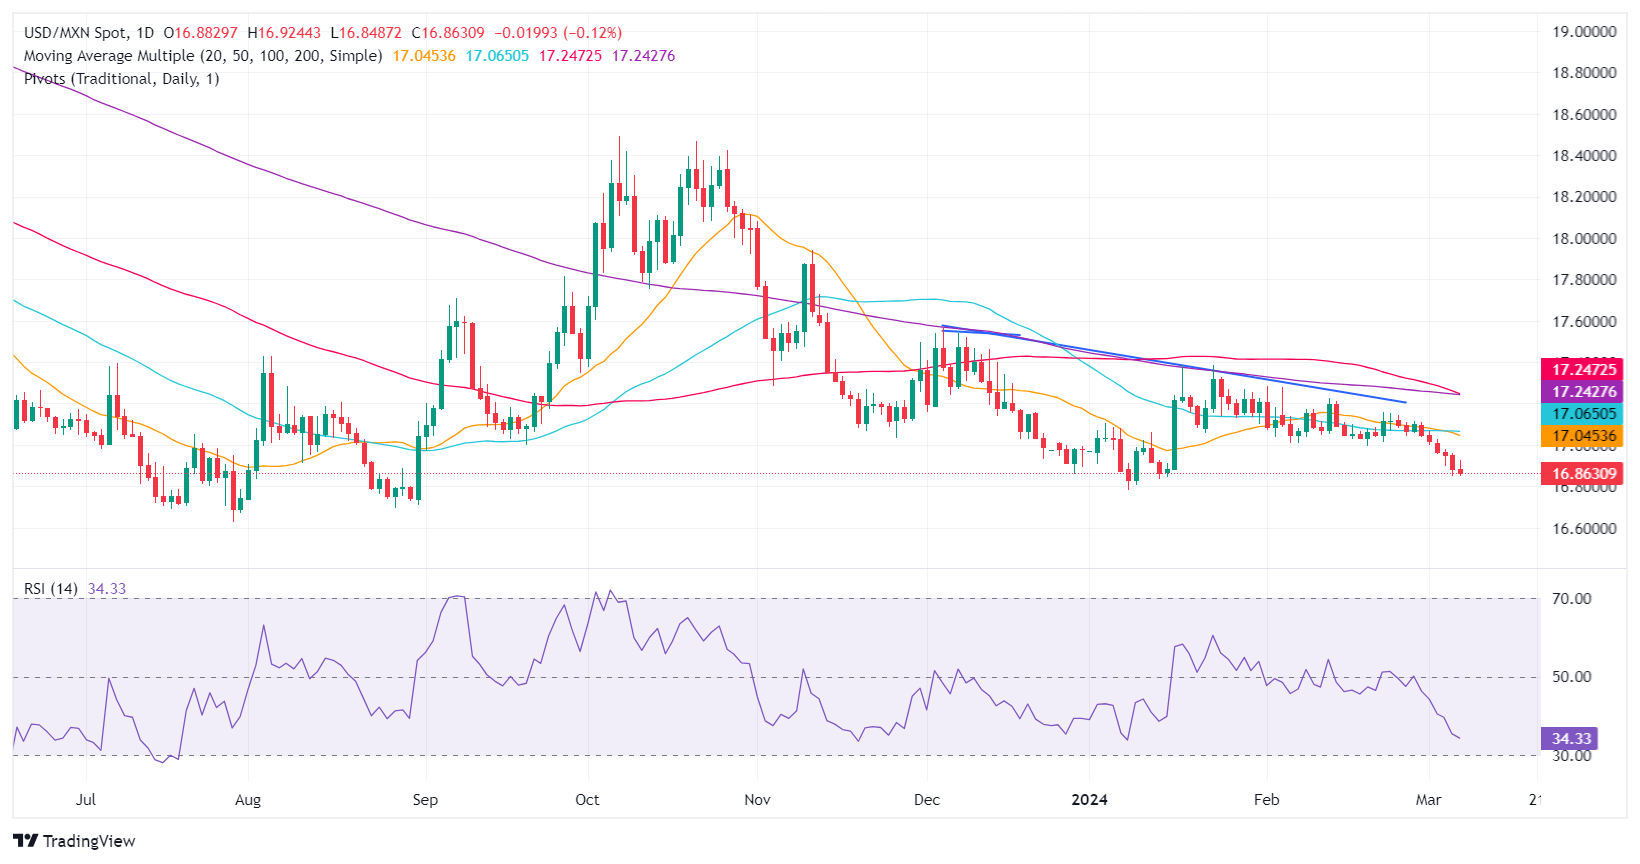
Technical analysis: Mexican Peso advance continues as USD/MXN holds firm below 16.90
The USD/MXN downtrend remains intact, with sellers keeping the exchange rate below 16.90. If they push the pair below the year-to-date (YTD) low of 16.78, look for a deeper correction past last year’s 16.62 low. Initial targets are October 2015’s low of 16.32 and the 16.00 mark.
On the other hand, if buyers reclaim the 17.00 figure, that could open the door to testing the 50-day Simple Moving Average (SMA) at 17.05, followed by the 200-day SMA at 17.24 and the 100-SMA at 17.38.
USD/MXN Price Action – Daily Chart
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















