Indian Rupee wipes out weekly gains as oil prices continue to rise
- The Indian Rupee weakens further against the US Dollar amid rising oil prices.
- Middle East tensions continue to prompt energy supply risks.
- India’s flash HSBC Global PMI data remains strong in October.
The Indian Rupee extends Thursday’s weakness against the US Dollar (USD) in Friday, wiping out almost entire gains made earlier this week. The USD/INR pair jumps to near 94.92 as surging oil prices due to Middle East tensions have weighed heavily on the Indian currency.
In the opening trade, the MCX Crude Oil contract expiring on November 19 is up 0.65% to near Rs. 9,550. The oil price is close to its recent highs of Rs. 9,661 posted earlier this week.
Higher oil prices bode poorly for currencies from economies, such as India, which rely heavily on its imports to meet its energy demands.
Middle East tensions flare after Saudi drone attack
Analysts at Commerzbank report that Middle East tensions “intensified after a drone attack on Saudi Arabia's Shaybah oil field killed two people and injured two others,” but note that the impact on crude was ultimately contained. They highlight that “oil prices briefly jumped on reports suggesting a wider withdrawal of US diplomatic personnel from the Gulf,” before the move faded as “Washington clarified that the order was limited to Saudi Arabia,” prompting the market to pare earlier gains.
The withdrawal of US non-emergency personnel from Gulf has prompted fears that military aggression in Iran could escalate further.
India’s private sector output remain robust in October
According to the preliminary HSBC Global Purchasing Managers’ Index (PMI) data for October, the overall business activity remained stronger. The Composite PMI arrives at 56.7, higher than the final reading of 55.9 in September. Strong service sector activity led to a significant increase in the Composite PMI.
“Private-sector manufacturing activity continued to expand, with growth of output and new orders broadly unchanged at last month’s levels. However, the steady pace of new order growth masks the fastest increase in new export orders since June 2025. Manufacturers responded by increasing their stocks of purchases and finished goods. Input cost inflation eased, while the rise in selling prices softened to its weakest in almost four years,” Pranjul Bhandari, Chief India Economist at HSBC, said.
US PMI data awaited
Investors await the preliminary US S&P Global PMI data for October, which will be published at 13:45 GMT. Both manufacturing and the service sector activities are expected to have expanded again, but at a moderate pace.
USD/INR Technical Analysis
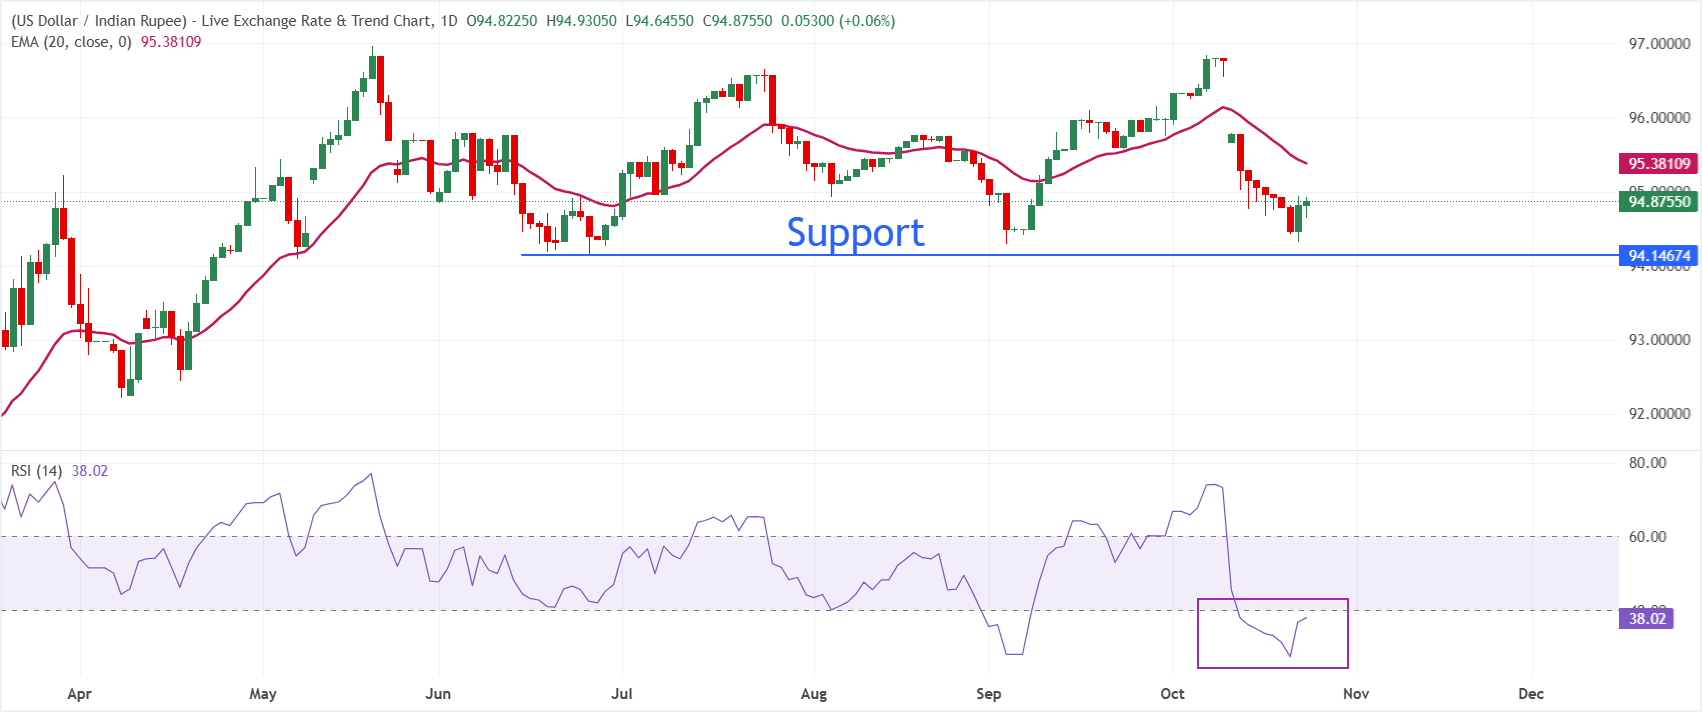
In the daily chart, USD/INR trades at 94.92, keeping a bearish near-term tone as it holds below the 20-day exponential moving average (EMA) at 95.38.
The pair has retreated sharply from the recent highs, and the Relative Strength Index (14) at 37.94 stays just above oversold territory, suggesting that while downside momentum is still present, selling pressure may be losing some intensity.
On the topside, immediate resistance is located at the 20-day EMA around 95.38, which caps recovery attempts and will need to be reclaimed to ease the current downside bias. Looking down, the June 25 low at 94.15 is the key support level.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.

















