Gold struggles below two-month high despite softer US PPI
- Gold stays under pressure after hitting a fresh two-month high.
- Fading Fed rate-hike expectations and falling US Treasury yields help cushion the downside in the non-yielding metal.
- XAU/USD struggles around the 100-day SMA, while bullish RSI and MACD readings suggest buyers still retain some control.
Gold (XAU/USD) trades under pressure on Thursday after hitting a fresh two-month high of $4,449 during Asian trading hours. The metal fails to capitalise on softer-than-expected US Producer Price Index (PPI) data, even as the US Dollar and Treasury yields edge lower. At the time of writing, the precious metal trades around $4,377, down 0.70% on the day.
The pullback appears to be driven mainly by profit-taking as market participants remain reluctant to chase prices higher amid an uncertain macroeconomic backdrop. The recent rally from near $4,000 has largely been fuelled by softer US economic data, including a broadly in-line Consumer Price Index (CPI) and weaker-than-expected Nonfarm Payrolls (NFP) reports for July. These releases have reduced the chances of an imminent interest-rate hike by the Federal Reserve (Fed).
Data released by the US Bureau of Labor Statistics on Thursday showed that the headline PPI was unchanged in July after falling by 0.1% in June, while the annual rate eased to 4.7% from 5.5%. Core PPI rose by 0.2% MoM, down from 0.4%, while the annual rate slowed to 4.2% from 4.7%.
According to the CME FedWatch Tool, markets now assign a 32% probability of a September rate hike, down from 55% a week ago. US Treasury yields are falling across the board, while the US Dollar Index (DXY) retreats below 100 after touching a two-week high earlier in the day.
The 2-year Treasury yield trades around 4.14%, its lowest level since July 17. Lower yields and a softer US Dollar (USD) are limiting Gold’s downside.
Analysts at MUFG/BTMU highlight that the CPI data “supports our view that Fed is likely to leave rates on hold in September,” although they caution that “it is unlikely that the US rate market will scale back rate hike expectations much further in the near-term given a hike still can’t be ruled out.” They also flag ongoing upside risks to the inflation outlook, warning that “the lack of progress to reopen the Strait of Hormuz and elevated energy prices continues to pose upside inflation risks in the near-term.”
At the same time, they argue that “the lack of clear forward guidance from Fed Chair Kevin Warsh makes it harder to assess how they are likely to set policy going forward,” leaving markets to navigate a still uncertain policy path despite the latest CPI print.
Against this backdrop, falling US Treasury yields and a softer US Dollar are likely to keep Gold supported, although uncertainty over the Fed’s policy path and heightened energy-driven inflation risks could cap the upside.
Technical analysis: Buyers struggle to clear the 100-day SMA
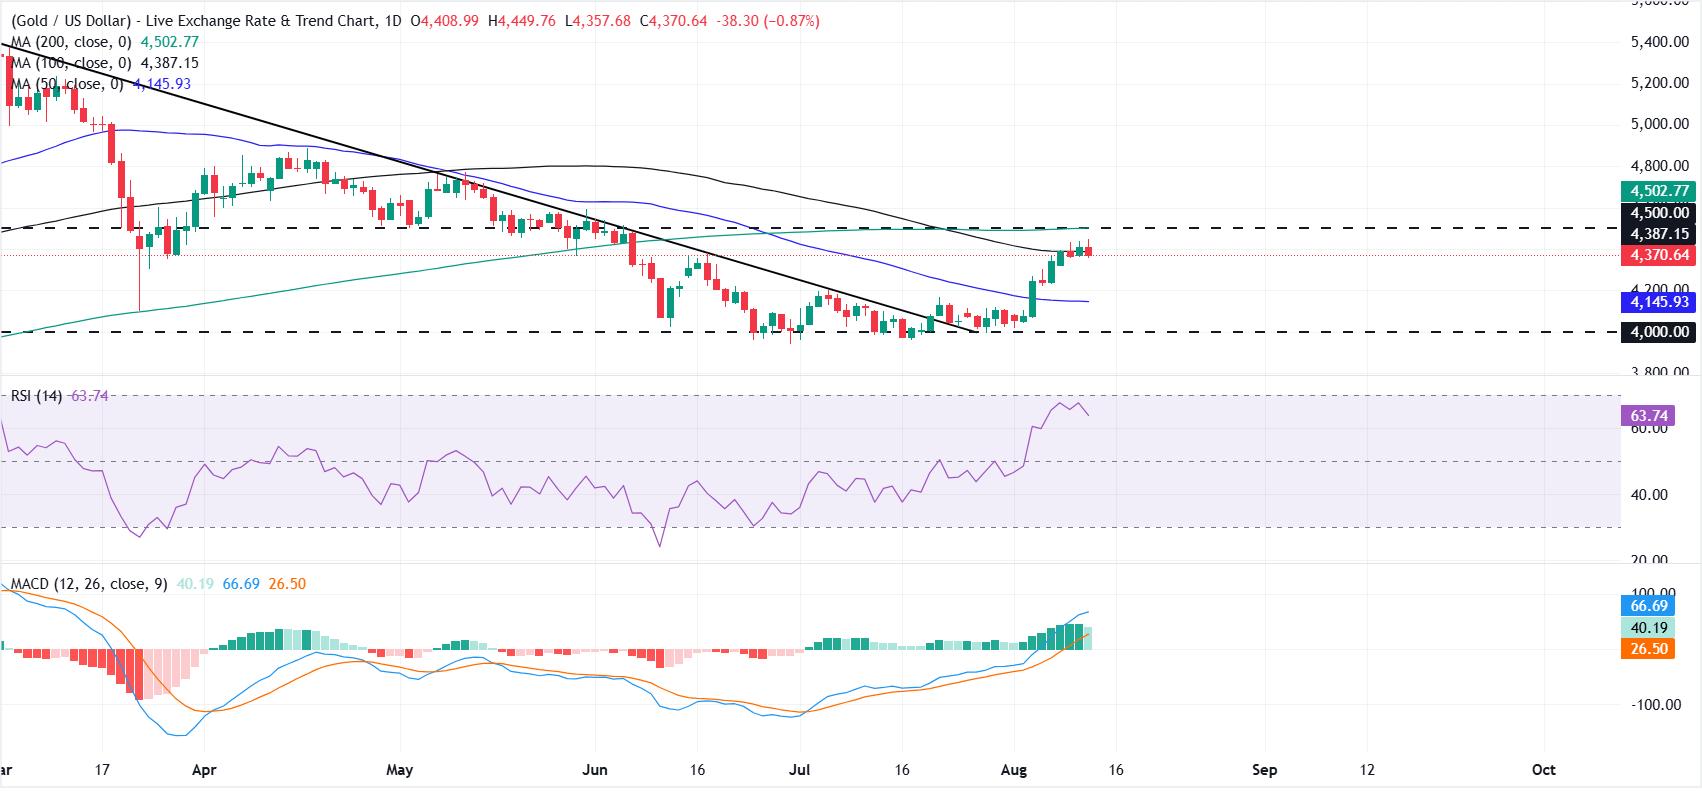
XAU/USD is fluctuating just around the 100-day Simple Moving Average (SMA) at $4,387 and well below the 200-day SMA at $4,502, while it holds comfortably above the 50-day SMA at $4,145, leaving the metal trapped between medium-term support and longer-term overhead resistance and hinting at a capped, neutral tone.
On the daily chart, the Relative Strength Index (14) at 65 sits in bullish territory, and the Moving Average Convergence Divergence (MACD) remains positive, which suggests underlying buying interest.
On the upside, a sustained move above the 100-day SMA at $4,387 could expose the $4,500 psychological mark, which closely aligns with the 200-day SMA at $4,502.
On the downside, the first meaningful support is located at the 50-day SMA at $4,145, followed by the psychological and structural floor at $4,000.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Vishal Chaturvedi
FXStreet
I am a macro-focused research analyst with over four years of experience covering forex and commodities market. I enjoy breaking down complex economic trends and turning them into clear, actionable insights that help traders stay ahead of the curve.
















