Flush or final flush?
Thursday‘s promising and developing short squeeze was nipped in the bud with the opening bell, and not just in the weaker tech. Both indices solidly undershot Thursday‘s lows – is that climactic volume supported by breadth metrics?
Given the AI build up worries starting with financing costs (insurance against default for CRWV, even for IGV such as ORCL?), revenue uncertainty (did OpenAI comment on last week‘s $20bn Axios-stated gap?) or raising fresh capital (Anthropic IPO could be $2T, or just $1.5T, and what about its cash generation ability?), there is no shortage of bearish catalyst. And this doesn‘t touch on capex growth continuation worries, better refined into multiples market is willing to pay for SMH, DRAM companies, and whether they would be as profitable as thought of earlier.
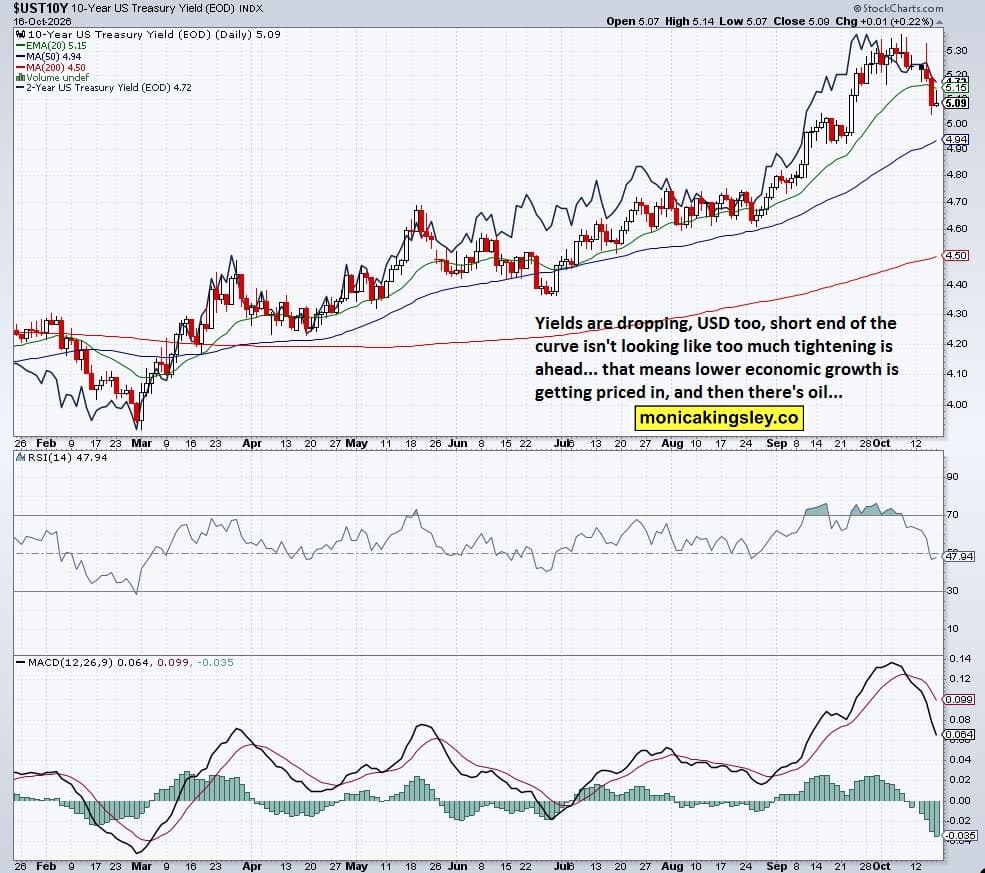
Or hot inflation, both CPI and PPI – yet bond yields are down, and Oct rate hike isn‘t taken for certain, but has only 15% odds now? So what are those retreating yields pricing in? Earnings aren‘t retreating, economy isn‘t going into recession – oil from the Gulf (Marianas turkey shoot, but tanker one) and diesel prices though are biting, XLI has come down, but XLU, XLY, XLRE are turning up?
Friday‘s passing on breadth improvement and budding short squeeze that targeted up to 775, with both XLI and XLY declining, muddies the S&P 500 picture – there‘s a tendency for VIX / VVIX spikes to be followed by retracements higher, but I‘m not sure whether even ES can pull off anything better than a tiny green doji (inside day near to the lows) Monday.
Author

Monica Kingsley
Monicakingsley
Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.
















