Canadian Dollar sees through its own record surplus
- USD/CAD extended its rebound off the spring lows even as Canada logged its widest trade surplus in four years.
- The record surplus was built on a Crude Oil price spike that has since reversed, stripping away the Loonie's export support.
- Friday's Canadian employment report is expected to show hiring slowing sharply from May's pace.

Canada delivered the kind of trade headline that should have put a firm bid under the Loonie, and the currency barely noticed. Statistics Canada reported the merchandise trade surplus widened to $4.2 billion in May, a four-year high built on record exports worth $77.1 billion, yet the Canadian Dollar drifted lower on the session as USD/CAD held its ground near the 1.4200 handle.
A surplus with an expiry date
The disconnect makes sense the moment you look at what actually built the surplus. May's export run was the fourth straight monthly gain, but it was a price story rather than a volume story, and the price doing the heavy lifting was Crude Oil, which has since surrendered most of the war premium that inflated those shipment values.
In real, price-adjusted terms, exports were essentially flat on the month, and one bank desk was blunt enough to flag the print as the likely high watermark for the surplus rather than the start of a trend.
Crude Oil unwinds the war premium
The energy tailwind that flattered those export values is not just softening but actively reversing. West Texas Intermediate (WTI), the North American benchmark, has slid back toward the $70 mark, near its lowest levels since February, as vessel traffic through the Strait of Hormuz keeps normalizing and the war premium continues to drain away.
Supply is now the dominant force, with major exporters signing off on another output increase for next month and Saudi Arabia cutting its flagship export grade to Asian buyers by the widest margin since the price wars of the last decade. Sporadic shipping incidents can still hand Crude Oil a day of gains, but the structural pull is lower, and a producer does not discount that aggressively into strong demand.
The one number worth respecting
Underneath the commodity noise sits a data point that actually looks forward. Imports of industrial machinery and equipment jumped 6.1% in May and are running almost 13% higher YoY, and that is the category that tends to lead business investment rather than trail it.
Firms do not order machinery when they expect to shrink, so the signal is that Canadian capital spending is edging higher even with trade policy still murky. It is a real positive, but a modest one, and it does nothing to replace the export income that a receding Crude Oil price is quietly pulling back.
The hawkish case springs a leak
The same Crude Oil slide that is deflating the trade surplus is quietly draining the case for higher Canadian rates. The Bank of Canada (BoC) has held its policy rate at 2.25% for five straight meetings, wedged between a soft domestic economy and the inflation risk that elevated energy prices kept alive, and money markets had even flirted with a small chance of a hike at the July 15 decision.
That case springs a leak once Crude Oil slips below the assumptions the Bank leaned on for its spring forecast, which is exactly where prices now sit. Tuesday's Ivey Purchasing Managers Index (PMI) undershooting expectations only sharpened the sense that domestic momentum is fading, not building.
Friday puts the labour market on the stand
The calendar hands the Loonie its next real test on Friday. Canada's June employment report lands at 12:30 GMT, with consensus looking for hiring to cool to roughly 10K jobs after May's near-88K surge and the unemployment rate expected to hold around 6.6%.
A soft print would harden the message the trade data already whispers, that domestic demand cannot lean on an export boost that Crude Oil is busy taking away. The Federal Open Market Committee (FOMC) minutes on Wednesday give the US Dollar its own catalyst, but for USD/CAD direction this week, the jobs number is the one that counts.
Where the tape breaks
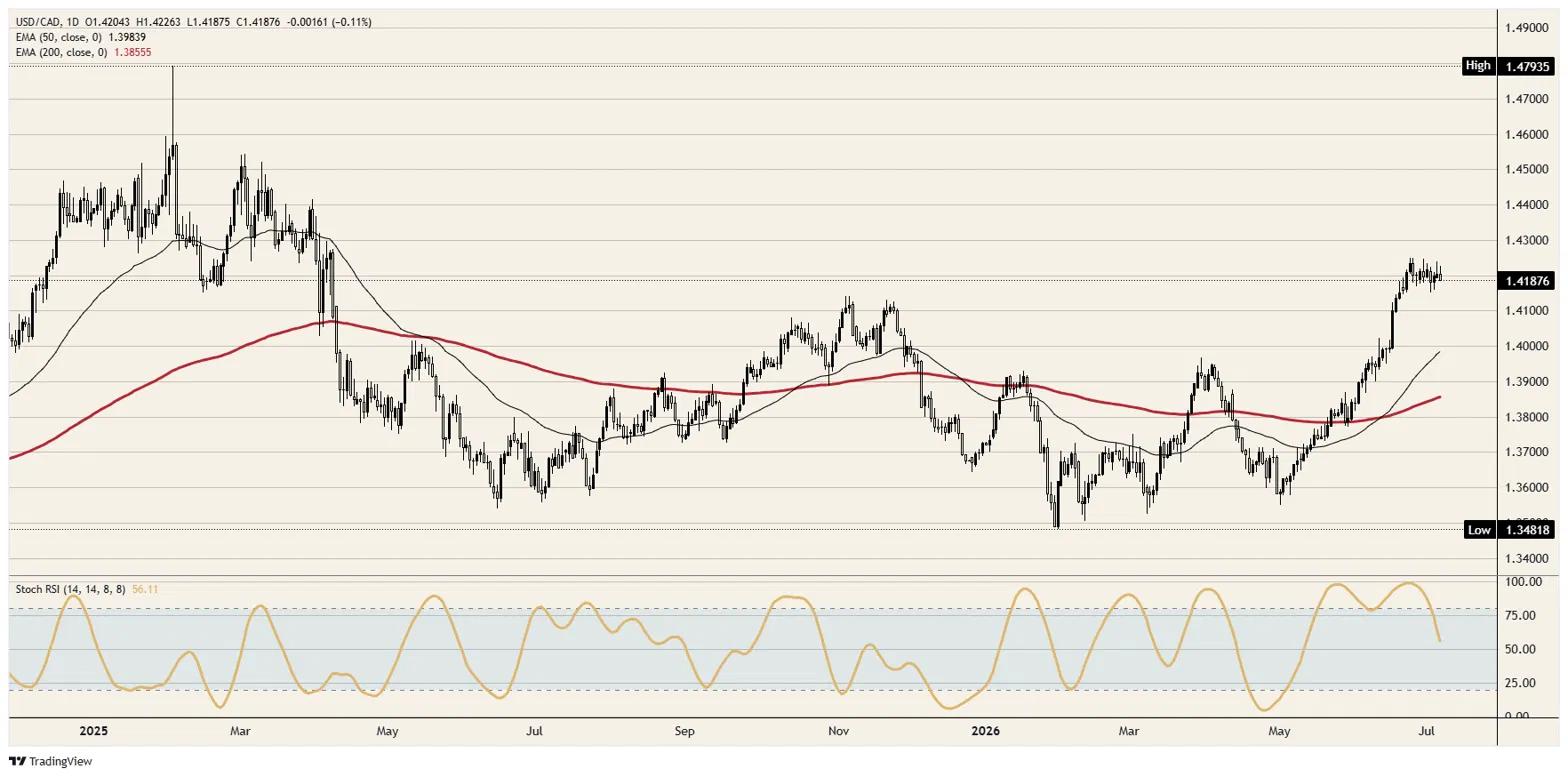
Resistance: The first ceiling sits at the recent swing high near 1.4250, the level that has capped the rebound off the spring low. A daily close above it opens a clean run at the 1.4300 handle, with little in the way until then.
Support: The first floor forms around 1.4150, then at the 1.4000 handle, which lines up with the rising 50-period Exponential Moving Average (EMA). Deeper support rests close to 1.3850 at the 200 EMA, a level USD/CAD reclaimed on the way up and would need to lose to call the trend into question.
Bias: Higher. USD/CAD is trading above both moving averages with momentum still pointed up, and the fundamental props under the Loonie are fading rather than firming. The Stochastic Relative Strength Index (Stoch RSI) rolling over from overbought argues for a pause rather than a reversal, and dips toward 1.4150 look like buying opportunities while that level holds.
USD/CAD daily chart
Canadian Dollar FAQs
The key factors driving the Canadian Dollar (CAD) are the level of interest rates set by the Bank of Canada (BoC), the price of Oil, Canada’s largest export, the health of its economy, inflation and the Trade Balance, which is the difference between the value of Canada’s exports versus its imports. Other factors include market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – with risk-on being CAD-positive. As its largest trading partner, the health of the US economy is also a key factor influencing the Canadian Dollar.
The Bank of Canada (BoC) has a significant influence on the Canadian Dollar by setting the level of interest rates that banks can lend to one another. This influences the level of interest rates for everyone. The main goal of the BoC is to maintain inflation at 1-3% by adjusting interest rates up or down. Relatively higher interest rates tend to be positive for the CAD. The Bank of Canada can also use quantitative easing and tightening to influence credit conditions, with the former CAD-negative and the latter CAD-positive.
The price of Oil is a key factor impacting the value of the Canadian Dollar. Petroleum is Canada’s biggest export, so Oil price tends to have an immediate impact on the CAD value. Generally, if Oil price rises CAD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Oil falls. Higher Oil prices also tend to result in a greater likelihood of a positive Trade Balance, which is also supportive of the CAD.
While inflation had always traditionally been thought of as a negative factor for a currency since it lowers the value of money, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Higher inflation tends to lead central banks to put up interest rates which attracts more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in Canada’s case is the Canadian Dollar.
Macroeconomic data releases gauge the health of the economy and can have an impact on the Canadian Dollar. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the CAD. A strong economy is good for the Canadian Dollar. Not only does it attract more foreign investment but it may encourage the Bank of Canada to put up interest rates, leading to a stronger currency. If economic data is weak, however, the CAD is likely to fall.
Author
Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















