British Pound double-teamed by soft CPI and a hawkish Fed
- GBP/USD fell to its lowest level of the session after the June Federal Reserve decision.
- Softer than expected UK inflation had already put the Pound on the back foot.
- The Bank of England's rate decision on Thursday is the next major catalyst.
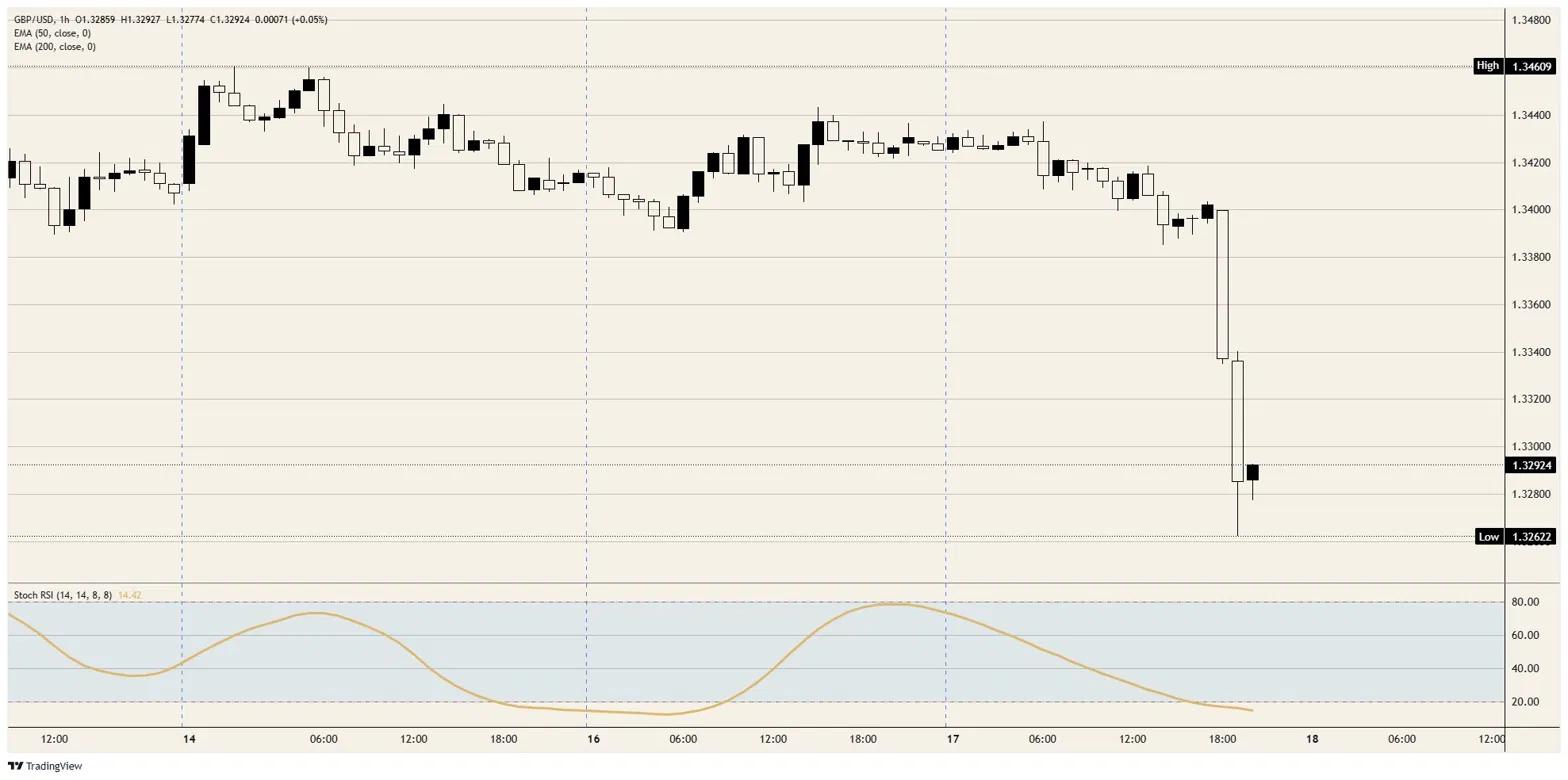
The British Pound (GBP) spent Wednesday absorbing blows from both sides of the Atlantic. Softer than expected UK inflation set a heavy tone in the morning, and Kevin Warsh's hawkish first Federal Reserve (Fed) decision finished the job in the evening. GBP/USD had been drifting near 1.3400 into the announcement and then collapsed close to 140 pips, tearing through 1.3350 and the 1.3300 handle to a session low near 1.3250 before steadying just below the figure.
The inflation miss that started it
The morning's Consumer Price Index (CPI) gave the Pound its first knock, with the May reading rising just 0.2% on the month against expectations of 0.4% and core annual inflation easing to 2.6% from a forecast 2.7%. Headline annual inflation held at 2.8%, so this was a miss rather than a collapse, but it was enough to nudge Bank of England (BoE) cut expectations and leave Sterling soft into the US session.
Then the Fed turned the screw
The Federal Open Market Committee (FOMC) held its target range at 3.50% to 3.75% on a unanimous 12 to 0 vote, a stark change from April's fractured 8 to 4 split, and deleted the easing bias. The Summary of Economic Projections (SEP) supplied the shock, lifting the median 2026 federal funds projection to roughly 3.8% from 3.4% and flipping the next move from a cut to a hike, after the 2026 Personal Consumption Expenditures (PCE) inflation projection blew out to 3.6% from 2.7%.
Warsh rewrites the rulebook
Warsh then used his first press conference to telegraph a sweeping communications overhaul. He floated holding press conferences only when the Fed has something to say, warned markets to expect changes to the SEP and the central bank's reporting by year-end, and appears to have withheld his own dot, the package of a Chair determined to wean the Fed off forward guidance. Treasury yields rose and the Dollar firmed across the board as he spoke.
September, then January
Rate pricing turned decisively hawkish. According to the CME FedWatch tool, a first Fed hike is now priced for September, where a 25 basis point increase is the most likely single outcome, and the curve leans toward a second hike by January. With the next couple of meetings treated as near-certain holds, the question has shifted entirely to the pace of tightening, a powerful tailwind for the Dollar against the Pound.
The Bank of England has the last word
Unlike the US, the UK calendar is busy into the weekend, and Thursday belongs to the BoE. The decision at 11:00 GMT is expected to leave Bank Rate at 3.75%, so the vote split is the real event; the consensus looks for two members to back a hike against one previously, a hawkish drift that today's soft CPI may complicate. UK labour data lands earlier on Thursday and retail sales close the week on Friday, giving Sterling plenty of domestic risk even as the US goes quiet.
Resistance: The 1.3300 handle the pair lost now caps the bounce, with 1.3350 the next barrier on any recovery.
Support: The session low near 1.3250 is the first floor, and a break there opens the 1.3200 handle.
Bias: Bearish, with the BoE the swing factor. A more hawkish vote split could spark a relief bounce, but soft UK inflation and a freshly hawkish Fed leave the path of least resistance lower while price holds below 1.3300.
GBP/USD 1-hour chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















