Breaking: United States private sector employment rises by 90K in September vs. 70K expected
Employment in the United States' (US) private sector increased by 90K in September, the Automatic Data Processing (ADP) reported on Wednesday. This reading followed the 36K increase recorded in August (revised from 38K) and came in better than the market expectation of 70K.
The publication noted that education, health care and leisure and hospitality sectors drove the increase in employment, while financial activities, professional and business services sectors showed weakness.
Commenting on the survey's findings, "it's a strong report, after a three-month slowdown, job creation rebounded and pay growth remained solid," noted Dr. Nela Richardson, Chief Economist at ADP.
Market reaction to ADP Employment Change data
This report failed to trigger a noticeable reaction in the US Dollar (USD). At the time of press, the USD Index was down 0.15% on the day at 101.23.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the weakest against the British Pound.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.13% | -0.43% | -0.14% | -0.04% | 0.26% | -0.09% | 0.04% | |
| EUR | 0.13% | -0.27% | -0.02% | 0.09% | 0.37% | 0.05% | 0.18% | |
| GBP | 0.43% | 0.27% | 0.25% | 0.38% | 0.65% | 0.35% | 0.47% | |
| JPY | 0.14% | 0.02% | -0.25% | 0.11% | 0.42% | 0.06% | 0.22% | |
| CAD | 0.04% | -0.09% | -0.38% | -0.11% | 0.31% | -0.04% | 0.11% | |
| AUD | -0.26% | -0.37% | -0.65% | -0.42% | -0.31% | -0.33% | -0.19% | |
| NZD | 0.09% | -0.05% | -0.35% | -0.06% | 0.04% | 0.33% | 0.14% | |
| CHF | -0.04% | -0.18% | -0.47% | -0.22% | -0.11% | 0.19% | -0.14% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
This section below was published as a preview of the ADP Employment Change data at 08:00 GMT.
- The US ADP Employment Change report is forecast to show a 72K increase in net employment in September.
- If the market consensus is confirmed, it will endorse the theory of US economic exceptionalism.
- The impact on the US Dollar is likely to depend on the outcome of the PCE Price Index due at the same time.
The Automatic Data Processing (ADP) Research Institute will release September’s monthly report on private-sector employment creation on Wednesday. The ADP Employment Change report is forecast to reveal that net employment in the United States (US) private sector increased by 72K this month, almost twice the 38K new jobs reported in August.
ADP data is closely watched by markets as it sets the sentiment ahead of the all-important Nonfarm Payrolls (NFP) report, usually released a couple of days later by the US Bureau of Labor Statistics. This time, however, the ADP report will have to share the spotlight with the key US Personal Consumption Expenditures (PCE) Price Index data, the Federal Reserve’s (Fed) gauge of choice for assessing inflationary trends, which will be released 15 minutes later and might end up stealing the show.
ADP jobs report is expected to reflect a resilient labour market
Markets hold an optimistic view of US employment trends, especially after the outstanding August Nonfarm Payrolls report, which showed a 162K net increase in job creation and a steady Unemployment Rate at 4.1%, its lowest level in more than a year.
Apart from that, more recent data has contributed to keeping spirits high, as analysts at OCBC note: “Recent claims data have continued to trend lower, suggesting labour market conditions remain firm.” Weekly ADP data has also been positive, as the latest reports showed that US private employers added an average of 20K jobs per week, up to the first week of this month.
Against this background, investors are expecting September’s labor data to confirm that the market remains tight, which, together with the strong inflationary pressures stemming from high energy prices, will pave the path for the Fed to tighten its monetary policy further in October or December at the latest. Futures markets are pricing in a 70% chance of a quarter-point interest rate hike in October and 60% odds that the US central bank will hike rates by 50 basis points before year-end, according to the data released by the CME Group’s FedWatch Tool.
It is worth recalling, however, that markets will contrast the ADP outcome with the PCE Price Index report released almost simultaneously for a more complete picture of the Fed’s monetary policy outlook. PCE inflation is widely expected to reflect upside pressures from high Oil prices, amid uncertainty in the Middle East, and show that consumer prices remain well above the Fed’s target. In that sense, employment data is seen as the sidekick to underpin the central bank’s hawkish stance this week.
Federal Reserve officials have reiterated that inflation pressures remain too high and that the bank might have to hike interest rates again. Fed Governor Lisa Cook went further on Monday, stating that the “number and magnitude of any future rate adjustments will be informed by inflation and labor market data,” thus increasing interest in this week’s releases.
When will the ADP report be released, and how could it affect the USD?
The US ADP Employment Change report will be out on Wednesday at 12:15 GMT, and it is expected to show that the private sector created 72K new jobs in September. If the final data meets expectations and is followed by hot PCE Price Index figures, it will boost hopes of another Fed interest rate hike in October and provide additional support to the US Dollar (USD).
Forex experts at Societe Generale anticipate that the combination of "higher inflation and resilient real-economy data could propel the Dollar Index to a near-2026 high (just 0.7% away) or push EUR/USD to a new low (only 0.5% away)," underscoring the potential for renewed Greenback strength even as investors digest the upcoming economic data releases.
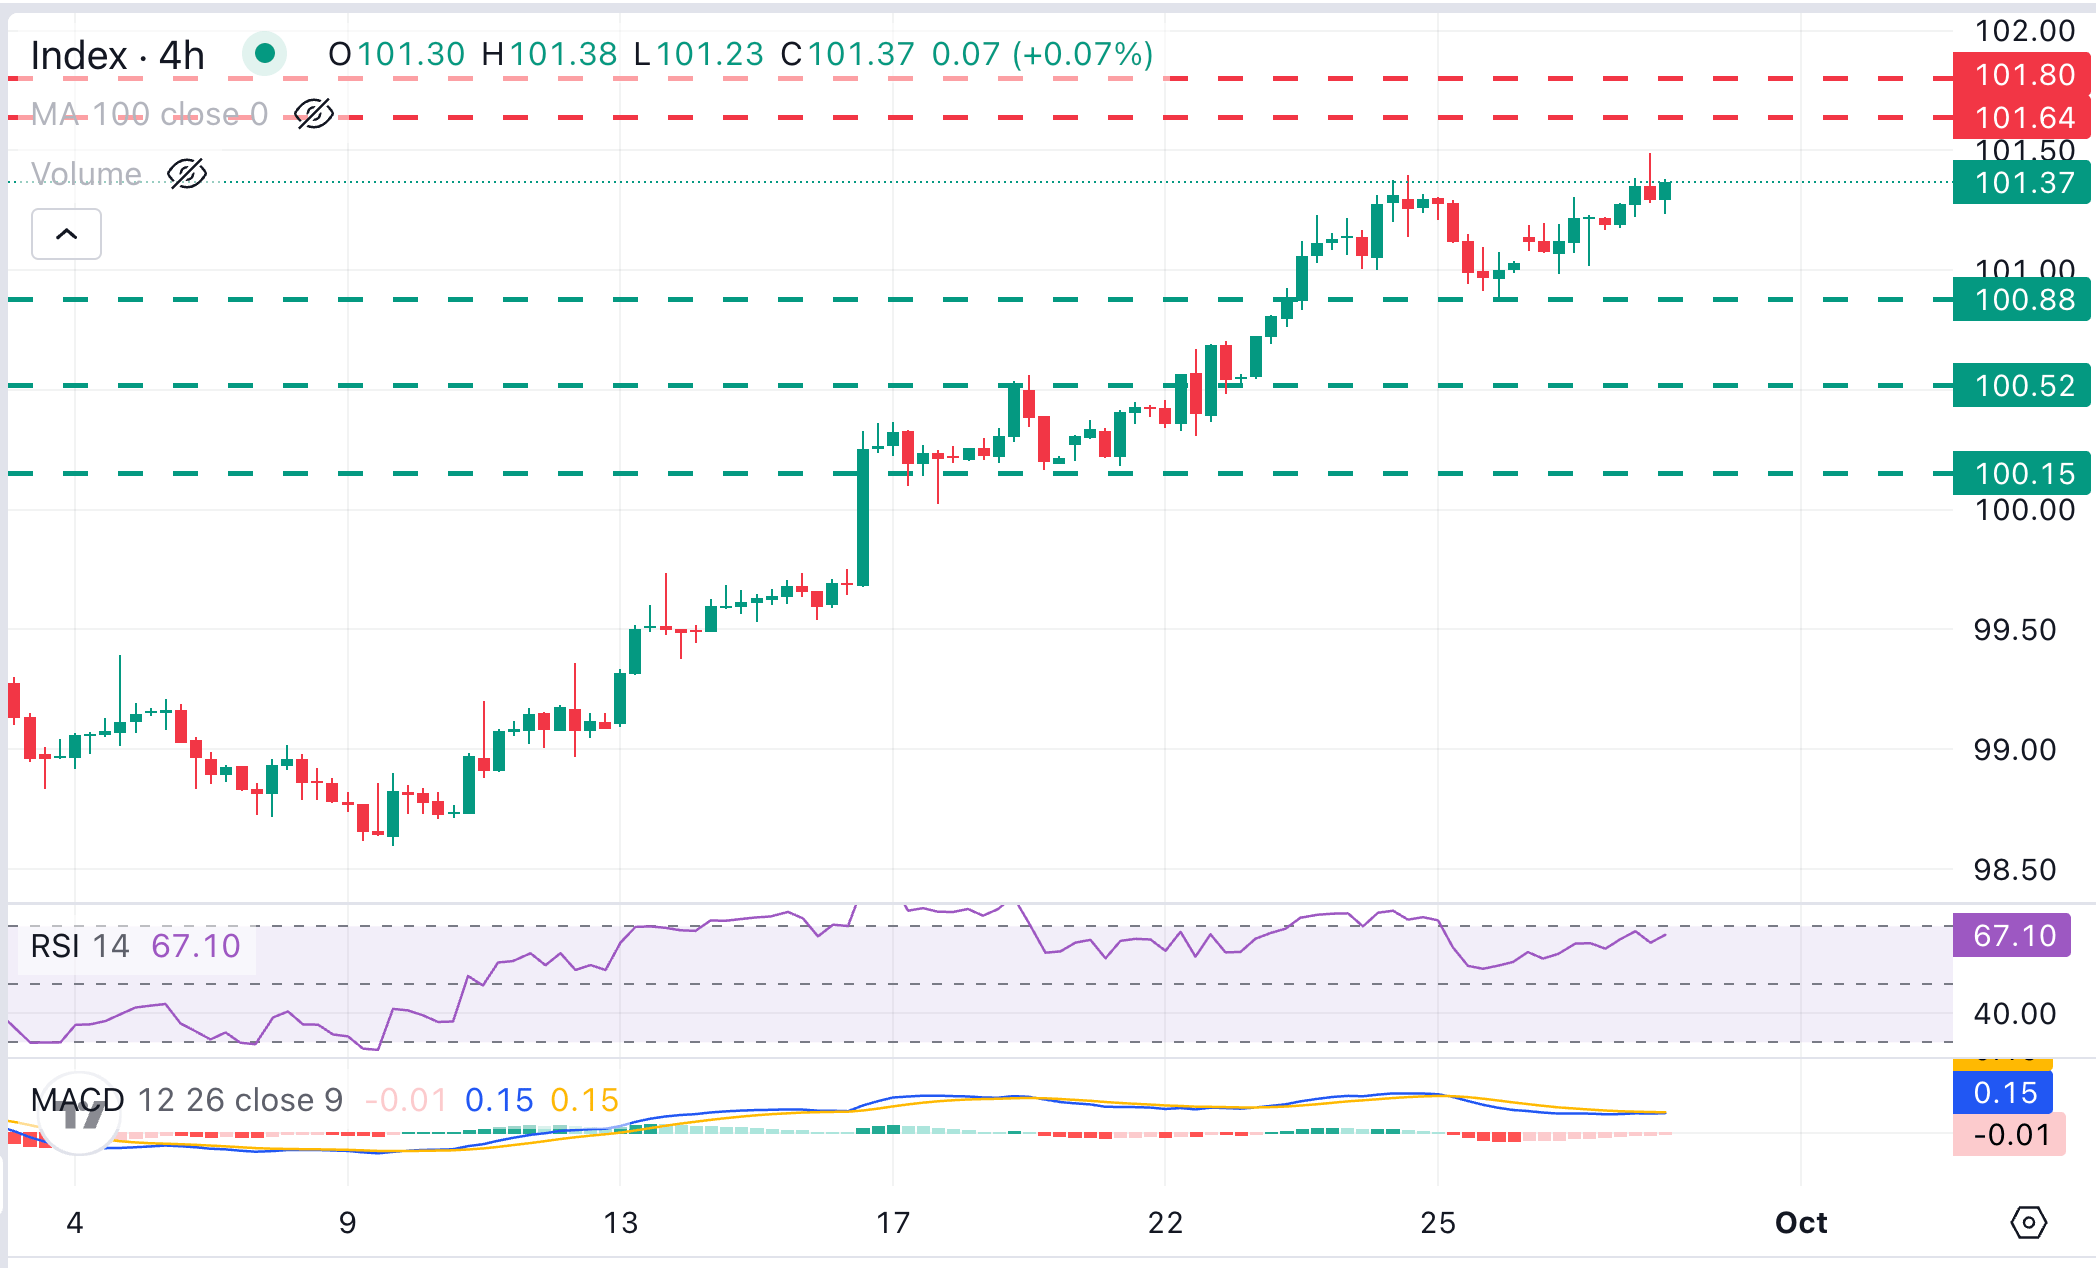
The US Dollar Index (DXY) technical picture shows a solid bullish trend, after rallying nearly 2.5% in less than three weeks, which has boosted price action to two-month highs near 101.50 at the time of writing. Fundamentals are supportive, but the Relative Strength Index (RSI) is reaching overbought levels on intraday charts, suggesting that the trend may be overextended and warning about a potential bearish correction.
According to Guillermo Alcalá, Analyst at FXStreet.com, bulls are likely to meet resistance at the 2026 highs of 101.64 and 101.80, July and June’s peaks, respectively. If these levels give way, the next target is the May 2025 high near 102.00. Bearish attempts, on the other hand, are likely to be tested at the ascending trendline support, now at 101.25 ahead of the September 25 low near 100.90. ”Further decline is likely to require a significant disappointment in US macroeconomic figures,” says Alcalá.
Economic Indicator
ADP Employment Change
The ADP Employment Change is a gauge of employment in the private sector released by the largest payroll processor in the US, Automatic Data Processing Inc. It measures the change in the number of people privately employed in the US. Generally speaking, a rise in the indicator has positive implications for consumer spending and is stimulative of economic growth. So a high reading is traditionally seen as bullish for the US Dollar (USD), while a low reading is seen as bearish.
Read more.Next release: Wed Sep 30, 2026 12:15
Frequency: Monthly
Consensus: 72K
Previous: 38K
Source: ADP Research Institute
Traders often consider employment figures from ADP, America’s largest payrolls provider, report as the harbinger of the Bureau of Labor Statistics release on Nonfarm Payrolls (usually published two days later), because of the correlation between the two. The overlaying of both series is quite high, but on individual months, the discrepancy can be substantial. Another reason FX traders follow this report is the same as with the NFP – a persistent vigorous growth in employment figures increases inflationary pressures, and with it, the likelihood that the Fed will raise interest rates. Actual figures beating consensus tend to be USD bullish.
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.

















