Why is the US Dollar climbing when its preferred inflation gauge is cooling?
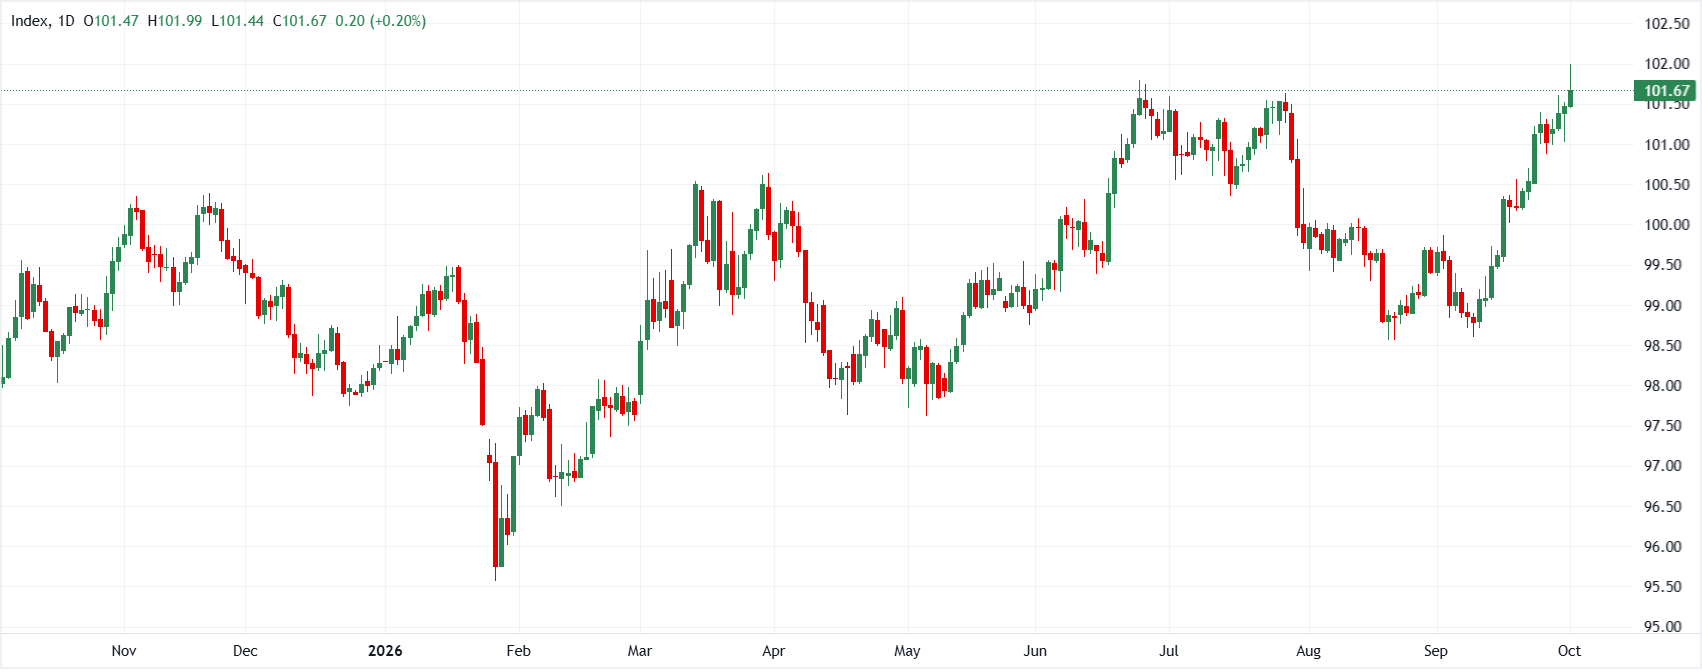
The US Dollar (USD) continues to display underlying strength, with the US Dollar Index (DXY) touching its June year-to-date high near 101.80 despite recent data showing a deceleration in core Personal Consumption Expenditures (PCE) inflation. While revised inflation metrics show slowing price momentum, robust underlying economic activity — marked by resilient consumer spending and firm capex — is keeping market expectations anchored to a firm US macroeconomic backdrop. As traders look ahead to upcoming Nonfarm Payrolls (NFP) and Consumer Price Index (CPI) releases, institutional strategists are debating whether softer inflation trends will prompt a more gradual Federal Reserve (Fed) tightening cycle or if sticky underlying price pressures will preserve the Greenback's upward momentum.
TD Securities expects sticky inflation and 3.0% Q3 GDP to keep Fed hawkish
Oscar Munoz and Eli Nir at TD Securities maintain that despite downward revisions to PCE inflation figures, the broader economic signal remains undeniably hawkish. Upgrading their Q3 GDP forecast to 3.0% annualized, they argue that resilient consumer demand, firm corporate profits, and sticky price pressures keep an October Fed rate hike firmly on the table.
"PCE and GDP revisions were a mixed bag with hawkish backward adjustments to growth and dovish adjustments to inflation. However, the underlying trend is the key story, and robust growth with rising inflation risks should continue to dominate the Fed's outlook... We have upgraded our Q3 GDP growth forecast to 3.0% q/q AR on the back of still firm consumer spending and capex. Domestic demand is strong... We now expect core PCE inflation will close 2026 at 3.0% Q4/Q4, and at 2.5% next year."
MUFG notes US Dollar resilience at 101.80 peak as softer PCE dampens aggressive hike bets
Lee Hardman at MUFG highlights that while the US Dollar Index reached its June year-to-date high of 101.80, softer inflation data and dovish central bank messaging are easing expectations for rapid monetary tightening. With 3-month annualized core PCE slowing to 2.1%, the likelihood of a back-to-back rate hike in October ahead of the US midterm elections has diminished, placing greater weight on upcoming labor market and CPI data.
"The US dollar’s upward momentum has continued even after recent Fed rhetoric and softer US inflation data should help to dampen expectations for more aggressive Fed hikes... After the downward revisions, there is clearer evidence of a slowdown in the Fed’s preferred measure of underlying inflation pressures. The three-month annualized rate of growth has fallen to just 2.1%. Looking back at the period since the US-Iran conflict began, the six-month annualized rate of growth has slowed to 2.7%... It makes it less likely that the Fed will hikes rates as aggressively as currently priced..."
The takeaway
The US Dollar's resilience near 101.80 highlights a foreign exchange market that is prioritizing robust US economic growth over decelerating short-term inflation metrics. While MUFG cautions that a slowdown in 3-month annualized core PCE to 2.1% removes the urgency for aggressive back-to-back Fed rate hikes, TD Securities projects that strong domestic demand — reflected in a 3.0% Q3 GDP forecast — and sticky 3.0% core PCE inflation by year-end will sustain Federal Reserve hawkishness and preserve the US Dollar's broader upward momentum.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author

FXStreet Insights Team
FXStreet
The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts. The content includes notes by commercial as well as additional insights by internal and external analysts.