New Zealand Dollar faces pressure against US Dollar as traders consider bigger Fed rate hike
- NZD/USD clings to losses near 0.5560 as the US Dollar outperforms.
- The US Dollar Index hits a fresh 18month high near 103.06.
- Traders also take the option of Fed’s bigger interest rate hike in December into consideration.
The New Zealand Dollar (NZD) is under pressure against the US Dollar (USD) on Thursday, holding onto its two day’s losses at around 0.5560 in the Asian trade.
The Kiwi pair trades vulnerably as the US Dollar continues its outperformance, with financial markets started pricing the possibility of a bigger interest rate hike by the Federal Reserve (Fed) in the December policy meeting.
At press time, the US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, trades 0.18% higher at around 103.06, the highest level seen in over 18 months.
Fed hike debate intensifies as Waller comments revive 50bp risk
Analysts at MUFG note that the latest market rethink has been “to consider the prospect of a 50bp hike,” stressing that this shift is “only now being considered because of Waller’s comments prior to the Consumer Price Index (CPI) report rather than the CPI report itself.” They highlight that “Waller’s comment that a stronger CPI print may warrant a 50bp hike has sparked a debate over whether Waller had knowledge of the CPI print,” helping to push front-end yields higher and reprice Fed expectations.
Fed’s Waller delivered a notably more hawkish tone on Tuesday, with a 9/10 FXS Speechtracker score standing well above the 7.3/10 historical average, underscoring a clear shift toward tighter policy bias. The conditional endorsement of a half-point December rate hike if October core CPI prints at 0.3% or higher, alongside support for a quarter-point hike even on better inflation data, signals a strong reaction function to any sign that inflation is drifting away from target. Emphasis on the breadth of price increases, insufficient restrictiveness of current policy, and the need for higher real rates reinforces upside risks for U.S. yields and supports the Dollar, while Waller’s downbeat view on near-term AI-driven productivity gains suggests limited relief from supply-side disinflation.
The FXS Fed Sentiment Index rose by 3.17 points to 145.50, firmly in hawkish territory and consistent with the elevated FXS Speechtracker reading. This move confirms that Fed communication is skewing more aggressively toward further tightening, a backdrop that should keep Dollar supported and weigh on risk-sensitive currencies as markets reprice December hike probabilities.
Meanwhile, the CME FedWatch tool shows that the odds of a 50 basis points (bps) interest rate hike in the December meeting are just 10%.
On the Kiwi front, the major driver would be market expectations for the Reserve Bank of New Zealand (RBNZ) policy meeting in December. The RBNZ will likely raise its Official Cash Rate (OCR) by 25 basis points (bps) to 3% after leaving them steady in the October meeting, as it signaled that “tighter monetary policy probably needed” amid upside inflation risks.
NZD/USD Technical Analysis
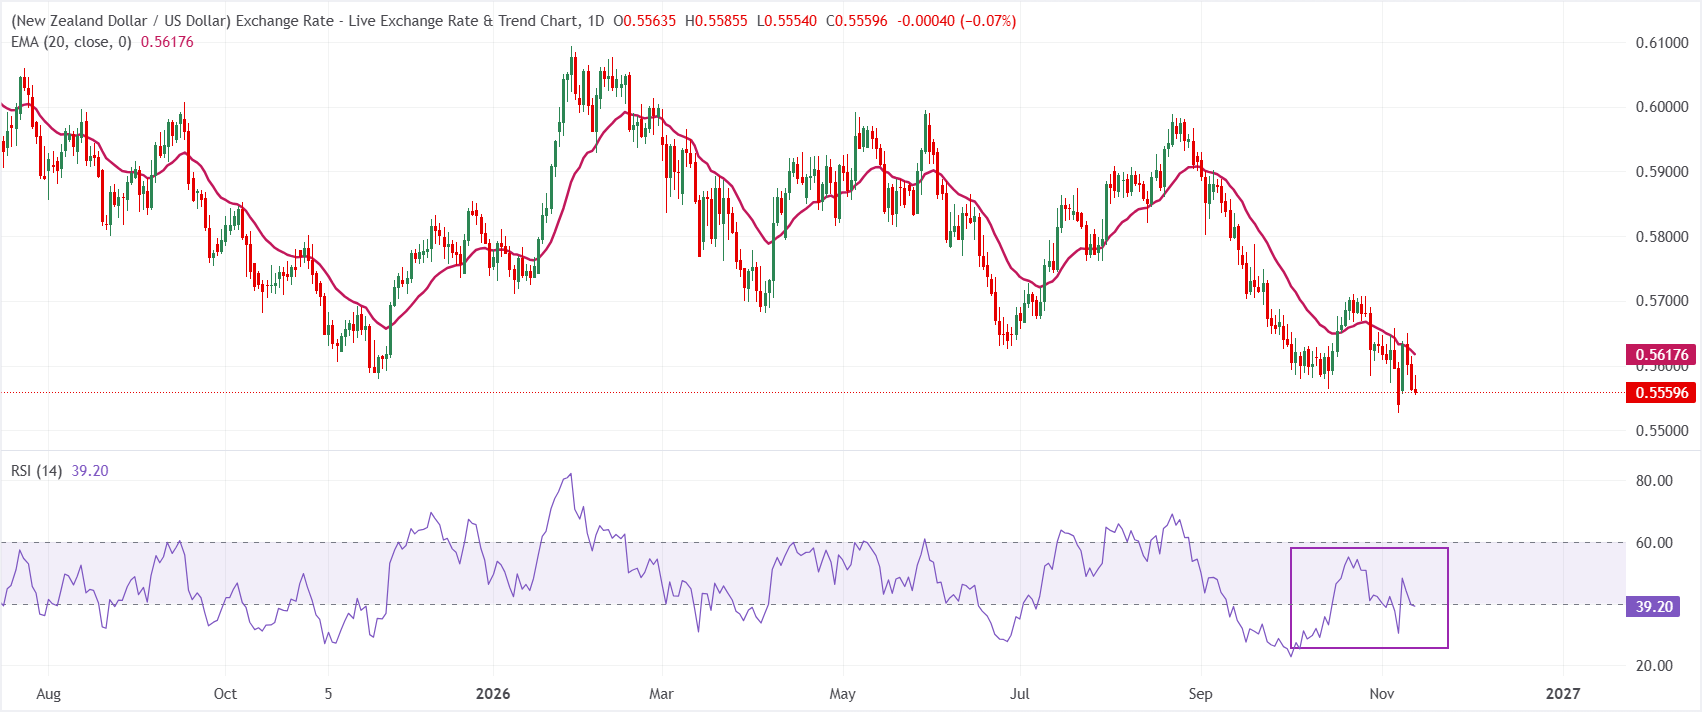
In the daily chart, NZD/USD trades at 0.5559, extending its decline below the 20-period exponential moving average (EMA) at 0.5618 and maintaining a bearish near-term bias. The pair trades under this short-term trend proxy, suggesting rallies remain capped, while the Relative Strength Index (14) around 39 points to weak but not extreme selling pressure after the latest slide.
On the topside, initial resistance is defined by the 20-day EMA at 0.5618, which is the first hurdle for any corrective rebound. A sustained break above this level would be needed to ease the current bearish tone, while failure to reclaim it keeps NZD/USD vulnerable to fresh lows, with support likely to emerge only at lower prior price floors not captured by the present indicator set.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Sagar Dua
FXStreet
Sagar Dua is associated with the financial markets from his college days. Along with pursuing post-graduation in Commerce in 2014, he started his markets training with chart analysis.