|

Denmark: Real spending in August is down compared to last year

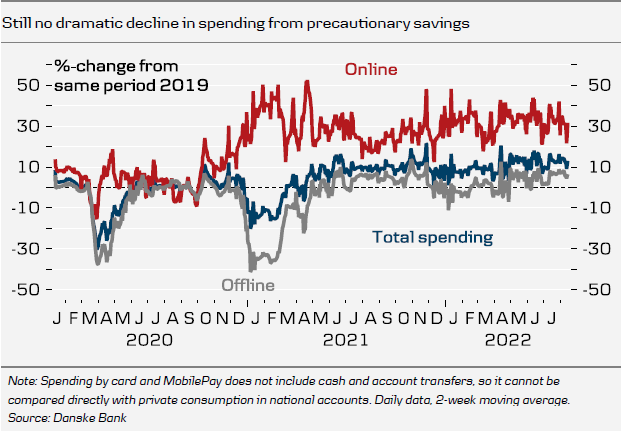
Danish card data suggests spending is holding up in the first two weeks of August, at around 9% above 2019 and 2020-levels. Compared to 2021, however, spending is only up 1.9%. Considering the steep increase in prices, this amounts to a real decline compared to last year. That being said, consumers continue to show resilience in the face of an unprecedented erosion of disposable real income and historically low consumer confidence.

Travel spending saw a surge through spring and early summer, as receding Covid fears spurred last-minute holiday planning. In August, this has been replaced by a steady decline in spending, when accounting for normal seasonal patterns. Travel spending is a luxury good, and therefore likely to be affected by weaker household finances. Increasing uncertainty about international Covid restriction during fall and winter is likely to also put a damper on spending.

Restaurant spending continues to perform well, with spending for the first two weeks of august up 8 percent compared to 2021 and 29% compared to 2019.

The mainl weakness is in retail spending. Compared to the first two weeks of August 2021, retail spending is down by 2.9%. Given the increase in prices of notably food and home goods, the decline is significant in real terms. However, last summer still had above-normal retail spending due to Covid. Compared to 2019, nominal retail spending is up 8.4%.

Gasoline prices have moderated since mid-June, which is also visible in the data.
Chart

Download The Full Spending Monitor

Author

Danske Research Team

Danske Research Team

Danske Bank A/S

Research is part of Danske Bank Markets and operate as Danske Bank's research department. The department monitors financial markets and economic trends of relevance to Danske Bank Markets and its clients.


More from Danske Research Team
Share:

Editor's Picks

AUD/USD keeps the red near 0.6950 after weak Aussie jobs data

AUD/USD holds losses near 0.6950 on disappointing Australian jobs data, extending the previous day's retracement slide from the monthly high and hitting a fresh weekly low during Thursday’s Asian session. Meanwhile, declining US bond yields drag the US Dollar away from the April 2025 high, touched after Wednesday's hot US CPI, helping limit losses for the currency pair.

USD/JPY slides back below 158.00 as USD reverses post-CPI gains

USD/JPY extends the previous day's pullback from a three-week high, attracting follow-through selling and sliding below 158.00 during Thursday's Asian session. Traders remain on high alert amid speculation that authorities will step in to prop up the Japanese Yen. The US Dollar, meanwhile, reverses Wednesday's hot CPI-led gains to April 2025 highs as US bond yields retreat on China bond-buying talk, further pressuring the pair.

Gold pares intraday gains, trades below $4,150 as Fed hike bets cap upside

Gold struggles to capitalize on its strong Asian session move up on Thursday and currently trades below $4,150. The commodity, however, retains an intraday bullish bias, snapping a three-day losing streak to a one-week low, touched on Wednesday, amid a broadly weaker US Dollar (USD). 

Zcash declines as US inflation surprise offsets fresh ETF inflows
Zcash (ZEC) is trading in the red on Friday, extending its previous day’s roughly 6% losses as the broader cryptocurrency market falls on rising US inflation. The US Consumer Price Index (CPI) print came in higher than expected, at an annual increase of 3.7% versus the expected 3.6%, raising concerns about inflation and rate hikes.
China seems routing US Treasury holdings through Canada

According to a Bloomberg report, China seems to be moving United States securities to non-US custodian banks in other countries, masking its role in financing US deficits.

Has Bitcoin really escaped the macro forces it was built to fight?
Over 17 years ago, Satoshi Nakamoto designed Bitcoin (BTC) on the back of a global financial crisis as an alternative to the global monetary system outside the control of central banks, governments and traditional intermediaries. This raises a key question: has Bitcoin really become independent of the macroeconomic forces it was built to challenge?