Silver needs 39.9 million more ounces of coins this year
The forecast underpinning silver's 2026 deficit assumes American investors buy 88% more metal this year, and their absence so far has left coins cheaper to buy than at most points this year.
The same forecast explains why. It assumes silver returns to early 2026 levels to bring those buyers back, and early 2026 is when the metal traded above $110 an ounce and briefly above $120. It closed on Monday at $65.90. Most of this year's forecast deficit rests on those buyers returning anyway, and anyone buying while they stay away is paying less to do it.
Silver has spent the first week of September taking its direction from the rate outlook and the Middle East rather than from anything in the metal itself. Friday's August payrolls report came in far stronger than expected, at 162,000 jobs against forecasts near 56,000. That lifted the odds of a rate increase at the September 16 meeting to around 58%, from roughly 50% before the release. Producer prices land on Thursday and consumer prices on Friday. For the wider market picture, Golden Meadow® publishes ongoing analysis, and you can see how silver has traded this year alongside it.
What the deficit number assumes
The 2026 silver deficit is forecast at 46.3 Moz by Metals Focus and the Silver Institute, the sixth consecutive annual shortfall, with five complete and this year a forecast. That number gets repeated widely. The demand line it depends on does not.
Coin and net bar demand is forecast at 257.6 Moz for 2026 against 217.7 Moz in 2025. The survey puts that rise at 18%, and 18.3% on the two printed figures. It expects the increase to be a second consecutive annual gain and the highest level since 2022, driven mostly by western markets. In ounces it is 39.9 Moz of additional physical investment demand, and it equals 86% of the entire forecast deficit.
Put plainly: if ordinary investors do not buy roughly 40 million more ounces of coins and bars this year than they did last year, the published balance does not hold as published.
The survey names the United States directly
The survey does not lean vaguely on "the rest of the world." It names the market that has been weakest.
It records physical investment rising 13% in 2025, a first annual increase in three years, with double-digit gains widespread geographically and the United States as the only exception. American investment almost halved, to its lowest level since at least the 2008 financial crisis. Then it forecasts a recovery: US coin and bar demand up 57% this year, after four years of losses that cut demand 69% from its 2021 peak, and US physical investment up 88%.
Those two percentages are not alternative estimates of the same thing. Coin and net bar demand is the balance-table series and it includes commemorative coins. Physical investment is the narrower series and it does not. The 257.6 Moz total and the 57% figure belong to the first; the 88% belongs to the second.
The survey gives its reasoning, and it is a fair one. American buying jumped in early 2026 to levels echoing the frenzy of 2020 to 2022, liquidations briefly dried up, and the absence of selling since suggests retail holders remain bullish even without bargain hunting at lower prices. It adds, fairly, that this year's gains look dramatic but will only erase last year's losses.
And then the condition. Metals Focus expects the silver price to revisit early 2026 levels, which it says should attract retail buying back in. The 88% rebound is not forecast to happen at today's price. It is forecast to happen at a considerably higher one.
What the coin channel is actually doing
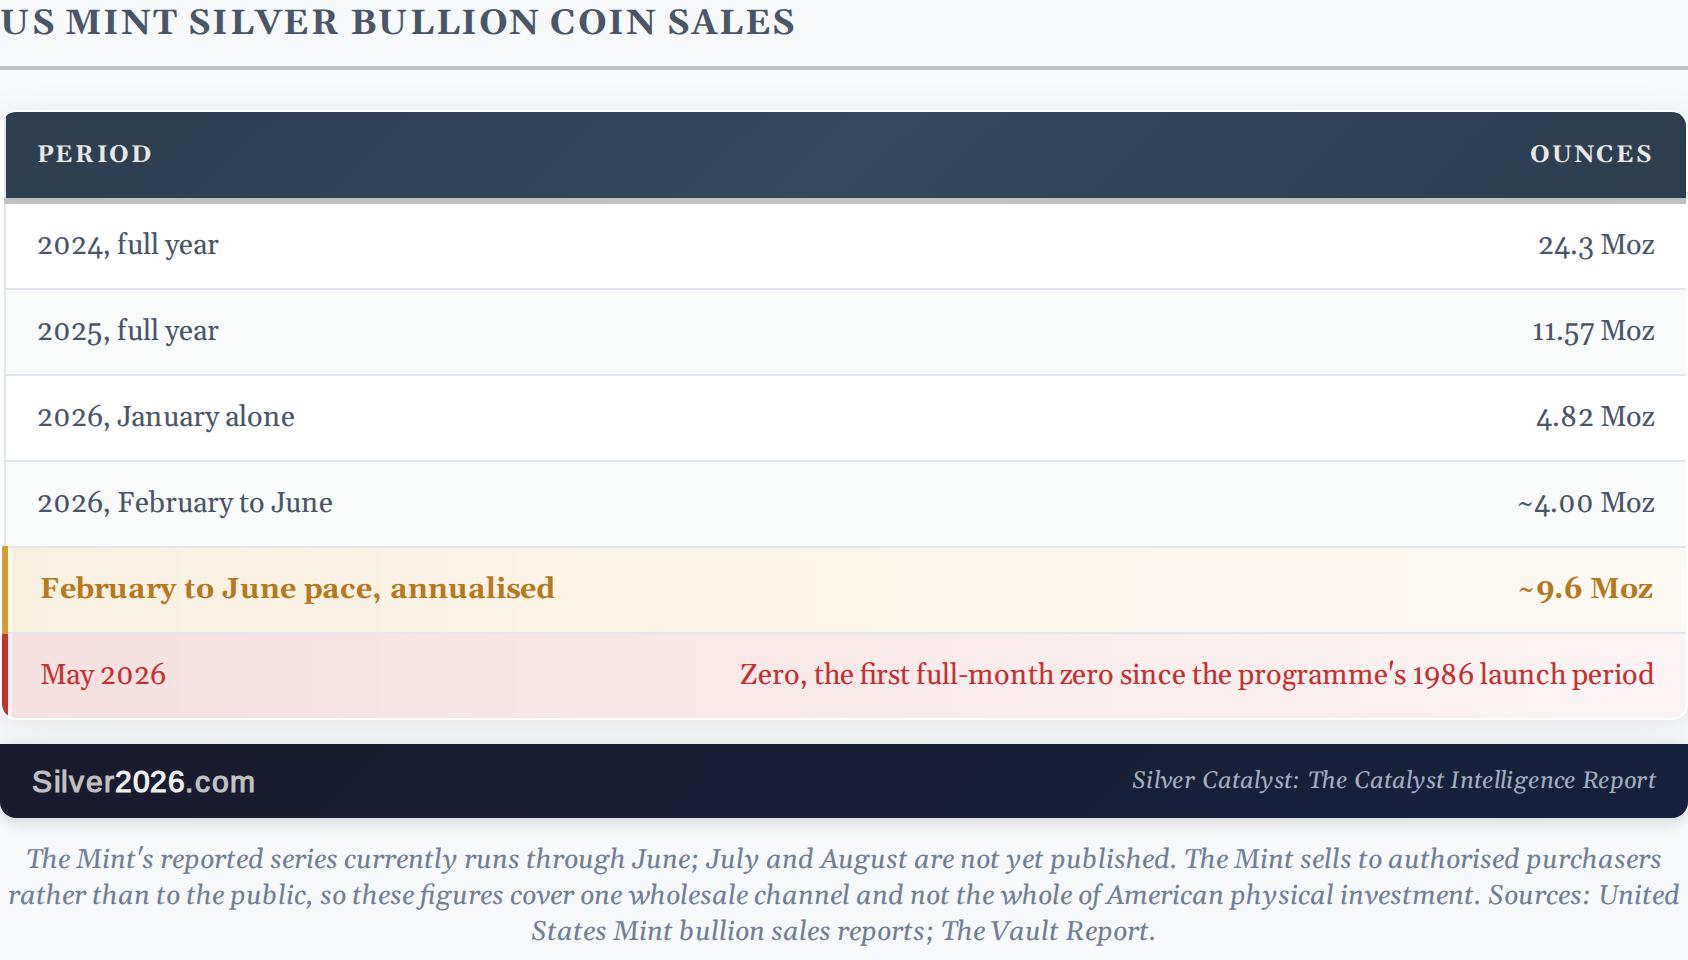
Sources: US Mint bullion sales data | The Vault Report
Two caveats belong with that table.
The Mint's reported series currently runs through June. July and August are not yet published, so nothing here tells you what the last two months looked like. And the Mint sells to authorised purchasers rather than to the public, which makes these figures one wholesale channel rather than the whole of American physical investment. Bars, rounds and private-mint product sit outside them entirely.
With those stated, the direction is clear. Running at the February to June pace, the channel annualises near 9.6 Moz, against 11.57 Moz for the whole of 2025 and 24.3 Moz in 2024. The May zero was demand-driven rather than a Mint suspension. Wholesalers held back because ordinary buyers would not pay the premiums on offer and dealers were already clearing repurchased coins at a discount.
Dealer pricing says the same thing from the other side of the counter. The lowest tracked premium on a one-ounce American Silver Eagle averaged 6.87% in August against 8.48% in July, per the premium history series, a fall of 1.61 percentage points in a month when spot rose 16.5%. The same series recorded a high of 19.16% in February and a low of 5.30% in April, so the year has taken premiums from the top of that range to near the bottom. Premiums fall when coins are easy to find.
The metal that did arrive came in through a different door
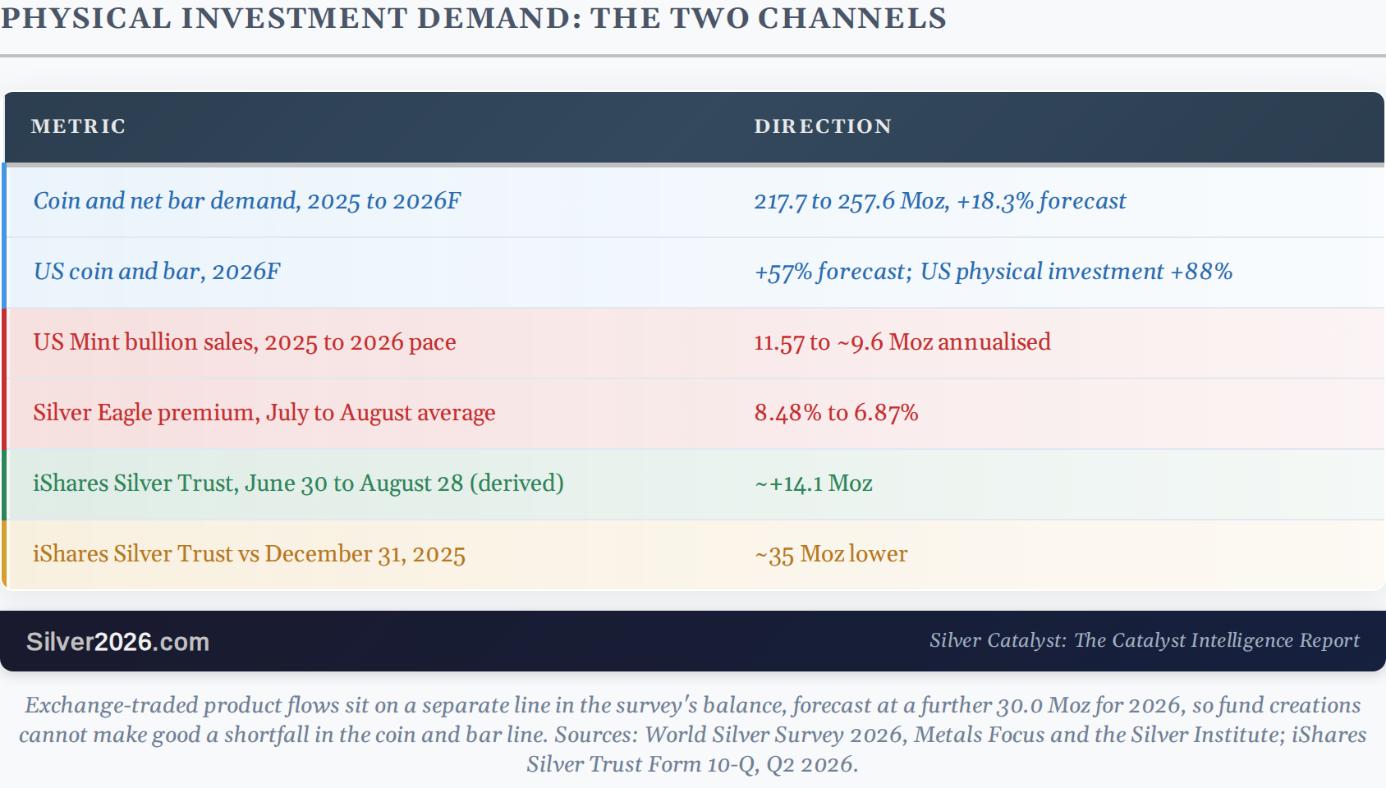
Sources: World Silver Survey 2026, Metals Focus and the Silver Institute | iShares Silver Trust Form 10-Q, Q2 2026
The iShares Silver Trust held roughly 493.9 Moz on August 28, on a figure derived from its share count rather than one the trust publishes, against 479.8 Moz at the end of June. That is about 14.1 Moz added across July and August, or the equivalent of some 30% of this year's forecast deficit, absorbed by one fund while the coin channel produced almost nothing.
It is tempting to treat that as the gap being filled. It is not, and the accounting is worth setting out, because the two flows are easy to run together.
Exchange-traded product flows sit on their own line in the survey's balance, forecast at a further 30.0 Moz for 2026, and the headline deficit is struck before they are counted. Fund creations therefore cannot make good a shortfall in the coin and bar line. They pull from the same metal, which still tightens the market, but it does not repair the line the forecast rests on. The trust is also still around 35 Moz below where it stood at the end of December.
What this means to Silver investors
Two answers, and they belong together: bad for this year's published balance, good for anyone still accumulating.
The bad half is the arithmetic. The forecast needs 39.9 Moz of additional coin and bar demand, including a 57% American recovery, and the one American channel we can see is running below its own 2025 pace. The rebound is conditioned on a price the market is currently moving away from rather than toward. If that condition fails, the 46.3 Moz deficit is a forecast with a soft leg, and that is worth saying alongside the headline rather than instead of it.
The good half is the same fact from the buyer's side. Premiums near 6.87% mean coins are easy to find. That is close to the bottom of this year's range, which ran from 19.16% in February to 5.30% in April, and a long way from the 2021 to 2022 rush when Eagle premiums at times exceeded 50%. A buyer building a position is paying less friction than at most points this year, and that advantage exists precisely because demand is weak.
Weak is not the same as broken, and this part of the survey's reasoning holds up. American holders stopped adding, but they did not start selling. The survey records liquidations briefly drying up during the early 2026 buying, and its read at the time of writing was still a lack of them, which is what separates a pause from a rout. Coins bought on the way to $120 have not come back out at $66. That is a better base to rebuild demand from than a market where holders sell into every rally, and the survey gives it as a reason for expecting them back.
None of this is evidence of Western scarcity. A premium curve that fell while the metal rose 16.5% in a month is not what a shortage looks like. I would rather say that plainly than let a reader infer tightness the data does not show. The Convergence Score I publish in each issue did not move this time, and this Deep Dive is one of the reasons.
The longer-term case does not rest on any of this. It rests on a supply side that cannot respond quickly to price, which is a separate argument built on separate evidence. The 2026 balance is narrower. It carries a demand assumption that the survey itself ties to a price the market has since moved away from, and that is the thing to watch before the next survey.
Want free follow-ups to the above article and details not available to 99%+ investors? Sign up to our free newsletter today!
Author

Przemyslaw Radomski, CFA
Gold Price Forecast
Przemyslaw Radomski, CFA (PR) is a precious metals investor and analyst who takes advantage of the emotionality on the markets, and invites you to do the same. His company, Sunshine Profits, publishes analytical software that any

















