Income in perspective
This blog was motivated by discussions I had with friends, following the eye-popping reports of third quarter earnings by oil and gas companies. Here’s a sampling of earnings reported for the quarter ending September 30, 2026, and their percent changes from the same quarter a year earlier:
- ExxonMobil — $15.4 billion; +105%
- Chevron — $9.9 billion; +183%
- ConocoPhillips — $4.0 billion; +135%
- Valero — $6.8 billion; +518%
My friends expressed some measure of condemnation for these companies, thinking that it was unseemly for them to generate such generous earnings while so many people are struggling to afford their products. Was this a case of these companies earning excess profits or engaging in price gouging? I thought the question deserved a closer look. I begin with an appreciation of the fact that, in and of themselves, the above earnings figures are misleading. Earnings must be considered relative to something else before we can legitimately assess how they should be categorized.
Consider three different metrics that allow us to evaluate these companies’ earnings in a more meaningful context than simply looking at the earnings figures on their own: gross margin, return on equity, and return on assets. The table below reports these figures for the companies listed above. The data are taken from reports posted on the Fidelity website, and they reflect earnings reported for the trailing 12 months. Gross margin measures the difference between revenues and the cost of goods sold, relative to revenues. Return on equity measures earnings relative to book value (i.e., equity). Finally, return on assets measures earnings relative to total assets.
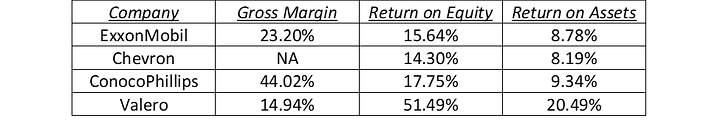
All these measures are subject to important idiosyncratic considerations, making direct comparisons problematic. Regardless, these data are what they are, and in light of the concerns about these earnings, it’s appropriate to view these statistics relative to those of other companies and other industries. My effort is hardly comprehensive, but still… I’ve arbitrarily chosen to look at the same statistics for four other companies in very different industries: Walmart, Bank of America, Coca-Cola, and Apple.
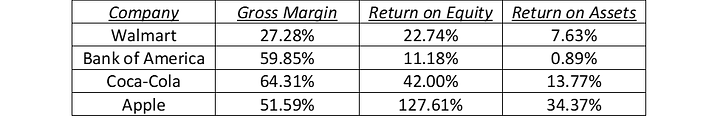
Gross Margin Comparison: Except for Valero, the gross margins of the non-energy companies I’ve looked at exceed those of the energy companies.
Return on Equity Comparison: Return on equity varies considerably across companies. The range for the energy companies listed above is from 14.30% to 51.49%. For the non-energy companies, the range is from 11.18% to 127.61%. (I’ve learned that Apple’s return on equity was exaggerated as a consequence of large share repurchases that reduced its book equity and thus elevated this statistic.)
Return on Assets comparison: This statistic is highly influenced by a firm’s capital structure with return on assets being particularly sensitive to leverage. It’s characteristic of banks to have significantly lower returns on assets due to this consideration. Ignoring that outlier, returns on assets for the non-energy companies appear to be broadly comparable to those of the energy companies.
The bottom line is that while the recent earnings reported by these oil and gas companies are large, we should generally expect large earnings from large companies. The case that their earnings are unusually large relative to other large companies, however, doesn’t appear to hold. These statistics vary considerably not only across companies but also across industries; and the available financial metrics provide little compelling evidence that these oil and gas companies are earning extraordinary returns relative to other large corporations. Put another way, based on the admittedly few non-energy companies that I’ve looked at, the performance of the oil and gas sector appears to be unremarkable. Could these companies have refrained from raising the prices of their products by as much as they did? Likely so, at least to some extent; but has the case been made that they engaged in price gouging? It’s not clear that they have.
On the other hand, another possible conclusion I’ve made — possibly much more consequential — is just how tenuous is the use of these common metrics. And yet they are the foundation upon which myriad investors base their decisions. I marvel at the strength of conviction a good many analysts present, given the ambiguities of the data upon which they base their valuations.
Author

Ira Kawaller
Derivatives Litigation Services, LLC
Ira Kawaller is the principal and founder of Derivatives Litigation Services.