US Dollar Index Price Forecast: DXY reaches fresh yearly high, but RSI turns overbought
- The US Dollar climbs to a fresh year-to-date high as strong economic growth and sticky inflation support a hawkish Fed outlook.
- DXY holds above its key daily moving averages after forming a double bottom near 98.50.
- Bullish momentum remains strong, although overbought conditions raise the risk of near-term consolidation.
The US Dollar Index (DXY) rally gathers pace on Thursday, climbing to a fresh year-to-date high as resilient US economic growth, a firm labour market and stubborn inflation support expectations of further monetary policy tightening by the Federal Reserve (Fed). Meanwhile, elevated US Treasury yields provide additional support to the Greenback by increasing the appeal of Dollar-denominated assets.
US Dollar Price This Year
The table below shows the percentage change of US Dollar (USD) against listed major currencies this year. US Dollar was the strongest against the Swiss Franc.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 4.69% | 2.24% | 1.11% | 3.97% | -3.50% | 3.49% | 5.11% | |
| EUR | -4.69% | -2.39% | -3.34% | -0.63% | -7.48% | -1.09% | 0.47% | |
| GBP | -2.24% | 2.39% | -0.98% | 1.81% | -5.22% | 1.33% | 2.93% | |
| JPY | -1.11% | 3.34% | 0.98% | 2.71% | -4.47% | 1.84% | 4.06% | |
| CAD | -3.97% | 0.63% | -1.81% | -2.71% | -6.99% | -0.85% | 1.11% | |
| AUD | 3.50% | 7.48% | 5.22% | 4.47% | 6.99% | 6.90% | 8.58% | |
| NZD | -3.49% | 1.09% | -1.33% | -1.84% | 0.85% | -6.90% | 1.58% | |
| CHF | -5.11% | -0.47% | -2.93% | -4.06% | -1.11% | -8.58% | -1.58% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
At the time of writing, the index trades around 102.18, up 0.70% on the day, after gaining 2.07% in September. Traders now look ahead to Friday’s US Nonfarm Payrolls (NFP) report. Strong data could further boost the Greenback, while a weaker reading could trigger some profit-taking.
Strategists at Brown Brothers Harriman observe that recent USD gains are closely aligned with “widening US-G6 interest rate differentials,” even as “tightening by other major central banks limits policy divergence with the Fed.” In their view, the Dollar’s appeal is reinforced by “US economic growth outperformance and strong foreign appetite for US securities,” factors that together “can keep USD risks skewed to the upside” despite the narrowing scope for further relative policy moves.
Technical Analysis
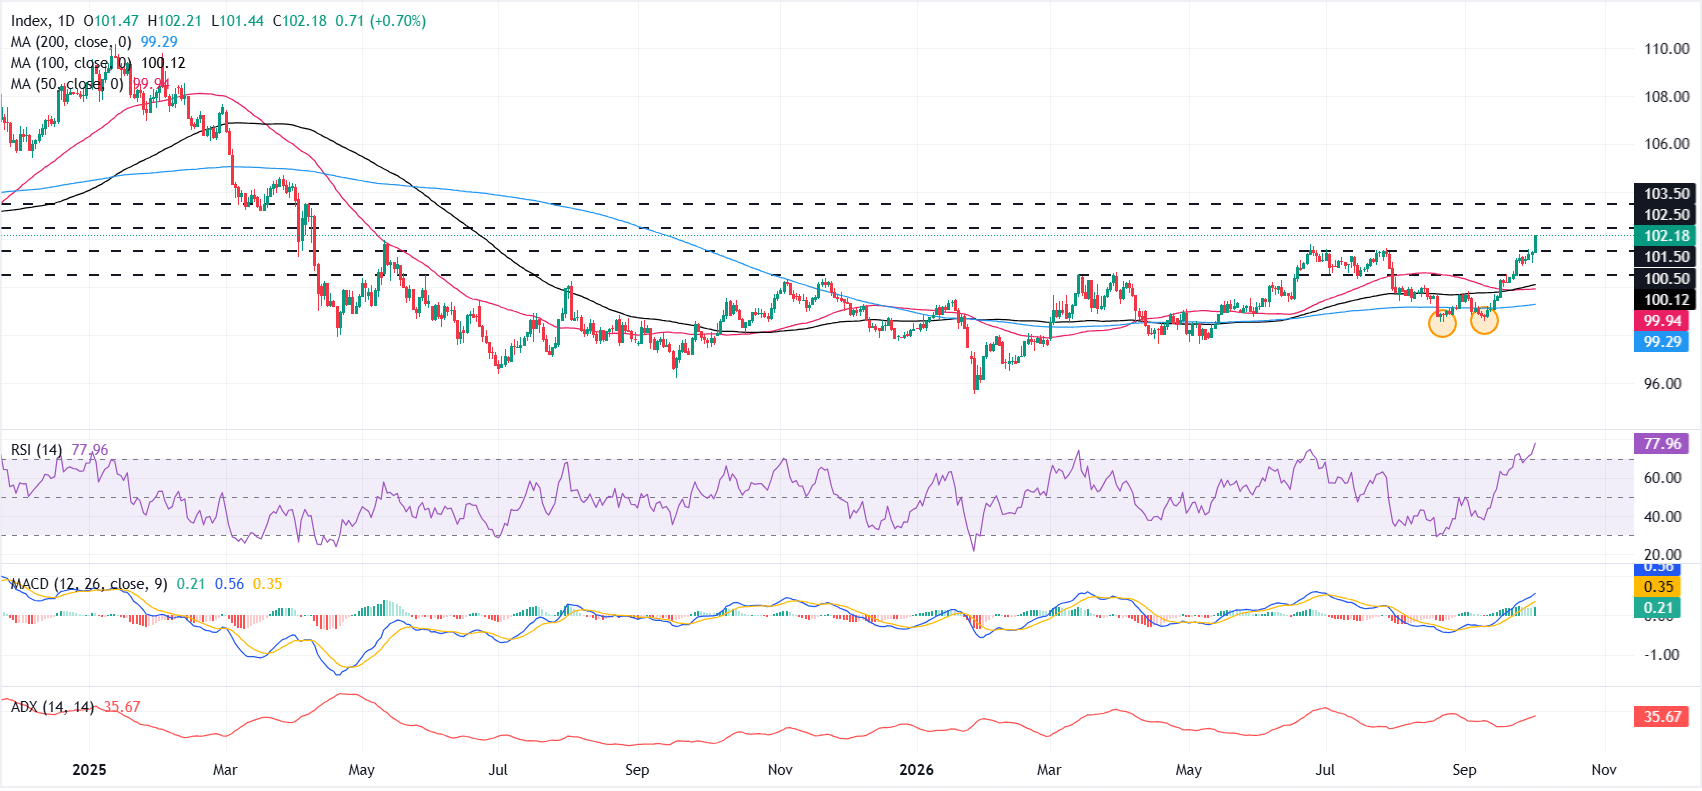
From a technical perspective, the US Dollar Index maintains a strong bullish bias after forming a double bottom near 98.50 in early September and reclaiming its key daily Simple Moving Averages (SMAs). The index now holds above the 50-day, 100-day and 200-day SMAs, which are clustered between 99.29 and 100.12.
Momentum indicators also favour buyers. The Relative Strength Index (RSI) stands near 78, while the Moving Average Convergence Divergence (MACD) remains in positive territory, pointing to firm upside momentum. The Average Directional Index (ADX) near 35 confirms that the underlying trend is gaining strength. However, overbought RSI conditions suggest that the rally could pause or consolidate before extending higher.
On the topside, a sustained move above 102.00 would keep the focus on immediate resistance at 102.50, followed by the 103.50 area. On the downside, a return below 102.00 would bring initial support at 101.50 into focus, with a deeper pullback exposing 100.50.
The outlook remains constructive as long as the index holds above the moving-average cluster, comprising the 100-day SMA at 100.12, the 50-day SMA at 99.94 and the 200-day SMA at 99.29. A decisive break below these averages would weaken the bullish structure and expose the double-bottom area near 98.50, which provides stronger support.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Vishal Chaturvedi
FXStreet
I am a macro-focused research analyst with over four years of experience covering forex and commodities market. I enjoy breaking down complex economic trends and turning them into clear, actionable insights that help traders stay ahead of the curve.