The Euro sells off hard as the French-German bond gap widens
- EUR/USD sells off hard to its lowest since May 2025 as the French-German bond gap widens.
- France pays 130 basis points over Germany for ten-year debt, the most since 2012.
- Two ECB hikes this year take the deposit rate to 2.50%.
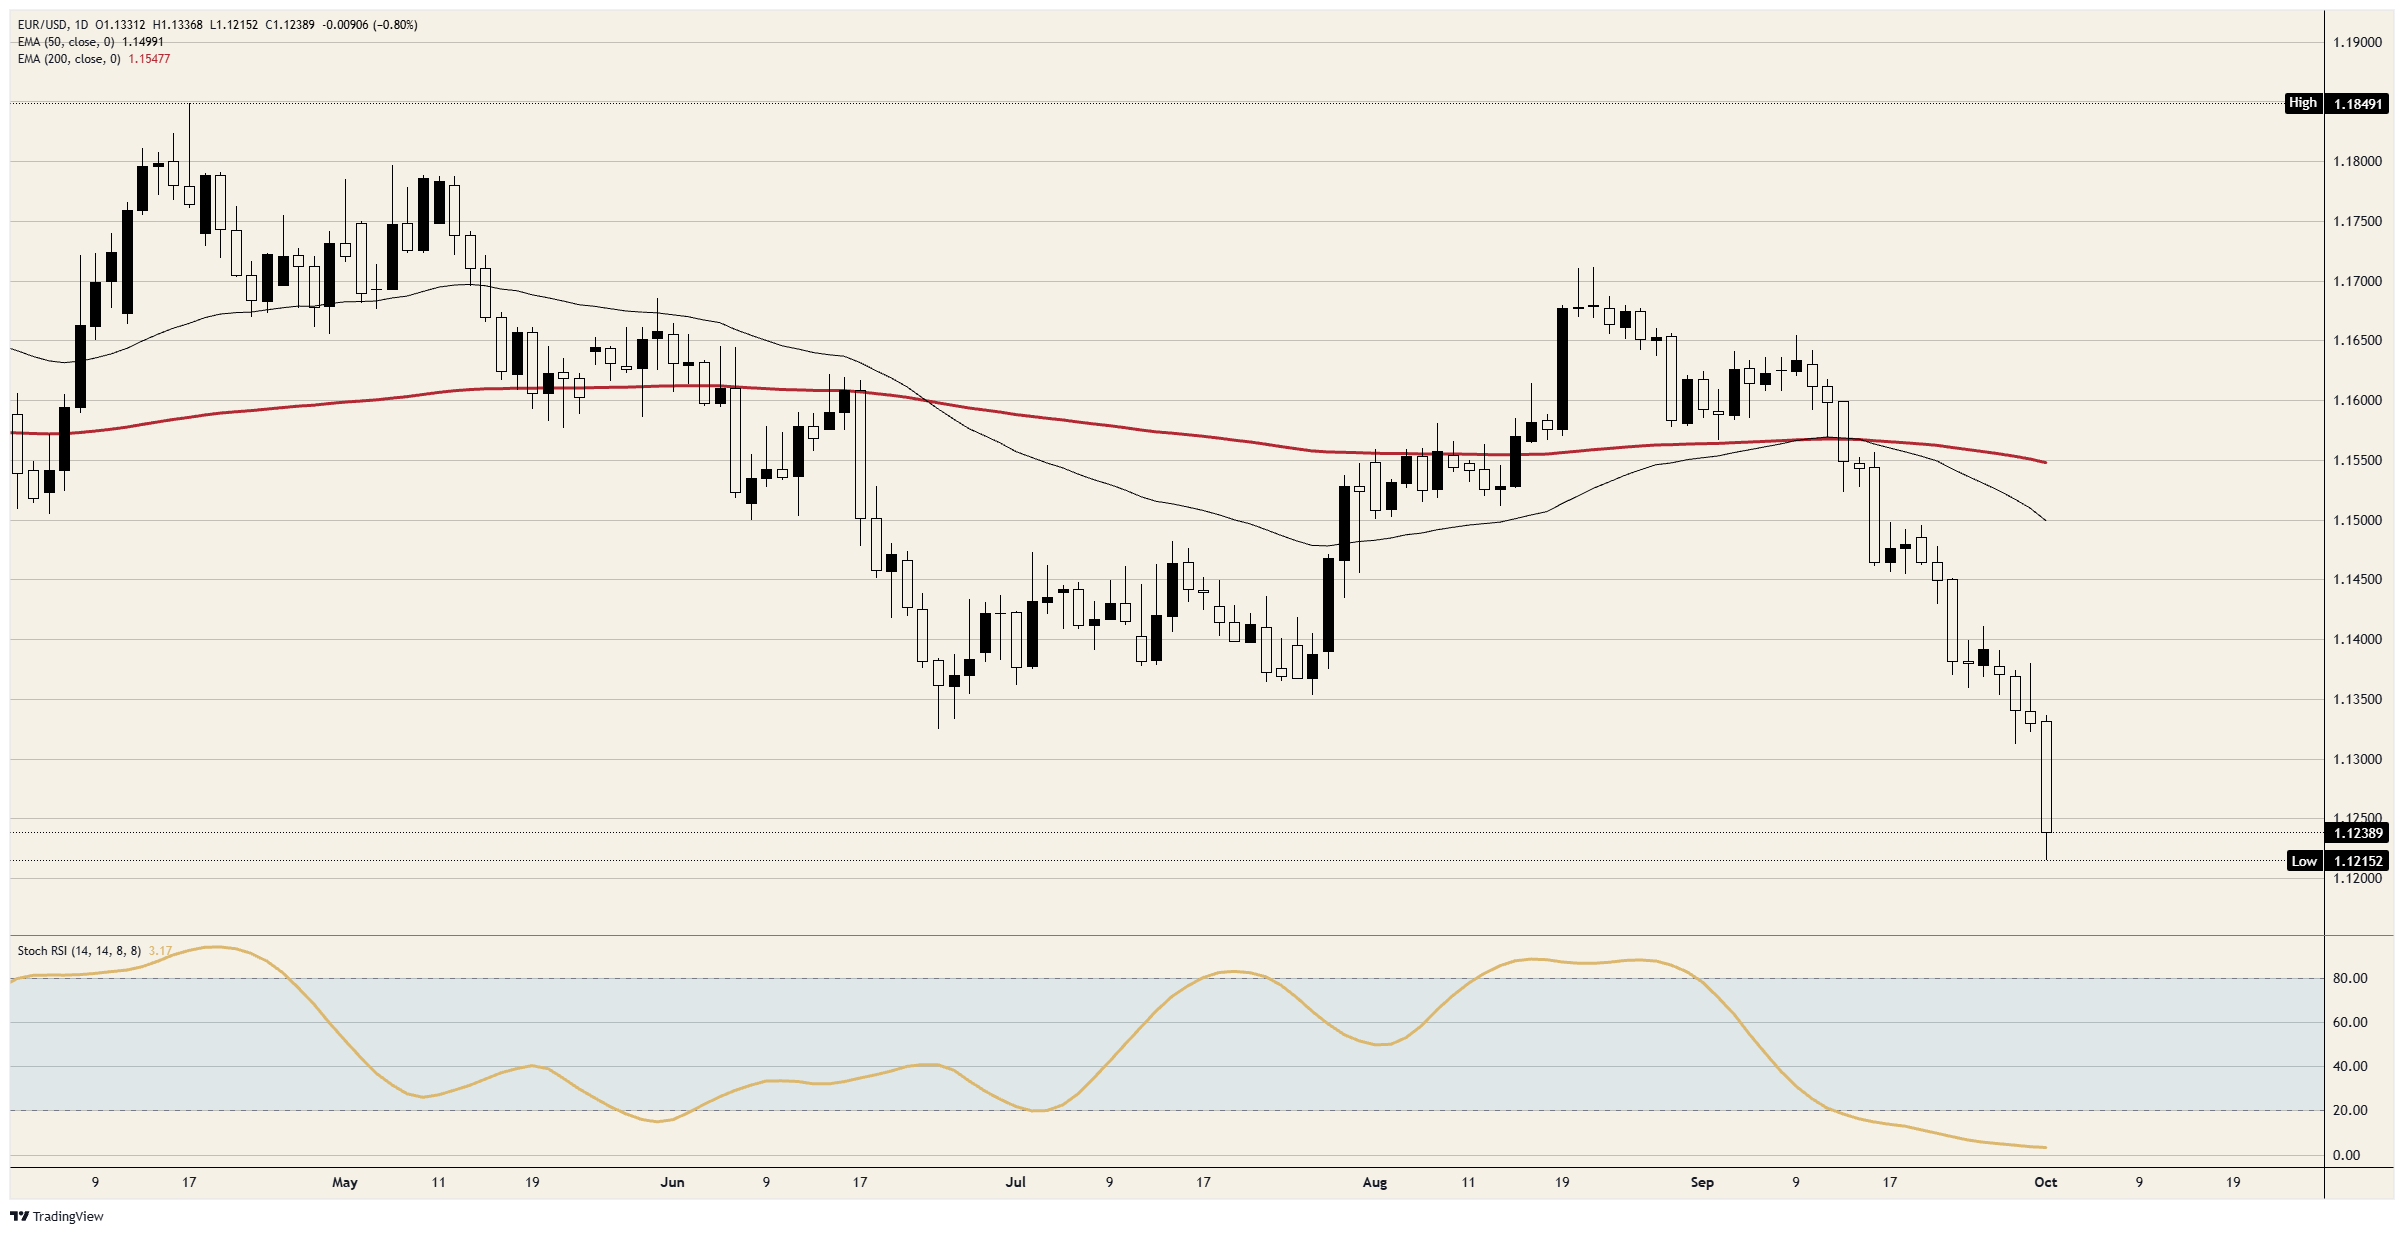
France unveiled a 2027 budget on Thursday aimed at reassuring the investors who lend it money, and EUR/USD is heading for its biggest one-day loss since June 17. Those investors already charge France 130 basis points more than Germany to borrow for ten years, the widest gap since 2012. Prime Minister Lecornu's two predecessors both lost their jobs over budgets. EUR/USD trades just under 1.1250 after falling to its lowest since May 2025.
The ECB raised rates twice in 2011 and cut by November as the debt crisis spread
The budget freezes public-sector pay and most pensions to limit the deficit to 5% of Gross Domestic Product (GDP), and France has been running deficits above that. The European Central Bank (ECB) raised its deposit rate to 2.50% on September 10, its second increase this year, and markets are pricing more because inflation is above 3%. Every increase adds to what France pays on new debt.
For EUR/USD, that means an ECB that may stop short of what inflation calls for, against a Fed already at 3.75%-4.00%. The ECB's bond-buying backstop is reserved for selling it judges unwarranted and disorderly, and a premium that widens on a published deficit may not count as either.
A 3.6% inflation forecast against a 2.50% deposit rate
The euro area's flash Harmonised Index of Consumer Prices (HICP) for September is due on Friday at 09:00 GMT, forecast at 3.6% YoY from 3.2%, with the core rate forecast at 2.5% from 2.4%. ECB Executive Board member Cipollone speaks before the release and ECB Vice-President Vujčić after it. US payrolls follow at 12:30 GMT.
A hot reading could raise the odds of an ECB hike on October 29 and, with them, the cost of that hike to France. Germany, France, Italy and Spain reported their September figures on Wednesday, all above forecast, so most of Friday's number is already known.
The Euro's levels below 1.1300
Resistance: 1.1300 gave way on Thursday, a first since May 2025, and the bounce that followed stalled just above it. Thursday's high, short of 1.1350, came before the selling started.
Support: 1.1200 sits just under Thursday's low, the lowest since May 2025. 1.1150 is the next round level beneath it.
Bias: Short below 1.1300 on a daily closing basis, looking for 1.1200 first and 1.1150 second. The daily Stochastic Relative Strength Index (Stoch RSI) reads near 3, close to the floor of its range, so a rebound toward 1.1300 on Friday's two releases would sit inside the call. A daily close back above 1.1350 makes it wrong.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.