The Australian Dollar goes seven weeks without a central bank
- AUD/USD trades just above 0.7050, its highest since early June.
- The RBA held at 4.35% unanimously and does not meet again until September 29.
- The Fed decides September 16, thirteen days ahead of Australia's board.
AUD/USD trades just above 0.7050 on Tuesday August 11, a tenth of a percent firmer inside a 29-pip range, having taken the Reserve Bank of Australia (RBA) decision entirely in its stride. The board left the cash rate at 4.35% on a unanimous vote and published fresh quarterly forecasts alongside it, the fifth decision of the year, and the currency barely acknowledged any of it.
The flat reaction is the least interesting thing about the day. What matters is the gap that opens behind the decision, because the next Australian meeting is seven weeks out and the next American one is not.
Seven weeks with the microphone off
The RBA does not sit again until September 29. The Fed decides on September 16, thirteen days earlier, and the American calendar fills the interval with Consumer Price Index (CPI) and Producer Price Index (PPI) prints, retail sales, the July meeting minutes on August 19 and the Jackson Hole symposium from August 27-29. Every scheduled event capable of repricing this rate over the next seven weeks sits on one side of it.
Australia's own contributions across the same stretch are thin. Consumer inflation expectations arrive Thursday August 13 at 01:00 GMT against a 4.7% prior, the Governor speaks at 23:30 GMT the same day, and the monthly CPI lands August 26. None of that carries a decision behind it, which leaves the Aussie trading the Dollar leg almost exclusively until the last week of September.
A hold that forecasts its own failure
The vote was unanimous and the projections behind it were not comfortable reading. The board expects inflation to return to around the midpoint of its target band only in late 2027, with the risks around that path skewed higher, and it sees unemployment drifting from 4.5% at the end of this year toward 4.8% by the end of 2028. A bank projecting more than a year of above-target inflation is waiting for a reason, not out of them.
The press conference was firmer than the statement. The board discussed an increase and never discussed a cut, policy was characterised as restrictive and tight, and the Governor repeated that the cash rate can go higher if required. Three increases already delivered this year was offered as the reason for patience, not as the reason for stopping, and the recent surge in Crude Oil was named directly as the channel through which more firms now intend to pass costs to consumers.
The same barrel sits in both reaction functions
Australia imports its energy shock and America partly exports one, so the war keeping Crude Oil bid argues for tightening on both sides of this rate. The RBA has now put that in writing. Futures price the September Fed meeting as a coin flip on the same logic, a fraction over half for a hold against a fraction under half for a quarter-point increase.
That symmetry is what makes the seven-week gap dangerous rather than dull. Both banks are levered to one headline, only one of them can answer it inside the interval, and the one that can is the Fed. An escalation between now and September 16 therefore reads Dollar-positive through the reaction function even where it is Australian-inflationary through the economics, which is the trap in owning the Aussie for its carry right now.
The gap the calendar has to fill
American CPI opens the sequence on Wednesday August 12 at 12:30 GMT, headline seen at 0.1% MoM against a -0.4% prior and 3.4% YoY from 3.5%, core at 0.2% MoM from zero and 2.5% YoY from 2.6%. A hot core reading revives the September increase and takes this rate lower. A soft one leaves the Aussie holding a yield spread it did not have to earn and cannot defend until the last Tuesday of September.
Thursday August 13 brings Australian consumer inflation expectations at 01:00 GMT, then American PPI and jobless claims at 12:30, seen at 0.2% MoM from -0.3% and 4.9% YoY from 5.5% against a 202K claims consensus, with two regional Fed presidents speaking either side of the release. Retail sales and preliminary Michigan sentiment on Friday August 14 round out a week in which the entire Australian contribution is a survey and a speech.
Technical outlook
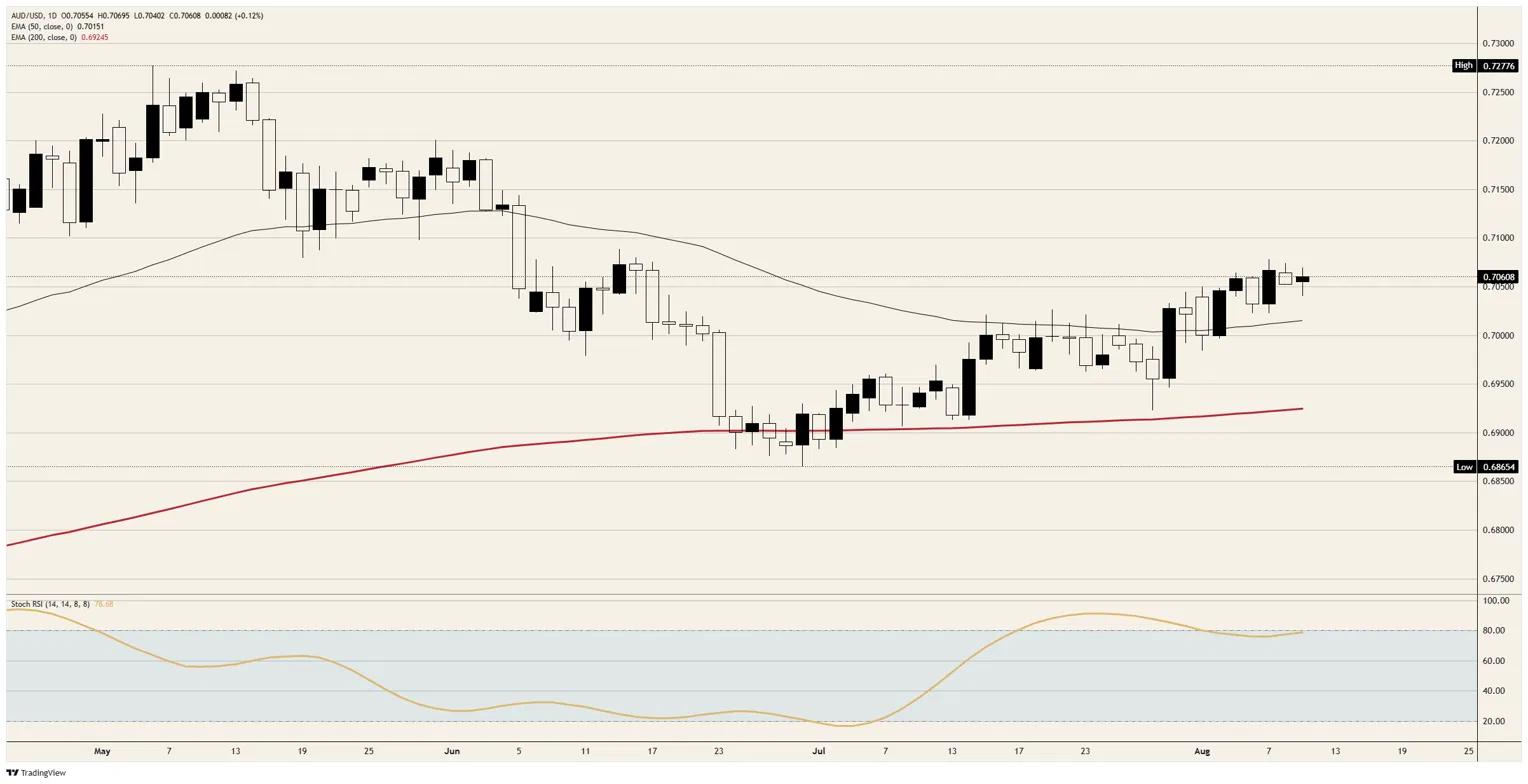
Resistance: 0.7100 is the first line, with the early-June shelf near 0.7150 above it and the May peak just short of 0.7300 the longer objective.
Support: The 50-day Exponential Moving Average (EMA) just above 0.7000 is the reclaimed floor, then 0.6950, with the rising 200-day EMA just beneath that level.
Bias: Bullish while the 50-day EMA holds. A daily Stochastic Relative Strength Index (Stoch RSI) near 79 caps the pace rather than the direction, so this is a grind toward 0.7100 rather than a run at it. A daily close beneath 0.7000 invalidates the call and puts 0.6950 back in play.
AUD/USD daily chart
Australian Dollar FAQs
One of the most significant factors for the Australian Dollar (AUD) is the level of interest rates set by the Reserve Bank of Australia (RBA). Because Australia is a resource-rich country another key driver is the price of its biggest export, Iron Ore. The health of the Chinese economy, its largest trading partner, is a factor, as well as inflation in Australia, its growth rate and Trade Balance. Market sentiment – whether investors are taking on more risky assets (risk-on) or seeking safe-havens (risk-off) – is also a factor, with risk-on positive for AUD.
The Reserve Bank of Australia (RBA) influences the Australian Dollar (AUD) by setting the level of interest rates that Australian banks can lend to each other. This influences the level of interest rates in the economy as a whole. The main goal of the RBA is to maintain a stable inflation rate of 2-3% by adjusting interest rates up or down. Relatively high interest rates compared to other major central banks support the AUD, and the opposite for relatively low. The RBA can also use quantitative easing and tightening to influence credit conditions, with the former AUD-negative and the latter AUD-positive.
China is Australia’s largest trading partner so the health of the Chinese economy is a major influence on the value of the Australian Dollar (AUD). When the Chinese economy is doing well it purchases more raw materials, goods and services from Australia, lifting demand for the AUD, and pushing up its value. The opposite is the case when the Chinese economy is not growing as fast as expected. Positive or negative surprises in Chinese growth data, therefore, often have a direct impact on the Australian Dollar and its pairs.
Iron Ore is Australia’s largest export, accounting for $118 billion a year according to data from 2021, with China as its primary destination. The price of Iron Ore, therefore, can be a driver of the Australian Dollar. Generally, if the price of Iron Ore rises, AUD also goes up, as aggregate demand for the currency increases. The opposite is the case if the price of Iron Ore falls. Higher Iron Ore prices also tend to result in a greater likelihood of a positive Trade Balance for Australia, which is also positive of the AUD.
The Trade Balance, which is the difference between what a country earns from its exports versus what it pays for its imports, is another factor that can influence the value of the Australian Dollar. If Australia produces highly sought after exports, then its currency will gain in value purely from the surplus demand created from foreign buyers seeking to purchase its exports versus what it spends to purchase imports. Therefore, a positive net Trade Balance strengthens the AUD, with the opposite effect if the Trade Balance is negative.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















