Pound Sterling edges higher as the BoE's deputy governors lean toward a hike
- GBP/USD edges back above 1.3250 as a third BoE deputy governor leans toward a hike.
- Three switches would turn the September 6-3 hold into a 6-3 vote to hike.
- UK second-quarter GDP final estimate on Wednesday, forecast at 0.4% QoQ.
The Bank of England (BoE) held the UK's Bank Rate at 3.75% on September 17 by six votes to three, and half of the six who voted to hold now say a hike may be needed. BoE Deputy Governor Ramsden said in London on Monday that there could be a case for raising the Bank Rate if upside pressure on the inflation outlook keeps building, after Deputy Governors Breeden and Lombardelli made the same argument on Thursday. GBP/USD closed just above 1.3250 for a second straight gain.
The same count could point the other way
Chief Economist Pill and external members Greene and Mann voted for 4% on September 17. If Ramsden, Breeden and Lombardelli join them in November, the committee would hike by the same six votes to three it used to hold, and BoE Governor Bailey and external members Dhingra and Taylor would be the ones outvoted. All three deputies point to the same risk, that energy prices feed into wage bargaining and price-setting.
The ECB and the Fed have both raised rates since the Iran war began on February 28, and the BoE hasn't. It has held at 3.75% at every meeting this year, arguing its policy was already restrictive, while the ECB went up twice and the Fed once. Ramsden also said markets took the BoE's multi-year plan for selling its gilt holdings well, which has nudged UK borrowing costs slightly lower.
Sterling barely reacted to the speech, and there's a reason. Ramsden's case for a hike repeated what he had already set out in the minutes of the meeting at which he voted against one. The Pound needs UK rates to rise faster than US rates to recover, and the Fed decides on October 28, with a range of 3.75%-4.00% and futures leaning toward another quarter-point.
Taylor is the hold voter to watch before payrolls
External member Taylor speaks on Tuesday at 15:30 GMT, and he is the only one of the six September holders scheduled to speak before Friday. Britain's final second-quarter Gross Domestic Product (GDP) estimate follows on Wednesday at 06:00 GMT, forecast at 0.4% QoQ and 1.2% YoY, both unchanged. External member Mann, who has voted to hike at the last two meetings, speaks on Thursday at 12:00 GMT.
The US side carries more weight for GBP/USD. Wednesday's core Personal Consumption Expenditures (PCE) price index is forecast at 3.4% YoY, and Friday's Nonfarm Payrolls (NFP) report at 84K after 162K in August. Those numbers set the odds of an October Fed move, and the BoE doesn't meet until November 5, so a payroll miss would do more for the Pound before November than anything a BoE speaker can say.
The map into Taylor and the UK GDP number
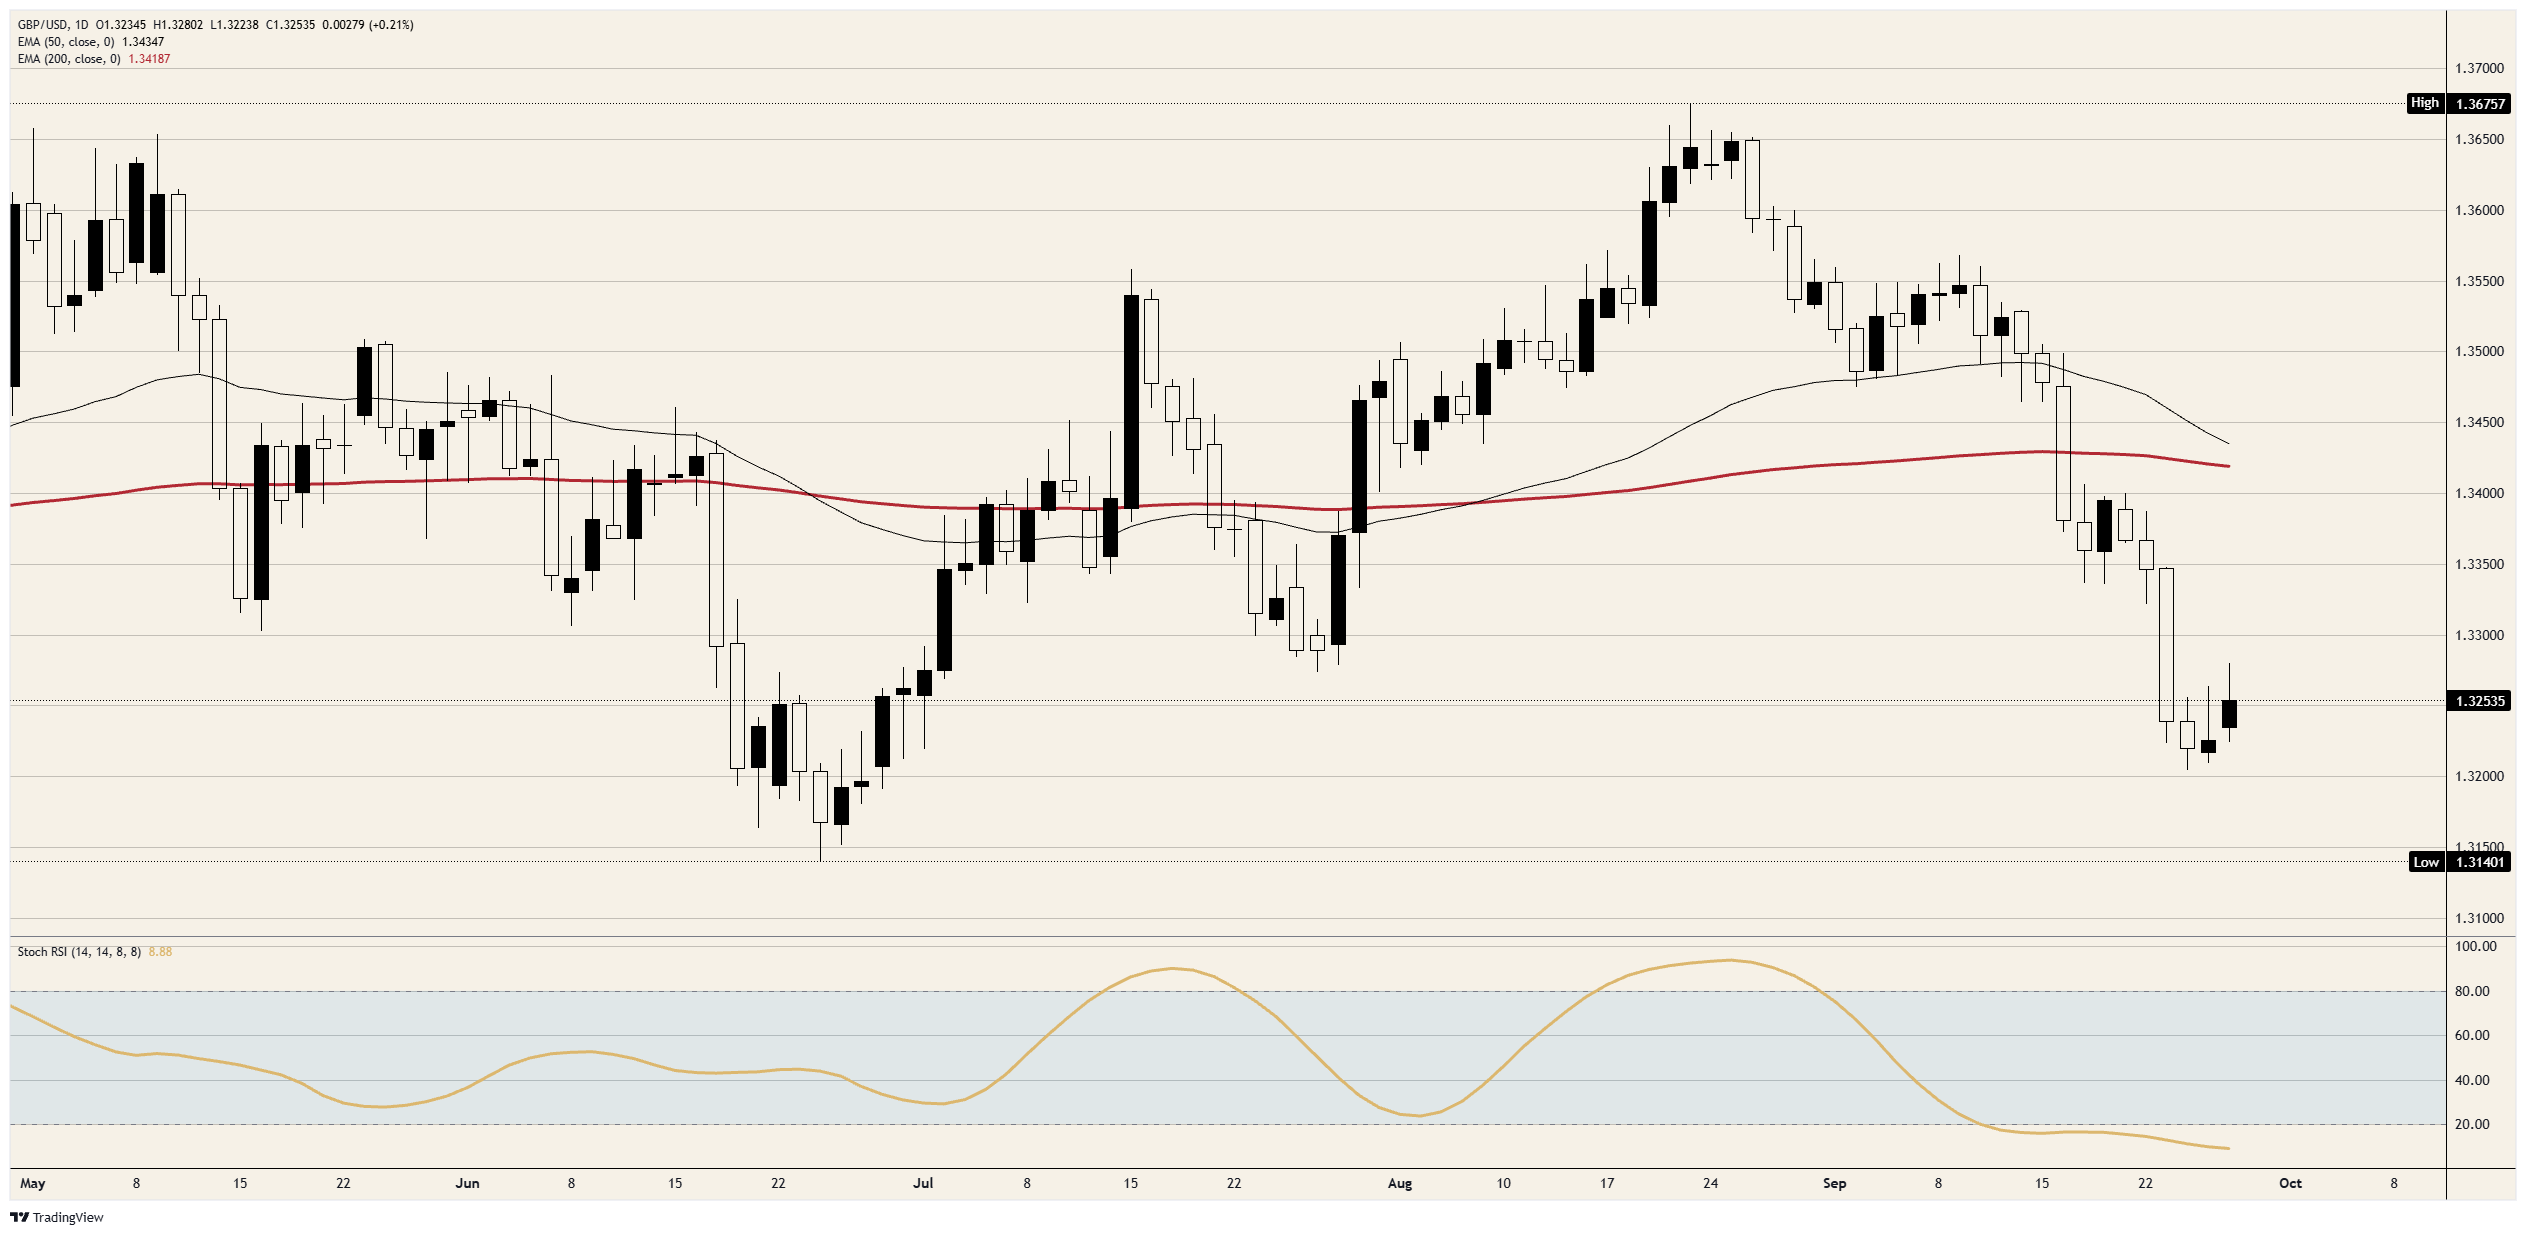
Resistance: Monday's high stopped short of 1.3300, the level GBP/USD went through on September 23, the largest down day of the slide. Above that, 1.3350 is where that session opened.
Support: 1.3200 held Thursday's low, the weakest level since late June. A break there leaves the late-June low just under 1.3150 as the only level left before 1.3100.
Bias: Short while 1.3300 caps, with 1.3200 the first objective and the late-June low near 1.3150 the second. The daily Stochastic Relative Strength Index (Stoch RSI) has dropped to around 9, its lowest since the slide began, which leaves room for a squeeze toward 1.3300 ahead of the next drop. A daily close above 1.3350 invalidates the call.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















