New Zealand's Kiwi prices a hike it has already delivered
- NZD/USD holds just beneath 0.5950, unchanged on a 22-pip range.
- The RBNZ decision Wednesday carries a 2.75% consensus from 2.50%.
- Consumer confidence prints at 22:00 GMT against a 99.3 prior.
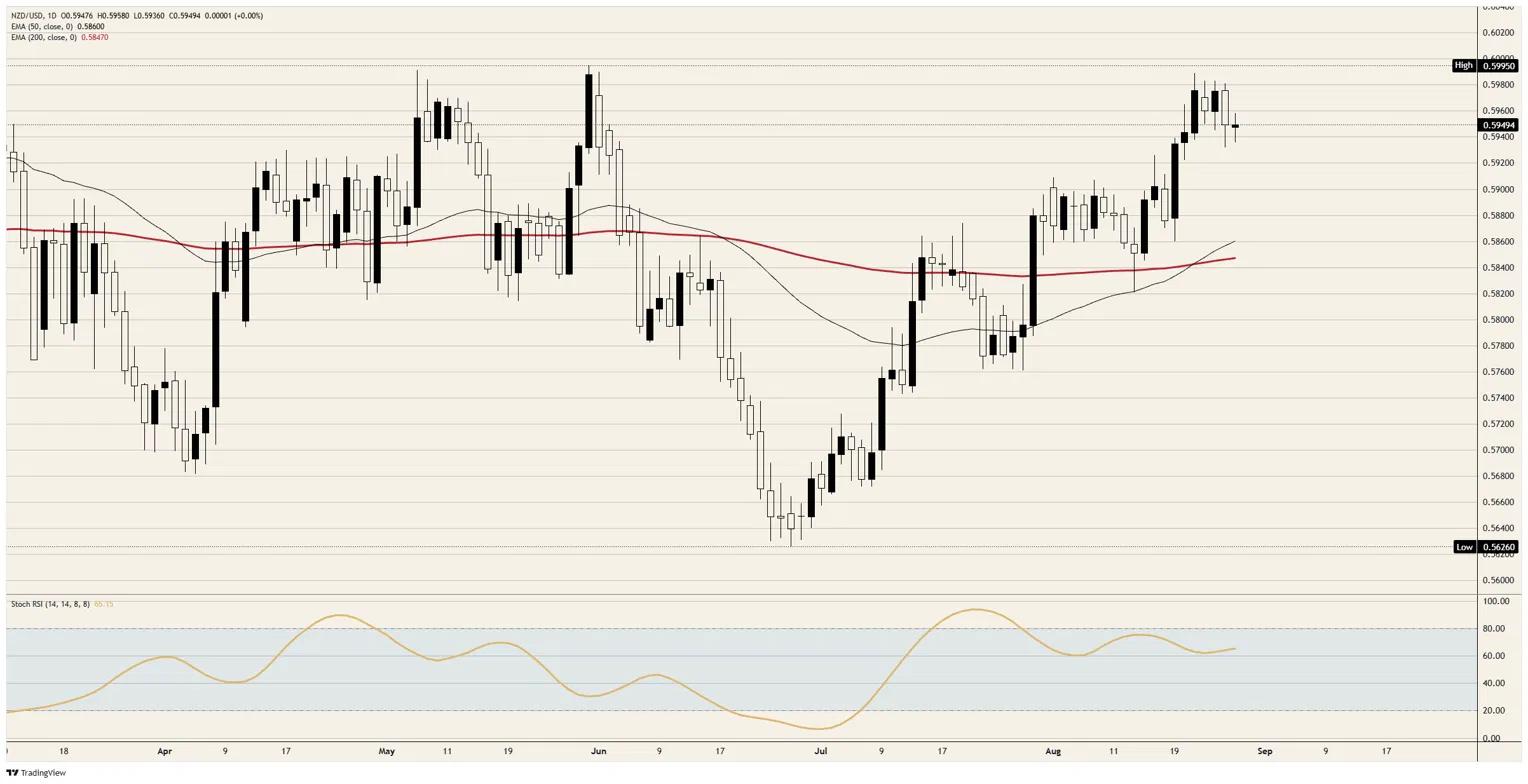
NZD/USD holds just beneath 0.5950 on Thursday, unchanged on the session across a range of twenty-two pips and some forty-five pips under the window high just short of 0.6000 set in early June. The pair sits close to ninety pips above a rising 50-day Exponential Moving Average (EMA) near 0.5850, with the 200-day a shade beneath that, and the daily Stochastic Relative Strength Index (Stoch RSI) near 65 with room above it.
The currency did the job the hike was for
The Reserve Bank of New Zealand raised the Official Cash Rate a quarter point to 2.50% on July 8, its first increase since 2023, and gave two reasons for it. The first was that 2.25% sat somewhat beneath neutral, so the move removed stimulus rather than applied restraint. The second was that standing still risked letting financial conditions loosen further, named explicitly as a softer currency or lower rate expectations.
The Kiwi has since climbed close to 5.7% from its early-July low just above 0.5600 and now trades within touching distance of its high for the window. A currency that strong tightens financial conditions without help, which retires the second of those two reasons before the September meeting arrives. Wednesday's consensus 2.75% would in any case leave the rate inside the Reserve Bank's own 2.50% to 3.50% neutral uncertainty band, so a second increase buys less accommodation rather than actual restraint.
Not all of the rally is the Dollar leaving, but most of it is. The Kiwi has added roughly 2.6% since the last days of July, when it traded near 0.5800, while the Dollar Index has lost roughly 2.3% across the identical stretch. That leaves something like a third of a percentage point that belongs to New Zealand rather than to Washington, and that fraction is the whole of what Wednesday has to justify.
The domestic case has been thinning
Headline inflation is now expected to have peaked at 3.9% in the June quarter and to fall to 3.3% in the September quarter. Surveys of households, businesses and professional forecasters all recorded lower inflation expectations in the September quarter, back to roughly where they sat before the oil spike. That is the entire case for a second increase moving in the wrong direction.
The activity side offers no more help. House prices ran 0.4% lower on the year in May, residential investment contracted in the March quarter despite strong consent growth, and the central bank's own nowcast for September-quarter growth sits at 0.6%. A committee that needed a casting vote to hold in May and then reached July's increase by consensus arrives at September with the data pointing away from the number the market has already paid for. Most major New Zealand banks still carry the rate near 3.00% by year-end on two more quarter-point moves, and the May projections implied a peak around 3.3%, so the distance between a fully priced Wednesday and a disappointed one runs through the track rather than the decision.
Sixty hours of its own story, then payrolls
The immediate mark is Thursday at 22:00 GMT, when consumer confidence prints against a prior of 99.3, beneath the hundred line separating net optimism from net pessimism. Building permits follow Tuesday at 22:45 GMT with a prior of minus 3.6%. The decision lands Wednesday at 02:00 GMT with the Monetary Policy Statement and policy review attached and a press conference an hour behind it, and the projected rate track rather than the number itself is the event.
Then the pair hands itself back. The US block runs the manufacturing survey Tuesday at 14:00 GMT with a 55.3 consensus from 55.6, the private payrolls estimate Wednesday at 12:15 GMT from 44K, the Beige Book that same evening at 18:00 GMT sixteen hours behind Wellington, the services survey Thursday from 54.1, and August payrolls Friday at 12:30 GMT with the prior at minus 23K and unemployment 4.1%. The Kiwi gets roughly sixty hours to trade its own story before a US labour print that last came in negative decides the rest of it.
Levels
Resistance: Just short of 0.6000 is the window high and the first line, with the 0.6000 handle immediately above it and little marked beyond.
Support: 0.5900 is the near shelf, then the moving-average band around 0.5850 where the 50-day and 200-day EMAs sit within fifteen pips of each other, with 0.5800 beneath that.
Bias: Bullish while 0.5900 holds, capped at 0.6000. The trend is clean with price above both rising averages and momentum unstretched, but the increase is already in the price, so the break needs the projected track rather than the decision. Invalidation on a daily close beneath 0.5850.
NZD/USD daily chart
New Zealand Dollar FAQs
The New Zealand Dollar (NZD), also known as the Kiwi, is a well-known traded currency among investors. Its value is broadly determined by the health of the New Zealand economy and the country’s central bank policy. Still, there are some unique particularities that also can make NZD move. The performance of the Chinese economy tends to move the Kiwi because China is New Zealand’s biggest trading partner. Bad news for the Chinese economy likely means less New Zealand exports to the country, hitting the economy and thus its currency. Another factor moving NZD is dairy prices as the dairy industry is New Zealand’s main export. High dairy prices boost export income, contributing positively to the economy and thus to the NZD.
The Reserve Bank of New Zealand (RBNZ) aims to achieve and maintain an inflation rate between 1% and 3% over the medium term, with a focus to keep it near the 2% mid-point. To this end, the bank sets an appropriate level of interest rates. When inflation is too high, the RBNZ will increase interest rates to cool the economy, but the move will also make bond yields higher, increasing investors’ appeal to invest in the country and thus boosting NZD. On the contrary, lower interest rates tend to weaken NZD. The so-called rate differential, or how rates in New Zealand are or are expected to be compared to the ones set by the US Federal Reserve, can also play a key role in moving the NZD/USD pair.
Macroeconomic data releases in New Zealand are key to assess the state of the economy and can impact the New Zealand Dollar’s (NZD) valuation. A strong economy, based on high economic growth, low unemployment and high confidence is good for NZD. High economic growth attracts foreign investment and may encourage the Reserve Bank of New Zealand to increase interest rates, if this economic strength comes together with elevated inflation. Conversely, if economic data is weak, NZD is likely to depreciate.
The New Zealand Dollar (NZD) tends to strengthen during risk-on periods, or when investors perceive that broader market risks are low and are optimistic about growth. This tends to lead to a more favorable outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Conversely, NZD tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.