Euro slips back to its summer low as ECB President Lagarde urges measured hikes
- EUR/USD slips to 1.1350, level with its late-July low, as the ECB counsels measured hikes.
- Eurozone flash HICP forecast to jump to 3.6% YoY on Friday from 3.2%.
- ECB deposit rate at 2.50%, with the next decision on October 29.
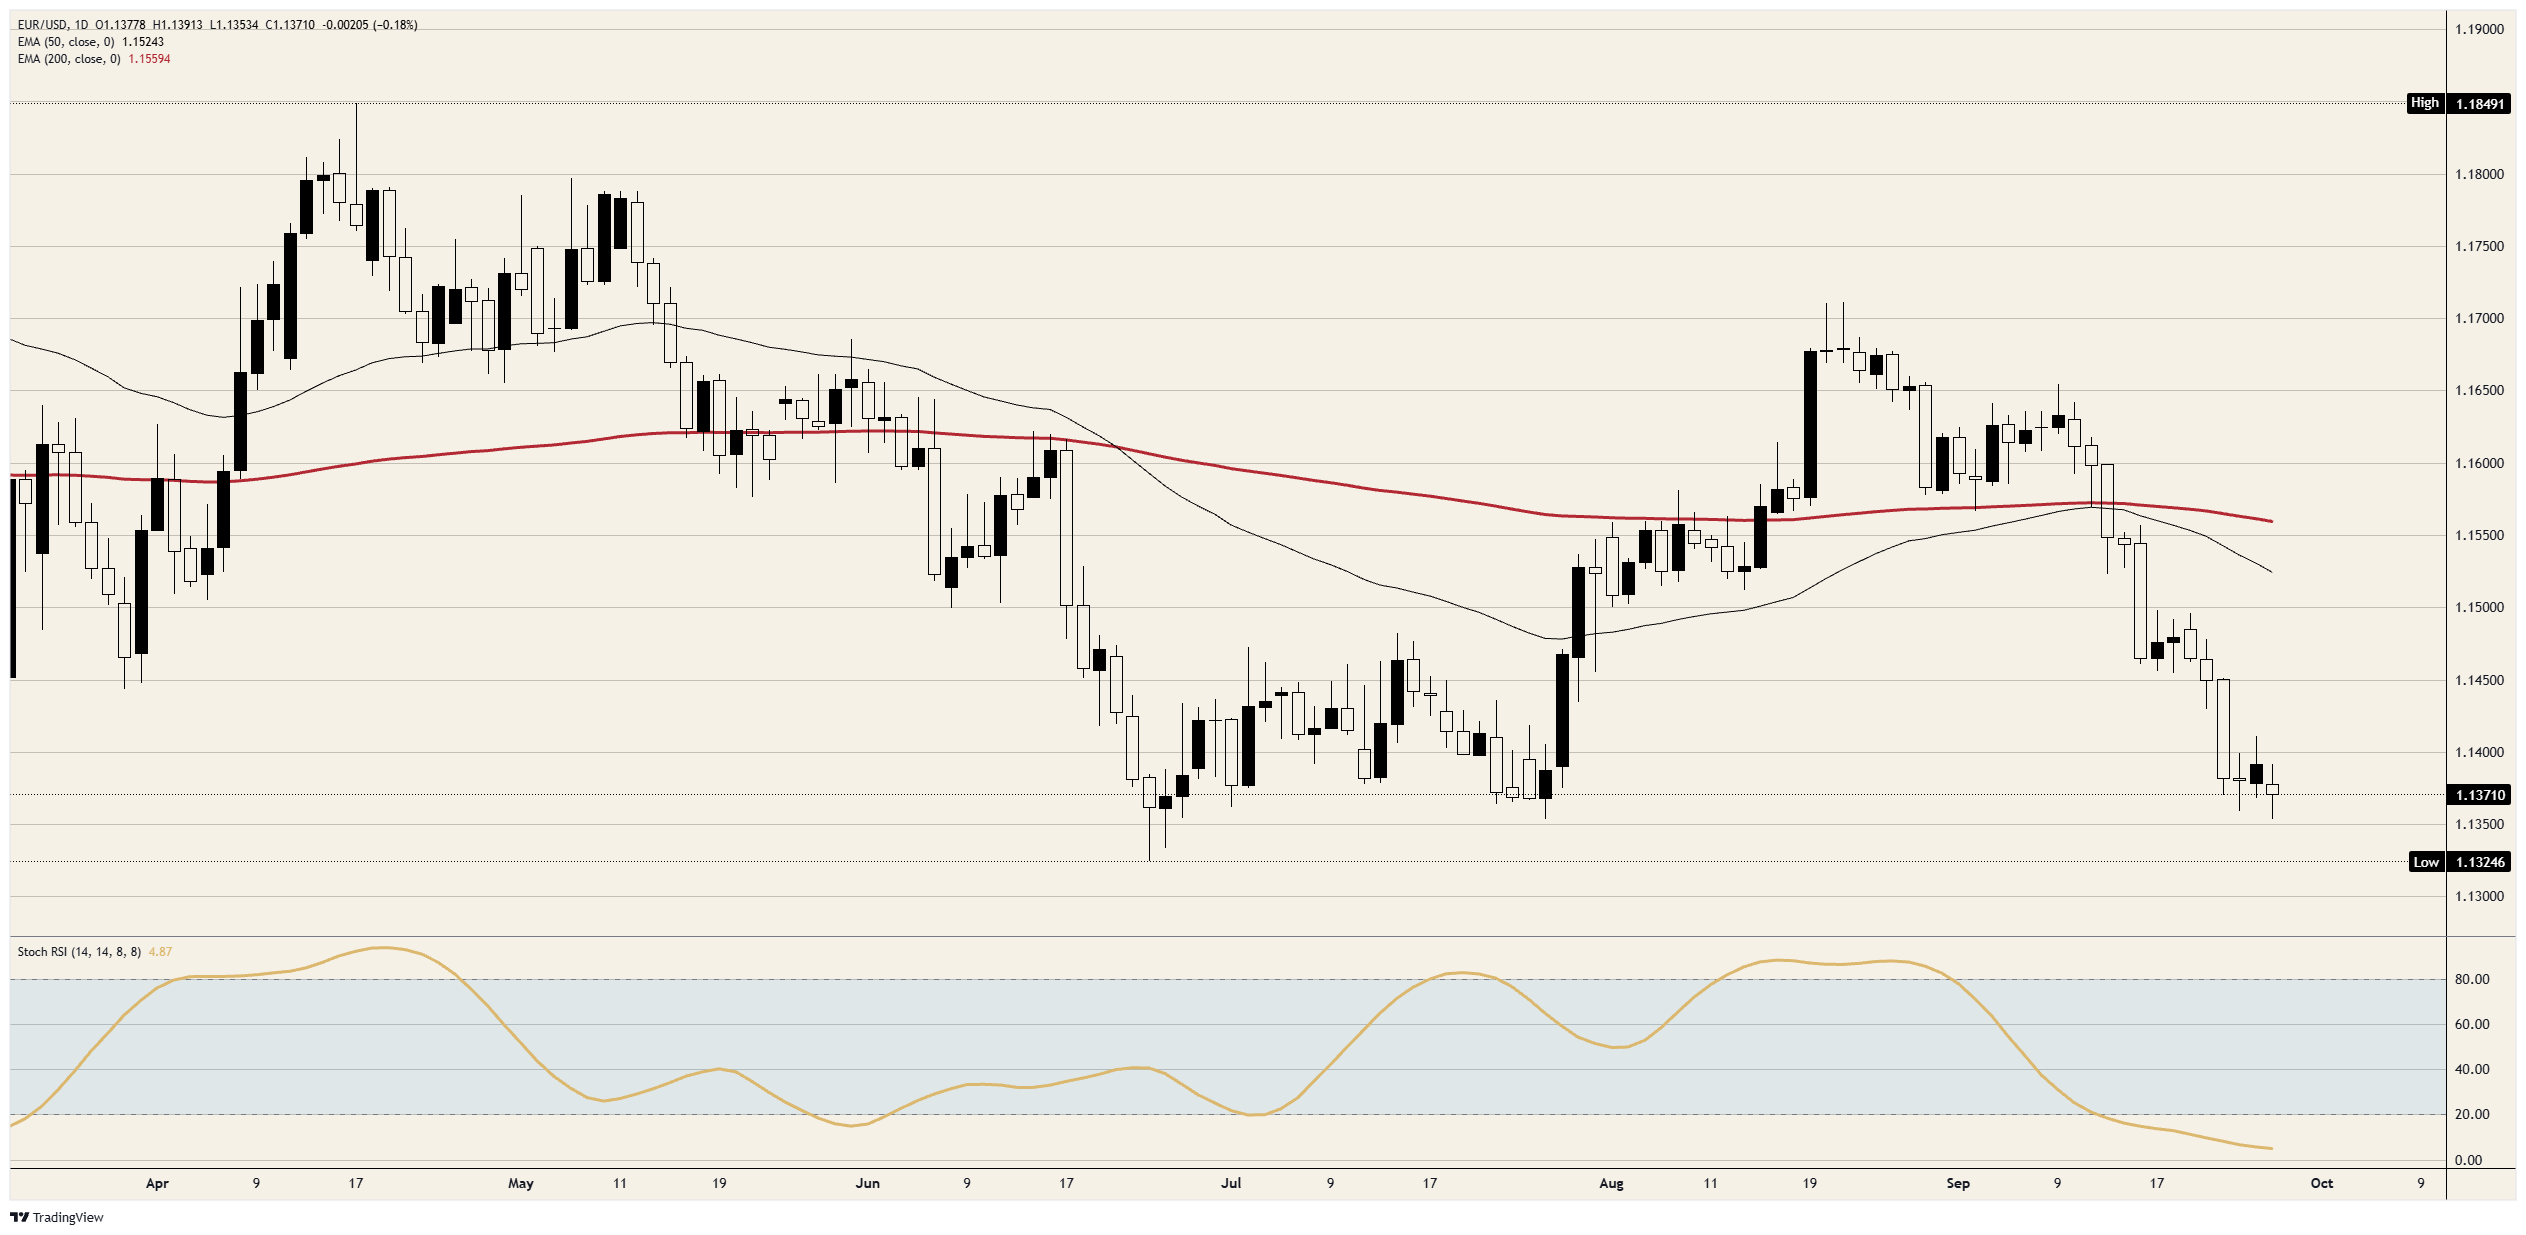
Traders betting on a faster European Central Bank (ECB) got pushback from ECB President Lagarde on Monday, and EUR/USD fell back to its late-July low near 1.1350. The pair closed just above 1.1350, three sessions after it broke below 1.1400. Lagarde told a European Parliament committee that the energy shock is too large to look through, but that a measured response remains appropriate because there's no sign yet of energy costs feeding into wages. Eurozone inflation was 3.2% in August, with energy prices up 14.3% YoY, and the ECB's September staff projections have it averaging 3.0% this year and 2.5% in 2027.
Lagarde counted the bond market as part of the tightening
Lagarde also said long-term interest rates have climbed since the ECB's September meeting, which will slow growth and cut the pass-through of energy costs by more than the ECB projected. Higher yields in Europe usually help the Euro, but she presented them as work the ECB no longer has to do itself. Traders heard fewer ECB hikes, and a smaller rate lift for the Euro against a Dollar backed by the Fed's 3.75%-4.00%.
The ECB raised its deposit rate to 2.50% on September 10, its second increase this year, and futures priced about a 60% chance of another on October 29 as of September 24. The October decision lands the day after the Fed's, so the ECB will vote knowing whether the gap to US rates has just widened again. Wednesday's Governing Council meeting is a non-monetary one, with no rate decision on the agenda.
Fifteen ECB speeches come before one inflation number
Lagarde speaks again on Tuesday at 11:00 GMT and on Thursday at 13:30 GMT, and 13 more ECB speeches are scheduled before Friday's flash Harmonised Index of Consumer Prices (HICP) for September at 09:00 GMT. Headline inflation is forecast at 3.6% YoY, up from 3.2%, and the core reading, which strips out energy, food, alcohol and tobacco, at 2.5% from 2.4%. The core figure is the one closer to the second-round effects Lagarde said the ECB hasn't seen yet, so a 2.5% or higher reading would test the measured line before October 29.
On the US side, core Personal Consumption Expenditures (PCE) inflation lands on Wednesday, forecast at 3.4% YoY, and September payrolls follow on Friday at 12:30 GMT, three and a half hours after the eurozone inflation number. EUR/USD gets both halves of the rate question on the same day.
Where the pair stands into Friday's inflation reading
Resistance: Friday's high just above 1.1400 is as far as any bounce has reached since the September 23 break. Above that, 1.1450 is the level that gave way that day.
Support: 1.1350 held on Monday and in late July. Under that, the late-June low near 1.1300 marks the bottom of the summer range.
Bias: Short below 1.1400, looking for a daily close under 1.1350 first and 1.1300 after that. The daily Stochastic Relative Strength Index (Stoch RSI) reads about 5 and has held under 20 since mid-September, which argues for a bounce before a break. A daily close above 1.1450 would end the short.
EUR/USD daily chart
Euro FAQs
The Euro is the currency for the 20 European Union countries that belong to the Eurozone. It is the second most heavily traded currency in the world behind the US Dollar. In 2022, it accounted for 31% of all foreign exchange transactions, with an average daily turnover of over $2.2 trillion a day. EUR/USD is the most heavily traded currency pair in the world, accounting for an estimated 30% off all transactions, followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
The European Central Bank (ECB) in Frankfurt, Germany, is the reserve bank for the Eurozone. The ECB sets interest rates and manages monetary policy. The ECB’s primary mandate is to maintain price stability, which means either controlling inflation or stimulating growth. Its primary tool is the raising or lowering of interest rates. Relatively high interest rates – or the expectation of higher rates – will usually benefit the Euro and vice versa. The ECB Governing Council makes monetary policy decisions at meetings held eight times a year. Decisions are made by heads of the Eurozone national banks and six permanent members, including the President of the ECB, Christine Lagarde.
Eurozone inflation data, measured by the Harmonized Index of Consumer Prices (HICP), is an important econometric for the Euro. If inflation rises more than expected, especially if above the ECB’s 2% target, it obliges the ECB to raise interest rates to bring it back under control. Relatively high interest rates compared to its counterparts will usually benefit the Euro, as it makes the region more attractive as a place for global investors to park their money.
Data releases gauge the health of the economy and can impact on the Euro. Indicators such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can all influence the direction of the single currency. A strong economy is good for the Euro. Not only does it attract more foreign investment but it may encourage the ECB to put up interest rates, which will directly strengthen the Euro. Otherwise, if economic data is weak, the Euro is likely to fall. Economic data for the four largest economies in the euro area (Germany, France, Italy and Spain) are especially significant, as they account for 75% of the Eurozone’s economy.
Another significant data release for the Euro is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought after exports then its currency will gain in value purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.