Estimates keep rising as Q3 earnings season takes center stage
The Q3 earnings season takes center stage this week when JPMorgan (JPM), Citigroup (C) , and others report September-quarter results before the market’s open on Tuesday, October 13th. This week’s reporting docket, comprising 29 S&P 500 members, also includes companies outside the Finance sector, with bellwethers like Johnson & Johnson, Taiwan Semiconductor Company, and UnitedHealth also reporting quarterly results.
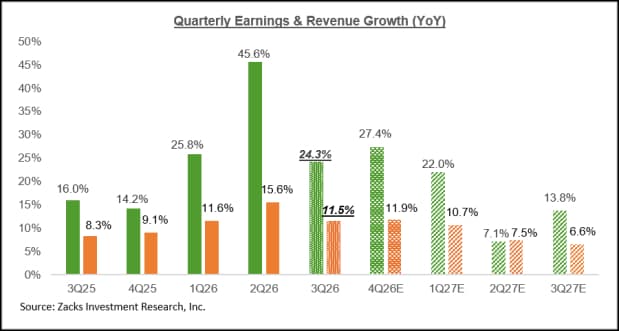
The expectation is that S&P 500 earnings will increase by +24.3% from the same period last year, the 8th straight quarter of double-digit earnings growth for the index.
The Tech sector remains a major growth contributor, but momentum is broad-based, with 15 of the 16 Zacks sectors on track for positive earnings growth in Q3. Importantly, the revisions trend remains positive and broad-based, highlighting a steadily improving outlook.
The quarterly chart below details actual results alongside Q3 2026 growth expectations and forward projections.
As noted earlier, the revisions trend has been positive, sustaining the favorable trend in place for almost a year. Estimates for Q3 increased after the quarter got underway, and we are seeing a similar trend at play for 2026 Q4 estimates, as the chart below shows.
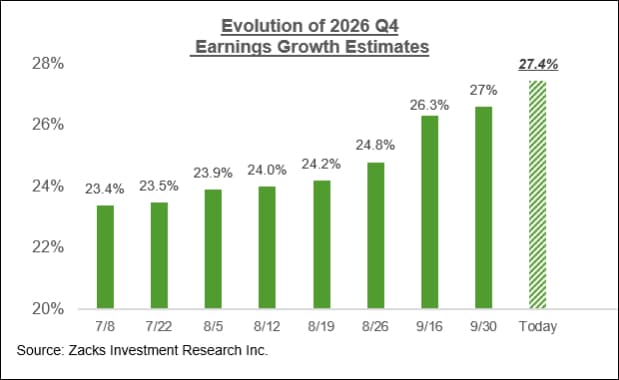
This positive revision behavior is not new; it extends a tailwind that has been building for nearly a year. The positive revisions were at first concentrated in Technology and, more recently, Energy following Middle East supply disruptions. However, for 2026 Q4 and what we saw in Q3, constructive estimate revisions have broadened significantly, rising across 7 of the 16 Zacks sectors—including Aerospace, Construction, Industrials, Finance, and Transportation alongside Tech and Energy.
On the negative side, Q4 estimates remain under pressure for these 8 sectors – Conglomerates, Autos, Basic Materials, Consumer Staples, Consumer Discretionary, Medical, Business Services, and Retail.
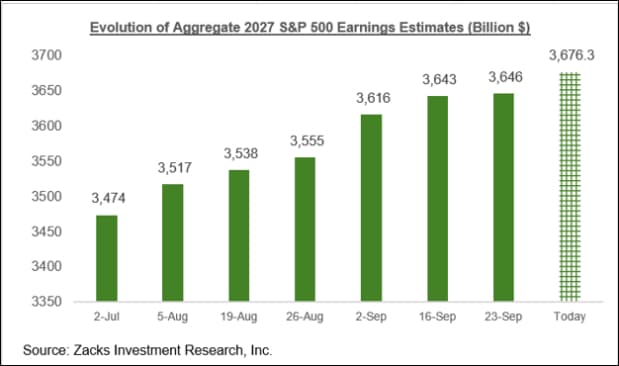
It is important to note that estimates for full-year 2027 have also been similarly trending higher, which we show a little later in this note.
Sector focus: Broad-based strength
Q3 earnings are expected to be above the year-earlier level for 15 of the 16 Zacks sectors, with 6 sectors expected to enjoy double-digit growth. The multi-industry Conglomerates sector is the only one expected to have lower earnings in Q3 relative to the same period last year (earnings decline of –35.1%).
The 6 sectors expected to enjoy double-digit earnings growth in Q3 are Aerospace (up +159.5%), Energy (+117.1%), Tech (+43.3%), Basic Materials (+29.7%), Transportation (+10.9%) and Industrial Products (+13.3%).
Q3 earnings growth for the S&P 500 index drops to +20.1% from +24.3% once the Energy sector’s contribution is excluded from the index. Excluding the Tech sector, Q3 earnings growth for the rest of the index drops to +14.2%.
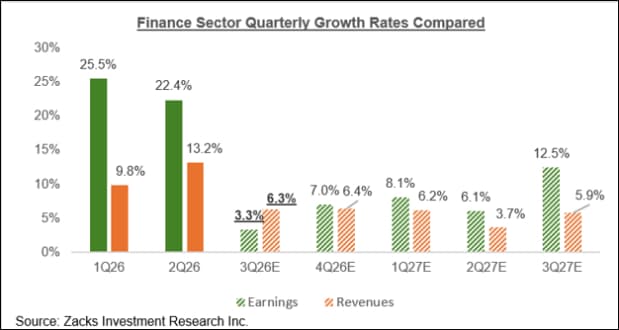
For the Finance sector, which dominates the reporting docket this week, Q3 earnings are expected to be up +3.3% from the same period last year on +6.3% higher revenues, as the chart below shows.
The chart below shows Q3 earnings and revenue growth expectations for the Finance sector relative to the preceding two periods and what is expected over the following four quarters.
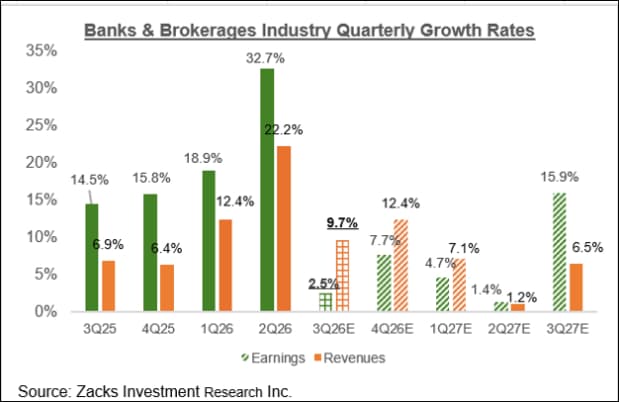
The Banks and Brokerages industry, which includes JPMorgan, Citigroup, Goldman Sachs, and others, is expected to post +2.5% earnings growth in Q3 on +9.7% higher revenues, as the chart below shows.
The sharp rise in long-term Treasury yields during Q3 has been an overhang on bank and broker stocks lately. Rising yields don’t just cause paper losses on balance sheet holdings of available-for-sale bonds, as they also pressure net interest margins through surging deposit betas and have negative effects on credit demand and quality. The unfavorable interest rate backdrop has clouded the outlook for deal flow, with a number of high-profile IPOs getting delayed as a result.
Q3 earnings season scorecard
The Q3 earnings season is not officially getting underway with this week’s results from JPMorgan, Citigroup, and others. Officially, the Q3 reporting cycle began with recent results from Pepsi (PEP), Micron (MU), Nike (NKE), and others.
The Nike, Micron, and other reports were for these companies’ fiscal quarters ending in August, which count as part of the September-quarter tally. Including the Nike and Micron reports, we now have such Q3 results from 19 S&P 500 members. With another 29 index members reporting results this week, including the aforementioned banks, we will have seen results from 48 S&P 500 members by the end of this week.
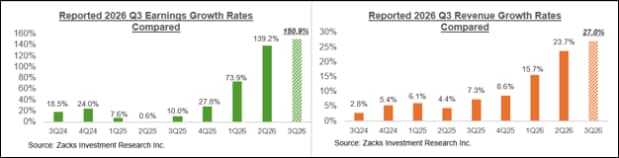
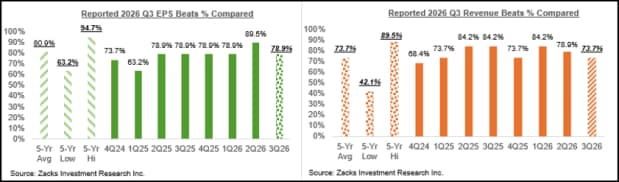
Total Q3 earnings for the 19 S&P 500 members that have reported results already are up +150.9% from the same period last year on +27% higher revenues, with 78.9% beating EPS estimates and 73.7% beating revenue estimates.
The comparison charts below show the earnings and revenue growth rates for these companies compared to other recent periods.
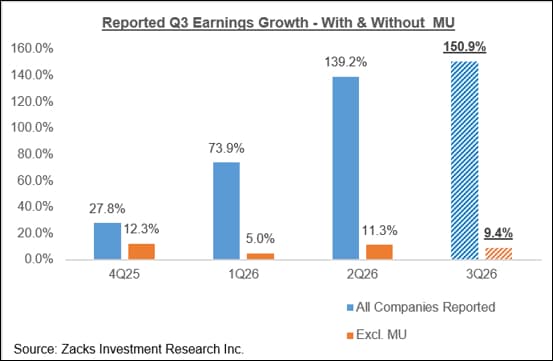
The very strong earnings and revenue growth pace for this group of 19 S&P 500 members is mostly due to Micron, whose Q3 earnings increased +1075.7% from the year-earlier level. Excluding the Micron contribution, Q3 earnings for the remaining 18 index members that have reported would be up +9.4%.
The chart below shows the Q3 earnings growth pace for the companies that have reported, with and without Micron, across recent periods.
The comparison charts below show the Q3 EPS and revenue beats percentages for these companies compared to other recent periods.
The Earnings Big Picture
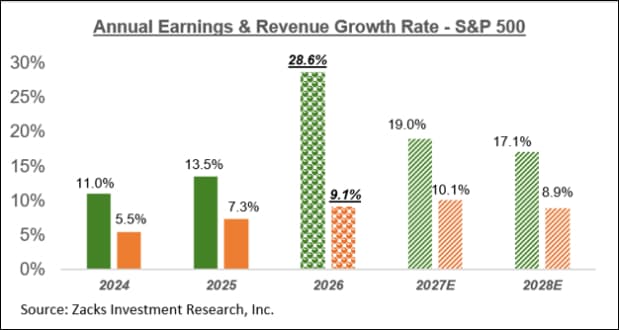
The chart below shows the aggregate growth picture for the S&P 500 index on a calendar year basis.
As we noted earlier, estimates for full-year 2027areexperiencing the same positive revisions trend that we noted earlier in the context of 2026 Q4. The chart below shows how aggregate 2027 earnings estimates have evolved since the start of July.
Want the latest recommendations from Zacks Investment Research? Download 7 Best Stocks for the Next 30 Days. Click to get this free report
Author

Zacks
Zacks Investment Research
Zacks Investment Research provides unbiased investment research and tools to help individuals and institutional investors make confident investing decisions.