British Pound Sterling needs a fourth dissenter
- GBP/USD trades near 1.3500, its highest since mid-July.
- Bank of England dissent has run 8-1, 7-2, then 6-3 since April.
- UK second-quarter GDP is due August 13, consensus 0.4% from 0.6%.
GBP/USD trades near 1.3500 on Tuesday August 11, a shade lower on the session and inside a range of barely 25 pips, with nothing British on the calendar to account for either the level or the calm. The Pound has added roughly two cents since the turn of the month from a base just beneath 1.3300, and it has done so without a single domestic release worth the name.
That gap between the price and the reason for it is what the rest of the week has to resolve. Two of the three releases capable of moving this rate are American, the third is a British growth print that consensus expects to slow, and the only genuinely sterling-positive development of the past six weeks has been a vote count.
The vote count is the live channel
The Bank of England held Bank Rate at 3.75% on July 30 by six votes to three, the minority preferring a quarter point more and framing the majority position as a pause rather than a stop. The hawkish bloc has now grown at three consecutive meetings, from a single dissenter in April to two in June and three in July. That direction of travel has been more reliable this year than any British data series.
One more convert makes the next vote five to four and two takes the decision itself. The committee meets again on September 17, the day after the Fed, repeating the sequencing that produced the July 29 and July 30 double bill six weeks ago. A currency trading a probability rather than a policy reprices on arithmetic, and this arithmetic has been moving one seat per meeting.
The economy those three are dissenting against
The case for a quarter point rests on energy rather than on domestic demand. Britain's June Consumer Price Index (CPI) printed at 2.6% YoY with core at the same rate and services at 3.6%, all cooler than the spring, while the war keeping Crude Oil bid has not gone anywhere. Tehran has ruled out negotiating with this administration before 2029, and Bab al-Mandeb transit remains constrained by the maritime embargo declared against Saudi shipping.
What the dissenters are voting into is a growth picture that keeps stalling. Consensus has second-quarter Gross Domestic Product (GDP) slowing to 0.4% on the quarter from 0.6%, June monthly output flat after 0.1%, and manufacturing production contracting 0.2% after a 0.1% gain. Tightening into that, with an October 28 Budget already committed to a tax lock and to borrowing at the edge of investor tolerance, is a harder vote to win than a growing minority makes it look.
The Dollar did most of the work
Trace the advance back and it begins on August 7, when American payrolls contracted by 23K against an 80K consensus and June was revised down to 20K. Futures now split the September Fed meeting almost exactly down the middle, a fraction over half favouring a hold against a fraction under half for a quarter-point increase. The Pound did not earn this level so much as inherit it.
The inheritance is also the vulnerability. Sterling holds its best level since mid-July on a rate differential that one American inflation print can reset, and the domestic offset it would need is three votes that have not yet become five. Wednesday's release is therefore the larger event for this rate, and Thursday's British one only matters if it takes the fourth dissenter off the table.
The week that decides the argument
American CPI lands Wednesday August 12 at 12:30 GMT, headline seen at 0.1% MoM against a -0.4% prior and 3.4% YoY from 3.5%, core at 0.2% MoM from zero and 2.5% YoY from 2.6%. Prediction markets have leaned softer than that consensus. A core reading at three tenths or better revives the September increase and takes this rate lower whatever the Bank of England is thinking.
Britain's turn comes Thursday August 13 at 06:00 GMT, with monthly and second-quarter GDP, industrial production and manufacturing production arriving in one block. American Producer Price Index (PPI) follows at 12:30 the same day, seen at 0.2% MoM from -0.3% and 4.9% YoY from 5.5%, with claims at 202K and two regional Fed presidents speaking either side of it. Retail sales and preliminary Michigan sentiment on Friday August 14 round out a calendar in which the Pound is the passenger for three days out of four.
Technical outlook
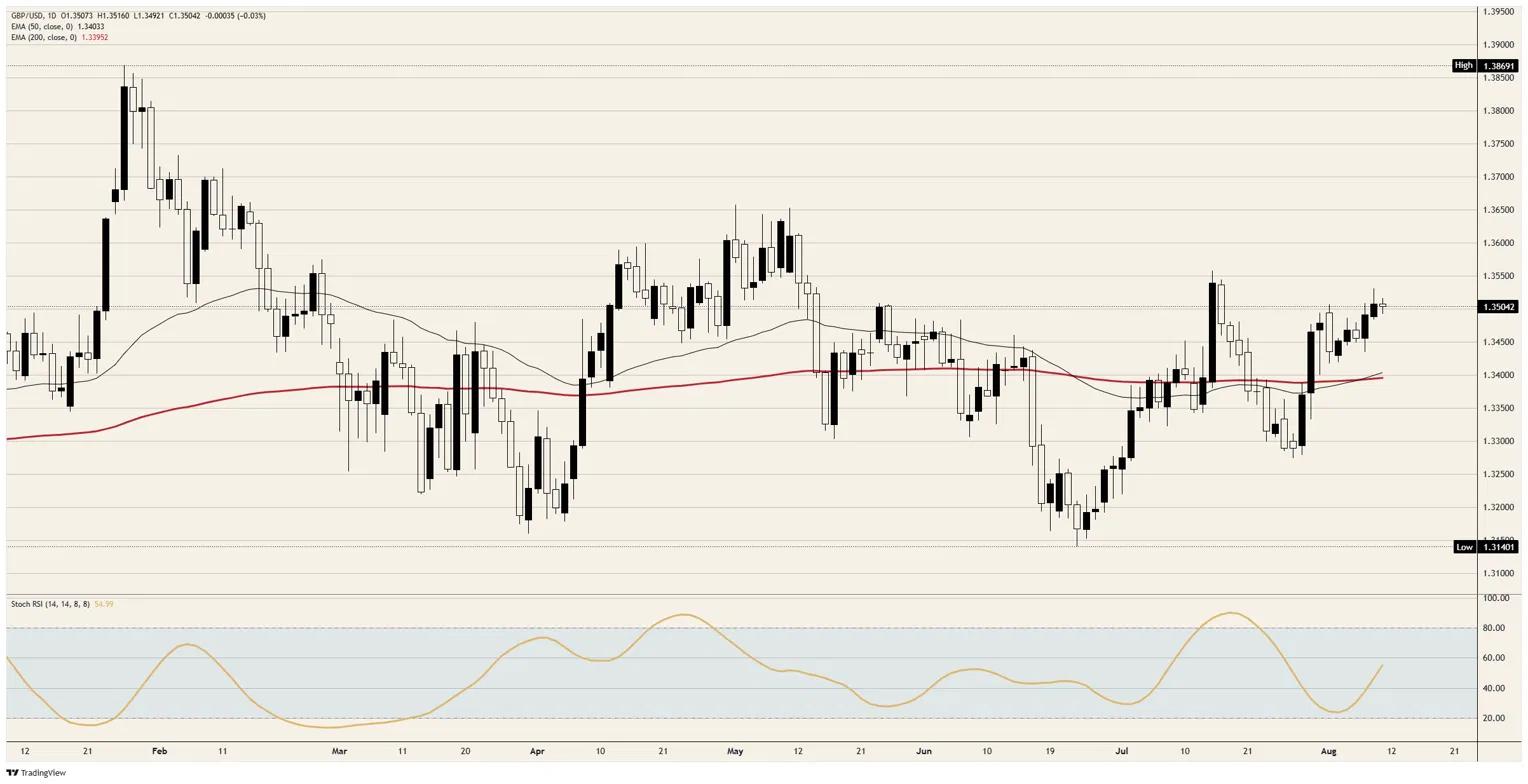
Resistance: The mid-July peak near 1.3550 is the first line, and a daily close through it opens 1.3600, with the February high just short of 1.3900 the longer objective.
Support: 1.3450 is the first floor, beneath which the 50-day and 200-day Exponential Moving Average (EMA) lines, converged near 1.3400, are the level that matters, then 1.3300.
Bias: Bullish while the EMA band near 1.3400 holds, with the daily Stochastic Relative Strength Index (Stoch RSI) near 55 and rising off the early-August base leaving room toward 1.3550. A daily close beneath 1.3400 invalidates the call and reopens 1.3300.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















