Aussie cracks as cool CPI meets a stubborn Kiwi
- Australian CPI undershoots, denting the RBA's hawkish hold story.
- RBNZ holds at 2.25% and gives doves nothing actionable.
- AUD/NZD prints its largest single-day decline in months from generational highs.
The Aussie Dollar finally tripped on Wednesday, dropping nearly 2% against the New Zealand Dollar. AUD/NZD had been grinding to generational highs near 1.2300, fuelled by a story of relative central bank divergence that always looked a little overcooked. It took just one softer-than-expected Australian Consumer Price Index (CPI) print, then a Reserve Bank of New Zealand (RBNZ) that refused to play ball with the doves, to crack the whole setup.
The CPI print the RBA didn't need
Australia's April CPI came in at 4.2% year-on-year (YoY), undershooting the 4.4% consensus and decelerating from 4.6% prior. The monthly read at 0.4% also missed. Trimmed mean inflation was the only line item to hold up, ticking higher to 3.4% YoY, but the headline miss was enough to undermine the case that the Reserve Bank of Australia (RBA) needs to stay restrictive for longer. Front-end Aussie rates softened on the print, and that is what the cross has been ultimately leaning on. Strip away the hawkish RBA story, even at the margin, and there isn't much left holding price above 1.2200.
RBNZ refuses to feed the doves
The other half of the trade fell apart at 02:00 GMT, when the RBNZ left the Official Cash Rate at 2.25%, exactly where it was expected to land. The hold itself was no surprise. What mattered was the accompanying Monetary Policy Statement and press conference, which gave the doves nothing actionable to chew on. Markets had been positioned for at least a cautious tilt toward easing into the back half of the year. They got something closer to patience. The Kiwi caught a rare bid across the board, and against a wounded Aussie the move was outsized.
A technical break that finally landed
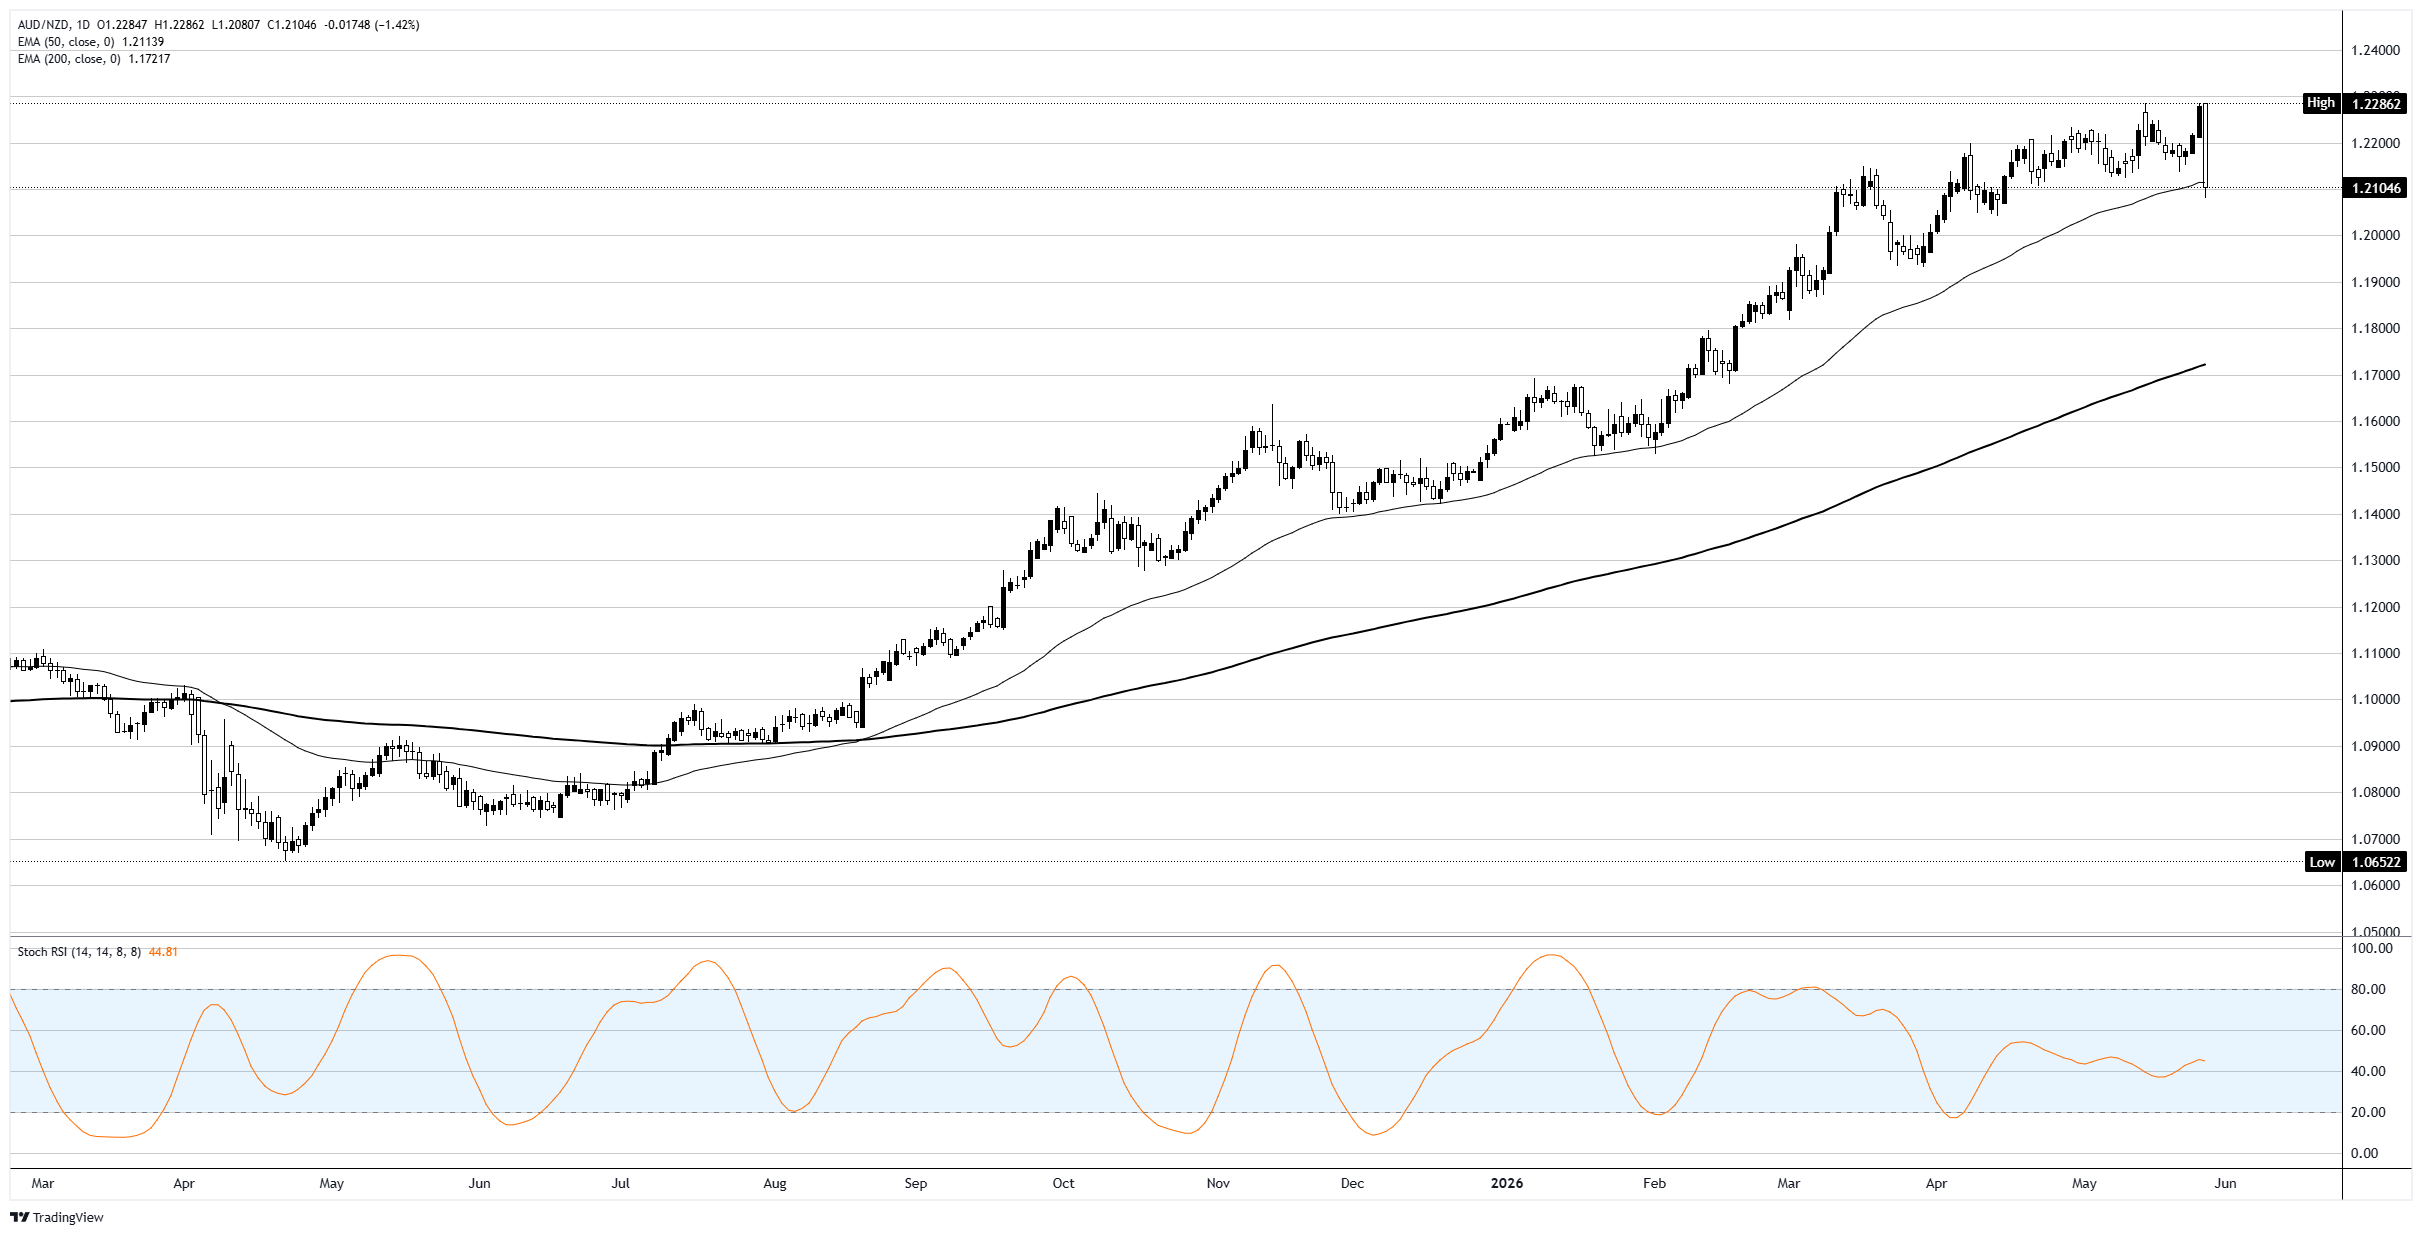
The daily chart had been flashing exhaustion for weeks. Stochastic Relative Strength Index (Stoch RSI) failed to confirm the latest push above 1.2250, and price had been chopping in a tight range near 1.2200 with declining momentum. Wednesday's session sliced through the 50-period Exponential Moving Average (EMA) around 1.2100 intraday, dipping toward 1.2050 before recovering to close right back on that moving average. That close matters. A daily settlement holding above 1.2100 keeps the broader uptrend nominally intact. A sustained break below opens the door to 1.2050 and then the psychological 1.2000 handle, which lines up with consolidation from earlier in the spring.
Levels that matter from here
Bias shifts to neutral with downside risk while price holds beneath 1.2200. A reclaim of 1.2200 puts the recent highs back in play, but Stoch RSI says that is the lower-probability outcome from here. Below 1.2100, momentum sellers have a clean runway toward 1.2050, then 1.2000, where buyers should defend hard given the strength of the longer-term trend. The 200 EMA sits down near 1.1700, which gives a sense of just how stretched this pair remains on any structural timeframe.
What the calendar holds
Thursday brings Australian Private Capital Expenditure (Q1) and the New Zealand Budget Release, neither of which should derail the post-CPI repricing. The RBA Bulletin lands the same day and will be scrutinised for any softening in the inflation framing. The bigger risk into next week is the Q1 Capex print itself, which can move RBA expectations meaningfully if it misses.
AUD/NZD daily chart
New Zealand Dollar FAQs
The New Zealand Dollar (NZD), also known as the Kiwi, is a well-known traded currency among investors. Its value is broadly determined by the health of the New Zealand economy and the country’s central bank policy. Still, there are some unique particularities that also can make NZD move. The performance of the Chinese economy tends to move the Kiwi because China is New Zealand’s biggest trading partner. Bad news for the Chinese economy likely means less New Zealand exports to the country, hitting the economy and thus its currency. Another factor moving NZD is dairy prices as the dairy industry is New Zealand’s main export. High dairy prices boost export income, contributing positively to the economy and thus to the NZD.
The Reserve Bank of New Zealand (RBNZ) aims to achieve and maintain an inflation rate between 1% and 3% over the medium term, with a focus to keep it near the 2% mid-point. To this end, the bank sets an appropriate level of interest rates. When inflation is too high, the RBNZ will increase interest rates to cool the economy, but the move will also make bond yields higher, increasing investors’ appeal to invest in the country and thus boosting NZD. On the contrary, lower interest rates tend to weaken NZD. The so-called rate differential, or how rates in New Zealand are or are expected to be compared to the ones set by the US Federal Reserve, can also play a key role in moving the NZD/USD pair.
Macroeconomic data releases in New Zealand are key to assess the state of the economy and can impact the New Zealand Dollar’s (NZD) valuation. A strong economy, based on high economic growth, low unemployment and high confidence is good for NZD. High economic growth attracts foreign investment and may encourage the Reserve Bank of New Zealand to increase interest rates, if this economic strength comes together with elevated inflation. Conversely, if economic data is weak, NZD is likely to depreciate.
The New Zealand Dollar (NZD) tends to strengthen during risk-on periods, or when investors perceive that broader market risks are low and are optimistic about growth. This tends to lead to a more favorable outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Conversely, NZD tends to weaken at times of market turbulence or economic uncertainty as investors tend to sell higher-risk assets and flee to the more-stable safe havens.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















