Breaking: ADP Employment Change rose by 62K in March
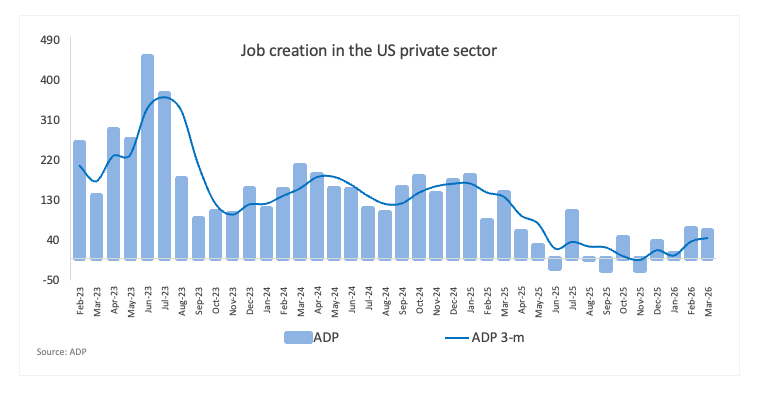
Private employers added 62K jobs in March, the Automatic Data Processing (ADP) reported on Wednesday. This reading followed the 66K increase (revised from 63K) recorded in the previous month and came in above the market expectation of 40K growth.
Assessing the report's findings, Nela Richardson, chief economist at ADP, stated, “Overall hiring is steady, but job growth continues to favour certain industries, including health care. In March, this solid performance was accompanied by a boost in pay gains for job-changers.”
Market reaction to ADP Employment Change data
The US Dollar builds on Tuesday’s losses, prompting the US Dollar Index (DXY) to recede to fresh five-day lows near 99.40 in the wake of the release.
US Dollar Price Today
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the strongest against the Canadian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.43% | -0.68% | -0.21% | -0.15% | -0.75% | -0.44% | -1.00% | |
| EUR | 0.43% | -0.26% | 0.22% | 0.27% | -0.31% | 0.02% | -0.57% | |
| GBP | 0.68% | 0.26% | 0.49% | 0.55% | -0.04% | 0.29% | -0.30% | |
| JPY | 0.21% | -0.22% | -0.49% | 0.08% | -0.50% | -0.22% | -0.75% | |
| CAD | 0.15% | -0.27% | -0.55% | -0.08% | -0.58% | -0.29% | -0.84% | |
| AUD | 0.75% | 0.31% | 0.04% | 0.50% | 0.58% | 0.32% | -0.25% | |
| NZD | 0.44% | -0.02% | -0.29% | 0.22% | 0.29% | -0.32% | -0.56% | |
| CHF | 1.00% | 0.57% | 0.30% | 0.75% | 0.84% | 0.25% | 0.56% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
This section below was published as a preview of the ADP Employment Change data at 7:30 GMT.
- With the ADP and NFP, it will be another key week for the US labour market.
- The US private sector is expected to add 40K new jobs in March.
- The US Dollar Index remains well bid amid steady geopolitical concerns.
This week, the US job market will be in the spotlight as worries mount that the economy may be losing steam. The first relevant release will be on Wednesday with the ADP Employment Change, which is expected to show that the private sector added 40K jobs in March, marking a slowdown compared to the 63K in February.
Economic worries have been growing amid weaker GDP signals and some less optimistic underlying statistics, while there is still uncertainty about the impact of US tariffs and the Middle East crisis.
The first important check-in is on Wednesday, when the ADP Research Institute issues its March Employment Change report. This data gives an early look at how many people are being hired in the US private sector.
The ADP data is best considered as a general guide rather than an exact forecast, even though it usually comes out a few days before the official Nonfarm Payrolls (NFP) report. It may give you an idea of where the job market is going, but it doesn't always match up perfectly with the Bureau of Labour Statistics numbers.
Under pressure: Employment, inflation, and Fed strategy
Employment sits at the core of the Federal Reserve’s (Fed) dual mandate, alongside price stability, and right now, it is back in focus.
With inflation proving stubborn, attention has shifted toward the US labour market following the Fed’s hawkish stance at its March 18 meeting. At the same time, investors are watching developments in the Middle East conflict, particularly its impact on energy prices and thus future inflation.
This week’s labour market data take on added importance against the backdrop of tariff uncertainty, signs of slowing growth, and still-elevated inflation. The ADP report will provide an initial indication, but the focus will be on Friday’s Nonfarm Payrolls, which could play a crucial role in determining expectations for the Fed’s next move.
When will the ADP report be released, and how could it affect the US Dollar Index?
The ADP Employment Change report for March will come out on Wednesday at 12:15 GMT. Predictions are for a slight rise of around 40K jobs after February's mild growth of 63K jobs.
The US Dollar Index (DXY) is still strong as it heads into the release, trading at levels last seen in May 2025. This is because the market is wary because of continued tensions in the Middle East.
If the ADP report is higher than expected, it might help assuage worries that the economy is slowing. On the other hand, another lower-than-expected print would likely make markets even more worried about a slowdown, which may make the Fed more inclined to cut rates down the road.
Pablo Piovano, Senior Analyst at FXStreet, explains that if bullish momentum picks up pace, the US Dollar Index (DXY) should initially retest its year-to-date ceiling of 100.64 (March 31). Once this level is cleared, the index could attempt a test of the May 2025 high at 101.98 (May 12) ahead of the weekly top at 104.68 (March 26).
“On the flip side, the breach below the key 200-day SMA at 98.41 should expose a potential retracement to the February base at 96.49 (February 11) prior to the 2026 bottom at 95.55 (January 27),” Piovano adds.
“Momentum indicators continue to prop up the ongoing recovery, with the Relative Strength Index (RSI) above the 58 level and the Average Directional Index (ADX) around 35, suggesting a robust trend," Piovano concludes.
Employment FAQs
Labor market conditions are a key element to assess the health of an economy and thus a key driver for currency valuation. High employment, or low unemployment, has positive implications for consumer spending and thus economic growth, boosting the value of the local currency. Moreover, a very tight labor market – a situation in which there is a shortage of workers to fill open positions – can also have implications on inflation levels and thus monetary policy as low labor supply and high demand leads to higher wages.
The pace at which salaries are growing in an economy is key for policymakers. High wage growth means that households have more money to spend, usually leading to price increases in consumer goods. In contrast to more volatile sources of inflation such as energy prices, wage growth is seen as a key component of underlying and persisting inflation as salary increases are unlikely to be undone. Central banks around the world pay close attention to wage growth data when deciding on monetary policy.
The weight that each central bank assigns to labor market conditions depends on its objectives. Some central banks explicitly have mandates related to the labor market beyond controlling inflation levels. The US Federal Reserve (Fed), for example, has the dual mandate of promoting maximum employment and stable prices. Meanwhile, the European Central Bank’s (ECB) sole mandate is to keep inflation under control. Still, and despite whatever mandates they have, labor market conditions are an important factor for policymakers given its significance as a gauge of the health of the economy and their direct relationship to inflation.
Economic Indicator
Nonfarm Payrolls
The Nonfarm Payrolls release presents the number of new jobs created in the US during the previous month in all non-agricultural businesses; it is released by the US Bureau of Labor Statistics (BLS). The monthly changes in payrolls can be extremely volatile. The number is also subject to strong reviews, which can also trigger volatility in the Forex board. Generally speaking, a high reading is seen as bullish for the US Dollar (USD), while a low reading is seen as bearish, although previous months' reviews and the Unemployment Rate are as relevant as the headline figure. The market's reaction, therefore, depends on how the market assesses all the data contained in the BLS report as a whole.
Read more.Next release: Fri Apr 03, 2026 12:30
Frequency: Monthly
Consensus: 60K
Previous: -92K
Source: US Bureau of Labor Statistics
America’s monthly jobs report is considered the most important economic indicator for forex traders. Released on the first Friday following the reported month, the change in the number of positions is closely correlated with the overall performance of the economy and is monitored by policymakers. Full employment is one of the Federal Reserve’s mandates and it considers developments in the labor market when setting its policies, thus impacting currencies. Despite several leading indicators shaping estimates, Nonfarm Payrolls tend to surprise markets and trigger substantial volatility. Actual figures beating the consensus tend to be USD bullish.
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.