Week ahead: Inflation numbers in the spotlight


Following a subdued (somewhat monotonous) week, the economic calendar will give us more to get our teeth into this week.
US and UK CPI inflation
Along with several tier-1 data releases, the focus this week consists of inflation data from the US and the UK on Tuesday and Wednesday, respectively.
In the US, you will recall year-on-year inflation was unchanged at 3.7% in the twelve months to September, and the core measure for the same period eased to 4.1%, down from 4.3% in August. The current median estimate supplied by Bloomberg heading into the headline number on Tuesday calls for inflationary pressures to cool to 3.3% in the twelve months to October (estimate range between 3.4% and 3.2%), with the core measure expected to ease slightly to 4.0%. The FP Markets Research Team released a technical post on the position of the US Dollar Index here for the week ahead.
You will recall that Fed Chair Jerome Powell participated in a panel discussion titled Monetary Policy Challenges in a Global Economy at the Jacques Polak Annual Research Conference last week. Powell noted that the Fed will ‘not hesitate’ to tighten policy further if needed and is making decisions meeting by meeting. Powell added: ‘We will continue to move carefully, however, allowing us to address both the risk of being misled by a few good months of data and the risk of overtightening’. Powell also noted: ‘My colleagues and I are gratified by this progress [retreat in price pressures] but expect that the process of getting inflation sustainably down to 2% has a long way to go’. The speech elevated the greenback/US yields and weighed on major US equity indices. Given Powell’s speech, this week’s inflation data will be important; any marked deviation could see markets reprice rate expectations. Current market pricing, nonetheless, implies that the Fed is done and dusted with rate hikes, and rate cuts could come as early as mid-2024.
Across the Atlantic, UK CPI inflation data is out on Wednesday. Economists anticipate that year-on-year inflation will slow to 4.8% in the twelve months to October from 6.7% in September (estimate range is between 6.5% and 4.7%). The sizeable decline in headline inflation will be largely on the back of base effects from utility prices. Year-on-year core inflation is also expected to slow to 5.8% over the same period, down from 6.1% in September (estimate range is between 6.0% and 5.5%).
You may remember that the Bank of England (BoE) held the Bank Rate steady at 5.25% at the last MPC meeting on 2 November, marking a second consecutive meeting where the MPC pressed the pause button. Regarding the BoE’s revised projections, the consumer price index (CPI) inflation is expected to cool. The BoE expects CPI inflation to cool to 4.75% in Q4 of 2023, 4.25% in Q1 of 2024 and 3.75% in Q2 of 2024. The MPC summary added: ‘This decline is expected to be accounted for by lower energy, core goods and food price inflation and, beyond January, by some fall in services inflation’. From a growth perspective, GDP is expected to be flat in Q3 this year, though it is anticipated to grow by a meagre 0.1% in Q4.
Void of any upside surprises in the data this week for the UK—inflation and wages—it’s difficult to see the BoE deviating from the current Bank Rate in December, with many desks communicating that they believe the central bank is done with hiking. However, an upside surprise this week, although unlikely to influence the odds for a rate hike by much, could see market pricing pullback on when the BoE may begin cutting rates. In terms of the technical picture, GBP/USD appears poised to overthrow $1.22 to the downside, given the higher timeframes display scope to explore deeper terrain.
Additional tier-1 data this week
14 November:
- UK Employment Data
- UK Wages Data
- Germany ZEW Economic Sentiment Index
15 November:
- Australia Wage Price Index
- US Inflation Data (PPI)
- US Retail Sales
- United States NY Empire State Manufacturing Index
16 November:
- Australia Employment Data
- China Industrial Production
- China Retail Sales
- US Weekly Unemployment Claims
- United States Philadelphia Fed Manufacturing Index
- US Industrial Production Data
-
17 November:
- UK Retail Sales
- US Housing Data (Building Permits)
G10 FX (5-Day Change):
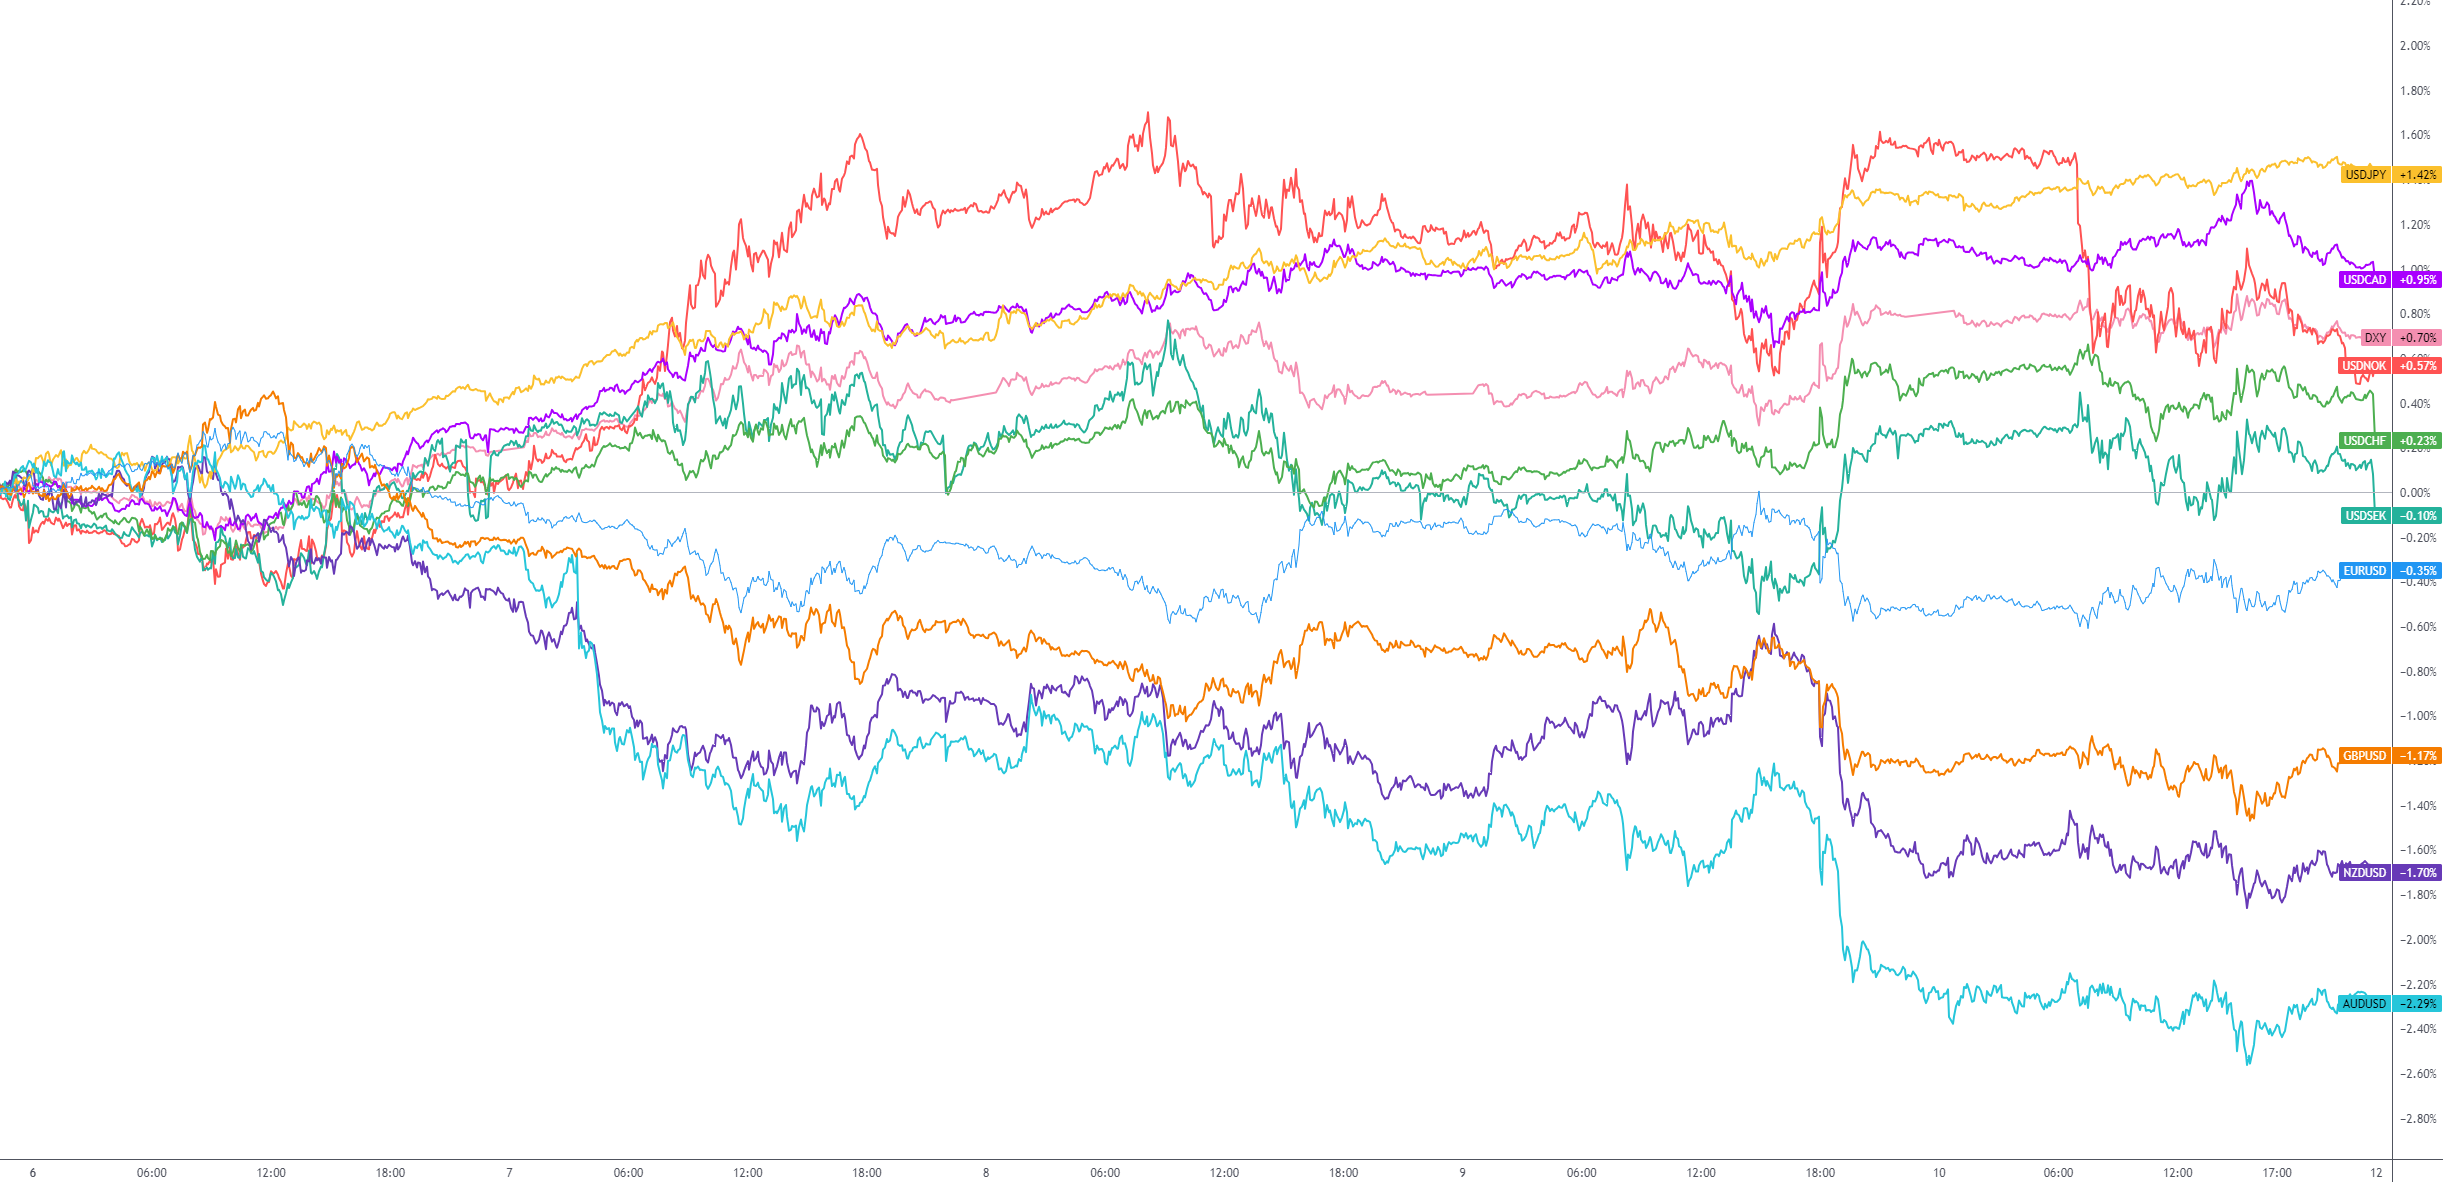
Charts: TradingView
Author
Aaron Hill
FP Markets
After completing his Bachelor’s degree in English and Creative Writing in the UK, and subsequently spending a handful of years teaching English as a foreign language teacher around Asia, Aaron was introduced to financial trading,

















