Wary of bull market chorus

S&P 500 opened with a spike only to lose steam, as tech retreated no matter what Big Tech did, and junk corporate bonds slowly deflated too. Those initially strong rotations back into prior stars (XLK, XLC, XLU) gave way, and supportive XLV was likewise affected. The rally didn‘t last, and stock bulls were warned with a shot across the bow – on low volume, with merely pausing certain market breadth characteristics. This isn‘t yet the top, simply put, but we‘re slowly getting there.
Sure, we have seen fine improvements in stocks trading above their 50-day moving averages, and former greatest laggards such as XRT and IWM surging higher. Yet I consider the sentiment as getting too greedy, and for all the wrong reasons – we aren‘t avoiding a recession, AI isn‘t going to save us (no huge productivity gains this year alone to avoid recession), job market data would be revised sharply lower over the coming months (e.g. NFPs – the disconnect with household data is tremendous as these showed 310K jobs actually lost), Fed may pause in Jun but remains hawkish and insists this Fed funds rate isn‘t terminal yet, and the TGA replenishment would also bite to quite some degree.
All at a time when the typical timing of both LEIs and yield curve inversion suggests recession dead ahead – why hadn‘t it struck already? Excess savings and highly expansive fiscal with monetary policy consequences that had cushioned consumers as these go, income tier by income tier, through burning their safety margin.
Yet S&P 500 and Nasdaq ignore the NY Fed‘s over 60% recession odds, and chooses to rally on GS downgrading its own recession odds call from 35% to 25%? Looking at the AI story driving 2023 S&P 500 and Nasdaq gains so heavily, one can‘t help but remember the dotcom era, when we coincidently saw also a few rallies surpassing 20% gains, only to see them crash – and regardless of all the new bull market proclamations with broadening market breadth making that call even more alluring, I think this bear market rally would experience the same fate.
Yes, I think that stocks are to break 4,000, and will try to bottom in the low 3,900 if not my 3,865 strong support. That‘s the first chapter covering better part of this summer, the first chapter of making a fine longer-term bottom that investors can buy into – yet now, we‘re still in the euphoric stage of the rally that has a bit further to run, in spite of the wide Nasdaq vs. long-dated Treasury yields disconnect. One can‘t overstay the welcome, and not every market environment being suitable for swing trading (just remember the long, tight range chop below 4,209), which was my motivation behind introducing Intraday Signals (ideally combined with Trading Signals or at least Stock Signals), so as to take advantage of both very short-term opportunities and the medium-term ones, as a fine diversification tool.
Beaten down bears would go on capitulating, one by one – succumbing to the false dawn that‘s about as alluring as the post Bear Sterns times when the bottom was supposedly in also in terms of the real economy. It won‘t be any different over this summer and Sep when the buyers would realize that deteriorating data even in non manufacturing risk dipping into recessionary territory again, and real estate beyond commercial would deteriorate alongside retail sales beyond same store sales or unemployment ranging from initial to continuing claims.
Realization of hitting recession together with fresh need for earnings downgrades would be that confirming catalyst of upcoming selling in stocks, when the strength of Top 7 performers starts losing momentum, and the rotation into former laggards won‘t be able to overcome the 500-strong index weakness. Just as the Oct lows rally peaked out in breadth late Nov 2022, the latest comeback in stocks trading above their 50-day moving averages won‘t be enough to keep S&P 500 from declining when all those passive investing models start to recognize further upside potential in Top 7 stocks as fading, triggering sectoral rebalancing, including out of the stock market altogether, and in favor of risk-off trades and safe havens such as USD that‘s set to rise over the weeks ahead.
A few more recessionary indications before the rich chart section with levels and upcoming directional moves – bankruptcies unseen since 2010, deliquencies with tightening bank lending standards, acceleration in initial claims YoY that would affect the analogical unemployment rate statistics, neither fiscal nor monetary policy in a further expansive mode, poor housing affordability thanks to high mortgage rates preventing existing supply from entering the market to clear it and facilitate a real estate bottom – and the business cycle in general still pointing south.
S&P 500 and Nasdaq Outlook
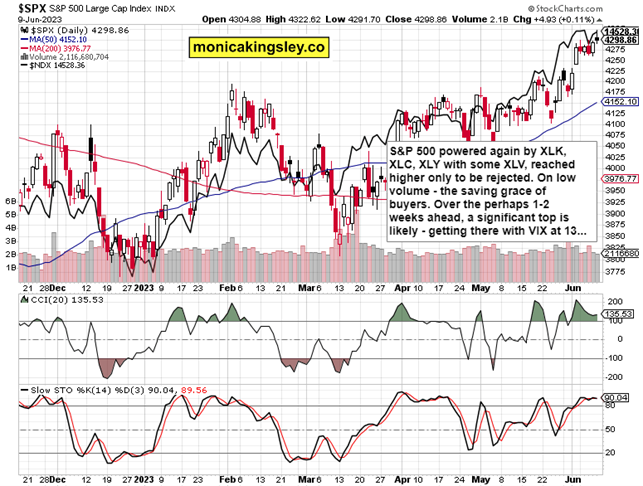
For all the deterioration Friday, it‘s impossible to call for a top being in – its prerequisite setup would be $XLK $XLC $XLY and $XLV leading higher while former laggards such as $XLF $KRE $XRT and $IWM do their best to more than follow, only to be superseded by tech, communications and discretionaries wobbling seriously while rotation into the rest fails to lift S&P 500 up enough to prevent its decline, and it gets dragged along.
We aren‘t there quite yet, especially not from the point of view of volume analysis. Both the 4,305 - 4,315 area and 4,330 are fine examples of where the above described decline dynamics is likely to occur. Nearest supports remain 4,283 followed by high 4,260s, and present buying opportunities given the sentiment these days
What‘s most likely for Monday, is consolidation close to the 4,315 area – and that goes till FOMC, which I‘m looking not to hike rates in Jun but strongly hint at Jul hike, maintaining as hawkish a stance as possible, which stocks however would buck by spiking higher when all is said and done.
Gold, Silver and Miners
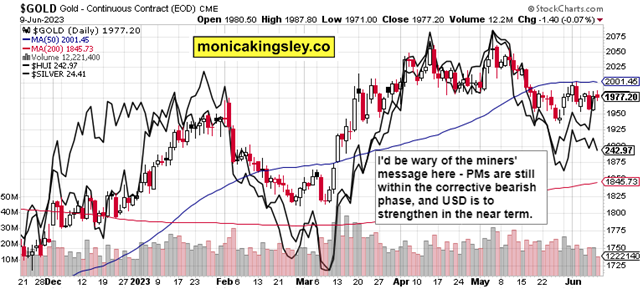
Given what I see over the upcoming weeks play out in USD, it‘s hard to call for precious metals appreciation, also given the fact that headline disinflation hadn‘t yet run its course (silver and copper would notice first). The miners‘ weakness is providing more than an advance warning that this isn‘t the time to be bullish, but rather cautious even if gold as such welcomes Wednesday‘s Fed decision.
Author
Monica Kingsley
Monicakingsley
Monica Kingsley is a trader and financial analyst serving countless investors and traders since Feb 2020.