Oil prices surge as bond market sell off could wipe out Chancellor’s fiscal headroom
Brent crude is higher by 4% on Thursday and is currently trading above $105 per barrel, the highest level since May, as Iran’s allies, the Houthis, are reported to have seized a key Red Sea port in Yemen.
Middle East war spreads beyond Strait of Hormuz
This poses a further threat to global energy supplies, and suggests that tensions in the region are spreading beyond the Strait of Hormuz, posing a new threat to global energy supplies from Saudi Arabia, in particular. Although President Trump has said that the war will end after the November Mid Term elections, there is no way that the market can believe this claim, as the situation remains perilous.
Why UK bond yields are rising at a faster pace than elsewhere
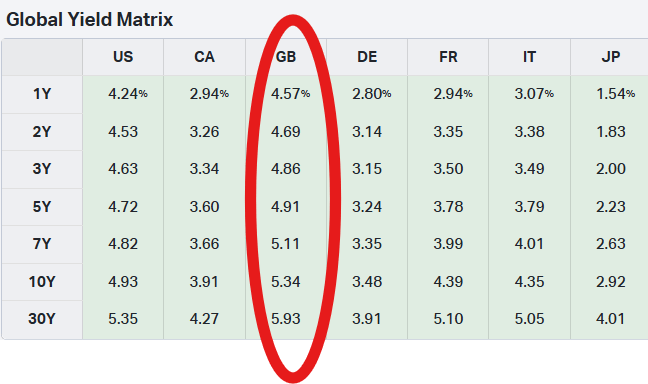
The surge in the oil price is having a pass through effect on the bond market, and sovereign bonds are selling off sharply. UK bond yields have jumped on Thursday, and are rising at a faster rate than our peers in the US or Europe. The 2-year yield is higher by another 10bps and the 30-year yield is edging towards 6%, and is currently trading at 5.94%. The long end of the UK yield curve is hurtling towards 6%, the last time the 30-year yield was at this level was in early 1998.
Although the move higher in bond yields is a global phenomenon caused by an energy price shock, the fact that UK bond yields are rising at a faster pace than elsewhere, suggests that there is a specific risk premium attached to UK debt right now.
The UK’s risk premium
The government needs to be careful of this premium. Its decisions on tax and spend in the upcoming Budget, can have a big impact on UK yields. For example, Andy Burnham’s refusal to commit to welfare cuts to fund defense on Wednesday, is a problem for bond investors and is weighing on bond yields today. While it is entirely reasonable to suggest that the UK’s rising borrowing costs are due to global factors, there is a portion of the increase that is down to government decisions that are causing concern about the fiscal rules and the sustainability of UK government debt.
The war in the Middle East is a major concern for the UK government, because of our idiosyncratic energy infrastructure. Although the UK imports less gas as a percentage of total gas use compared to Europe, we have far less gas storage, which means that the UK is more exposed to the spot market, and to price surges like we are currently seeing. European natural gas prices have jumped from around $50 in early August to $81 now, which is the highest level since 2022.
The implication for the Budget
UK yields are now at multi-decade highs, which pose a major problem for the UK Chancellor. With just over 6 weeks to go before his inaugural budget, surging bond yields are rapidly eroding his fiscal headroom. With 10-year yields hitting 5.3%, and 30-year yields trading just below 5.95%, fiscal headroom will have been eroded to £8bn - £9bn from the original £23.6bn included in last year’s Budget. If the 30-year yield hits 6%, and the rest of the yield curve moves towards this level, then the Chancellor’s headroom would be wiped out completely.
Will Healey deliver an emergency budget?
If we see oil prices continue to move deeper into triple digit territory, then the above scenario is possible. This would transform next month’s Budget into an emergency Budget to plug fiscal holes. Tax rises under the Labour government are nothing new, but Healey and co. may also be forced into huge welfare cuts to bring borrowing down and pay the debt interest bill. Andy Burnham may have tried to protect welfare spending this week, but his hopes and dreams are meeting the reality of the bond vigilantes who keep pushing UK yields to multi-year highs.
UK bond yields are higher than elsewhere
Source: Koyfin and XTB
Author

Kathleen Brooks
XTB UK
Kathleen has nearly 15 years’ experience working with some of the leading retail trading and investment companies in the City of London.

















