Markets consolidate after CPI
The week of August 10–14 was relatively calm after the publication of US CPI for July. No panic or capitulation followed, as the number came in as expected or slightly cooler. Traders have observed a slow drift higher in equities.
July CPI rose 0.1% month-on-month and 3.4% year-on-year, both in line with forecasts. Core CPI eased to 2.5% annually — the slowest pace since March 2021, though the publication has met expectations, thus the reaction of markets was limited. September interest rate hike odds have decreased below 50%, giving some relief for cyclical assets. S&P 500 was the most notable mover this week: market breadth and risk appetite has increased for all sectors.
CPI and PPI: no surprise, and that was the point
The inflation week did not shock anyone. Gasoline fell 2.9% on the month and helped the headline; core services remain the sticky piece. Wells Fargo’s Gary Schlossberg said the CPI reading plus last week’s weak jobs report “may keep hawkish Fed officials at bay in September” — though oil tied to the Middle East still leaves the outlook guarded.
PPI at 0.0% followed June’s decline, so the producers’ pipeline is not re-accelerating. Markets treated both prints as neutral: another CPI and another jobs report is underway ahead of September’s FOMC meeting. Warsh has given no forward guidance, so Jackson Hole at the end of August is the next place he might “frame the big questions” without telegraphing a hike.
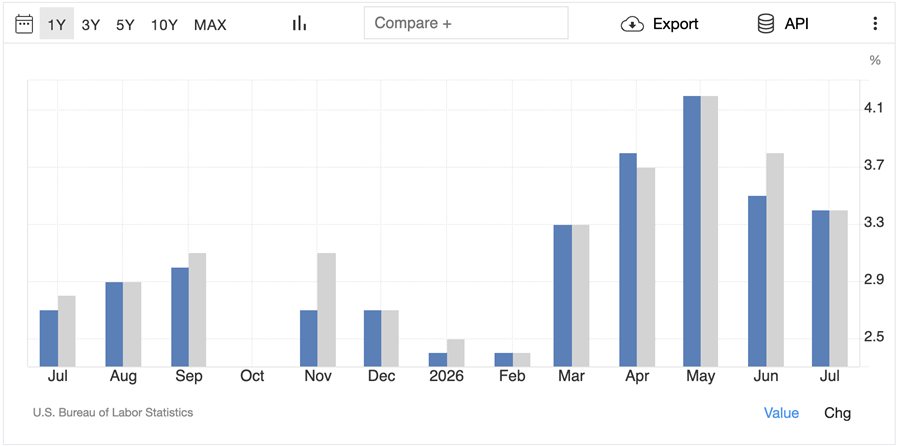
US inflation. Source
Equities: a quiet US uptick, a louder rebound in Asia
The US stock market showed an uptick as S&P500 had reached another all time high on Thursday, Aug 13th. Nasdaq had displayed a quieter momentum, but overall improvement of market breadth and low volatility pushed it higher too. Volume is still muted amid decreased summer’s activity .
Asian indices showed a more active pace. For example, South Korea’s Kospi index had jumped around 3.7 -- 4.4% into a technical bull market, with Samsung and SK Hynix leading the rally. Bloomberg described a return of the “long Korea, short Hong Kong” narrative unfolding in the markets.
Brent had locked in a range around $88 level reflecting absence of game changing news in the Hormuz Strait. The traffic hasn’t restored yet and there are no signs of deescalation.
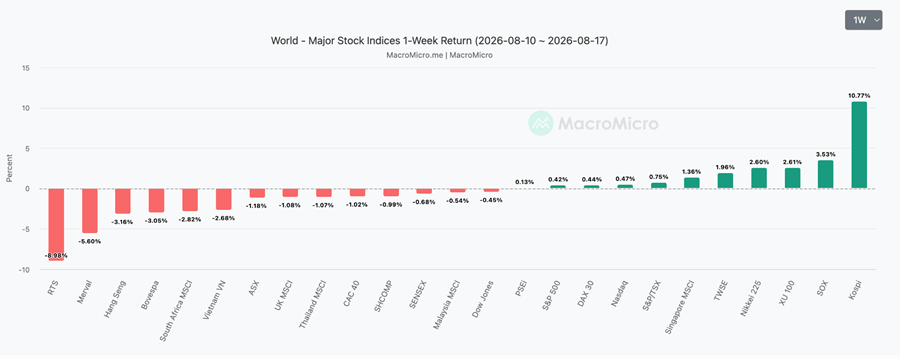
Performance of stock indices for the previous week. Source: macromicro.me
News in focus this week
August 26: Nvidia earnings — the next real test of the AI rally.
August 27–29: Jackson Hole — Warsh’s first symposium speech as chairman of the Federal Reserve.
Now let’s shift to potential scenarios and trading ideas for the week ahead.
Gold
Gold takes a break after the rapid price discovery extension. After the breakout fueled by weaker than expected NFP a spike toward $4,400 area, gold paused having locked in a trading range, as CPI hasn’t brought any fuel for immediate continuation.
However, there are more dovish than hawkish signs for the US interest rate: the probability of an interest rate hike in September has declined to 40% from the previous reading of 50% (before CPI), which might be considered as a mild dovish pressure.
Now, Gold is moving within a strong seasonal trend, and if it will resume pressuring to the border of a trading range this week, it might potentially break it and achieve the zone of $4500 - 200-day moving average.
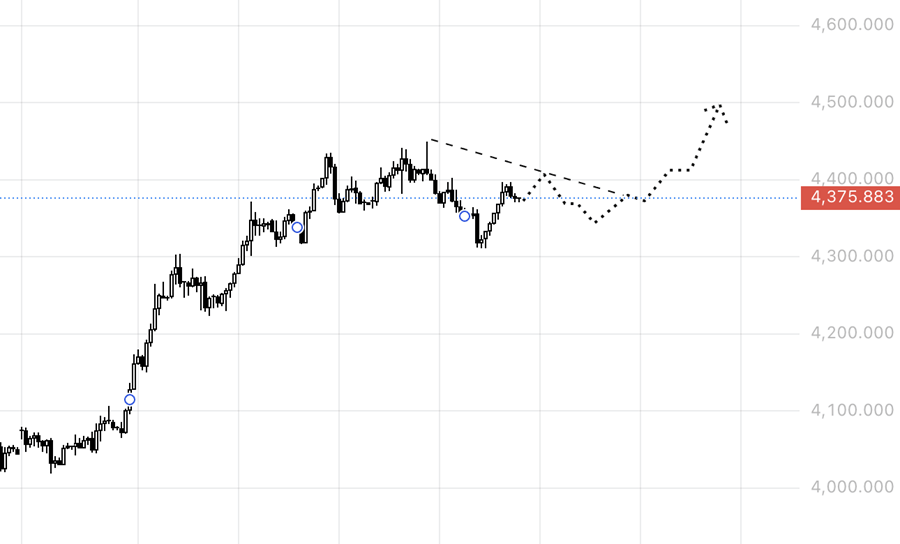
Possible development of XAUUSD, 2-hour chart. In case of completion of the trading range, price may test its boundary and develop a new wave of upswing with a target of $4500+. Source: Exness.com
Copper
Copper is arguably one the most bullish instruments in the metals group, having been driven by the demand from the AI sector: copper is actively used for data centers and electricity nets. Thus, the ongoing consolidation for XCUUSD might end up with a breakout and price discovery to the new price area.
Even though it's quite difficult to time breakouts, the consolidation with a low volatility right above the border of the triangular formation may lead to the breakout, as shown on the chart below.
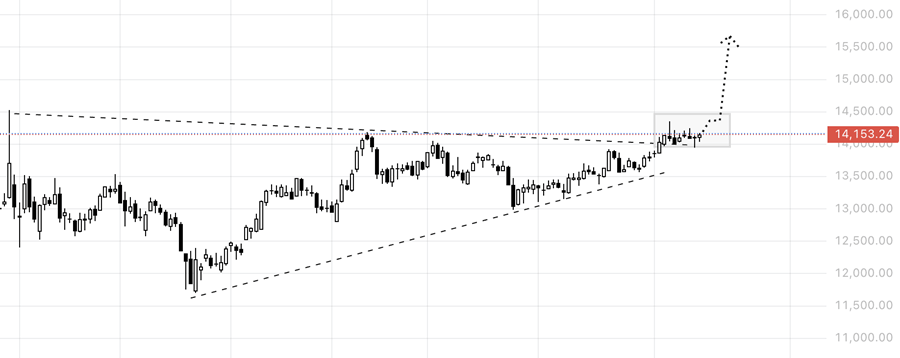
XCUUSD, daily chart. Source: Exness.com
Author

Stanislav Bernukhov
Exness
Born in 1980, Stanislav graduated from the university in 2003. He worked in the music industry and ran his own business ventures before being introduced to trading in 2004.

















