EUR/USD Weekly Forecast: ECB to hike as Trump pushes for lower US rates
- United States employment data delivered a positive surprise ahead of critical inflation data.
- The European Central Bank is widely anticipated to hike interest rates by 25 basis points.
- EUR/USD maintains its neutral stance as investors await central bank updates.

The EUR/USD pair posted a modest comeback after falling in the last week of August, finishing the week just above the 1.1600 level. The US Dollar (USD) lost momentum and corrected lower on Monday, but overall it retained its recently regained strength amid persistent Middle East tensions and speculation that the Federal Reserve (Fed) will have to raise the benchmark interest rate in September. The USD resumed its advance on Friday, as upbeat employment data brought back demand.
United States employment and inflation
In between, the Greenback suffered a minor setback: Fed Governor Christopher Waller cooled the odds for a September rate hike on Thursday by saying that officials can “wait one meeting,” as long as there are no surprises from upcoming inflation data. He also noted that a 25-basis-point (bps) hike won’t bring inflation back to 2%.
The Bureau of Labor Statistics (BLS) will release the August Consumer Price Index CPI) and the Producer Price Index (PPI) for the same month in the upcoming days. Indeed, the CPI may not be the Fed’s favorite inflation gauge, but it's a reliable indicator of inflationary pressures and may define whether the Fed will hike or hold when it meets later this month.
The United States (US) published the August Nonfarm Payrolls (NFP) report on Friday, with upbeat figures backing the USD. The country added 162K new jobs in the month, much better than the anticipated 56K. The Unemployment rate held steady at 4.1% as expected. Furthermore, annual wage inflation, as measured by the change in Average Hourly Earnings, declined to 3.1% from 3.2%.
Other than that, the country published the August ISM Purchasing Managers’ Indexes (PMIs). The manufacturing index eased to 54.6 from 55.6 in July, while the Services PMI improved to 55.4 from 54.1 in the previous month. Within the manufacturing sector, inflation held steady as the Prices Paid Index printed at 71.1, matching the previous monthly reading. On services output, the Prices Paid Index edged higher to 72.6 from 70.3. A reading above 50 means that more businesses are paying higher prices than in the previous month, meaning inflationary pressures are being felt up and down across all businesses.
So, while Fed Governor Waller hinting at an on-hold September decision temporarily took its toll on the USD, the fact is that inflationary pressures are high enough for speculative interest to price in upcoming hikes. Rising energy prices amid the Middle East war are no doubt the main factor driving market concerns, with Crude Oil Prices regaining positive momentum after the US and Iran resumed hostilities in late August.
European Central Bank and Eurozone inflation
Inflation is not a problem exclusive to the US. Germany reported that the Harmonized Index of Consumer Prices (HICP) rose 2.9% YoY in August, according to preliminary estimates, higher than the previous 2.8% although better than the expected 3.1%. Furthermore, Retail Sales in the country fell 3.4% in July, worsening from a flat reading in July. The Eurozone HICP in the same period printed at 3.3% as expected, rising from the 2.9% posted in July.
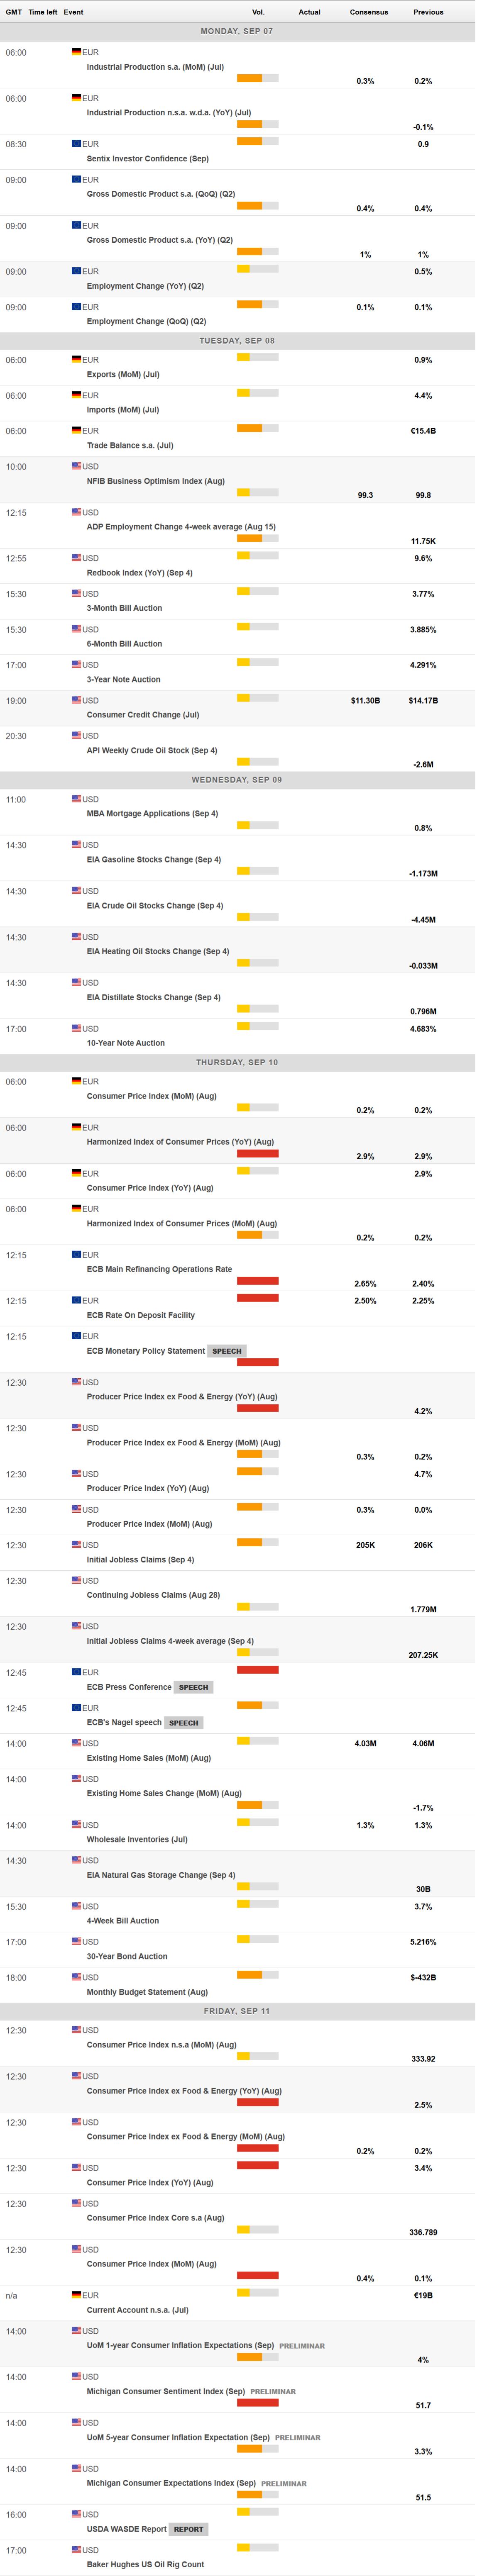
The situation is similar; what’s different is how central banks are reacting to the news: the European Central Bank (ECB) has already hiked interest rates by 25 bps and is expected to deliver a similar rate increase when it meets on Wednesday. The move is largely priced in, which means the impact on the Euro could be limited.
The ECB faces yet another challenge: President Christine Lagarde, whose term as the ECB head ends in October 2027, may be due to an early exit. Market talks suggest she would step down before France’s Presidential elections either to participate in them or to allow President Emmanuel Macron to have a voice on Lagarde’s successor at the central bank. Lagarde refrained from confirming or denying such rumors, but left the door open for an early departure.
Other than the ECB decision, the European macroeconomic calendar will include the final estimates of the German and Eurozone HICP.
There’s yet another factor pushing central banks to raise rates. Government bond yields are on the loose amid inflation-related concerns and geopolitical tensions. Higher borrowing costs affect the country’s economy and add to the inflationary process. Central banks’ tools may not be enough to tame the chaos, but inaction from policymakers will make the picture even worse.
By the end of the week, however, US President Donald Trump, once again called for lower rates: “The Fed Board, with its great new leader, must get smart - BE PATRIOTS for a change. High interest rates put the U.S.A. at a very unfair disadvantage, and I won’t allow that to happen!,” he posted on Truth Social, also threatening to stop trade with countries with higher rates.
Indeed, President Trump’s desire for lower rates is probably the main reason why Chair Kevin Warsh has refrained from hiking rates despite pledging multiple times to fight inflation. The Fed is between a rock and a hard place.
EUR/USD Technical Outlook:
From a technical point of view, the daily chart shows EUR/USD trading with a neutral-to-slightly bullish tone as it consolidates between nearby moving averages. The pair is trading above the 20-day Simple Moving Average (SMA) at 1.1608 and the 100-day SMA at 1.1564, which together suggest a tentative underlying bid, while it remains capped by the 200-day SMA at 1.1634. Momentum fades, with the 14-day Relative Strength Index (RSI) indicator easing at around 56 and the 14-period Momentum indicator nearing its midline from above, suggesting buyers are losing interest.
On the weekly chart, EUR/USD trades above the 20-, 100-, and 200-week SMAs, with the shortest SMA at 1.1562 providing immediate dynamic support. The broader price placement comfortably above the 100-week SMA at 1.1337 and the 200-week SMA at 1.1075 suggests the medium-term uptrend remains intact, yet technical indicators, holding around their midlines and directionless, suggest investors are unwilling to take stronger positions.
On the topside, immediate resistance is at the 200-day SMA around 1.1634; a daily close above this barrier would open the way for a retest of recent highs in the 1.1710 region, ahead of the 1.1800 threshold. On the downside, initial support is seen at the 20-day SMA near 1.1608, with the 100-day SMA at 1.1564 providing a deeper cushion if the pair slips back. A break beneath this latter level would likely open the door for a steeper decline, with 1.1470 as the next level to watch.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Economic Indicator
ECB Monetary Policy Statement
At each of the European Central Bank’s (ECB) eight governing council meetings, the ECB releases a short statement explaining its monetary policy decision, in light of its goal of meeting its inflation target. The statement may influence the volatility of the Euro (EUR) and determine a short-term positive or negative trend. A hawkish view is considered bullish for EUR, whereas a dovish view is considered bearish.
Read more.Next release: Thu Sep 10, 2026 12:15
Frequency: Irregular
Consensus: -
Previous: -
Source: European Central Bank
Author

Valeria Bednarik
FXStreet
Valeria Bednarik was born and lives in Buenos Aires, Argentina. Her passion for math and numbers pushed her into studying economics in her younger years.

















