Can Oil, ISM and AMD keep the tech rebound alive?
As we head into a new week, lower oil and coordinated US-Japan support for the yen have given equities and metals some breathing room.
The next test comes from Fed rate-hike expectations and AMD’s earnings, which could push yields higher and reopen concerns over whether heavy AI spending is delivering sufficient returns.
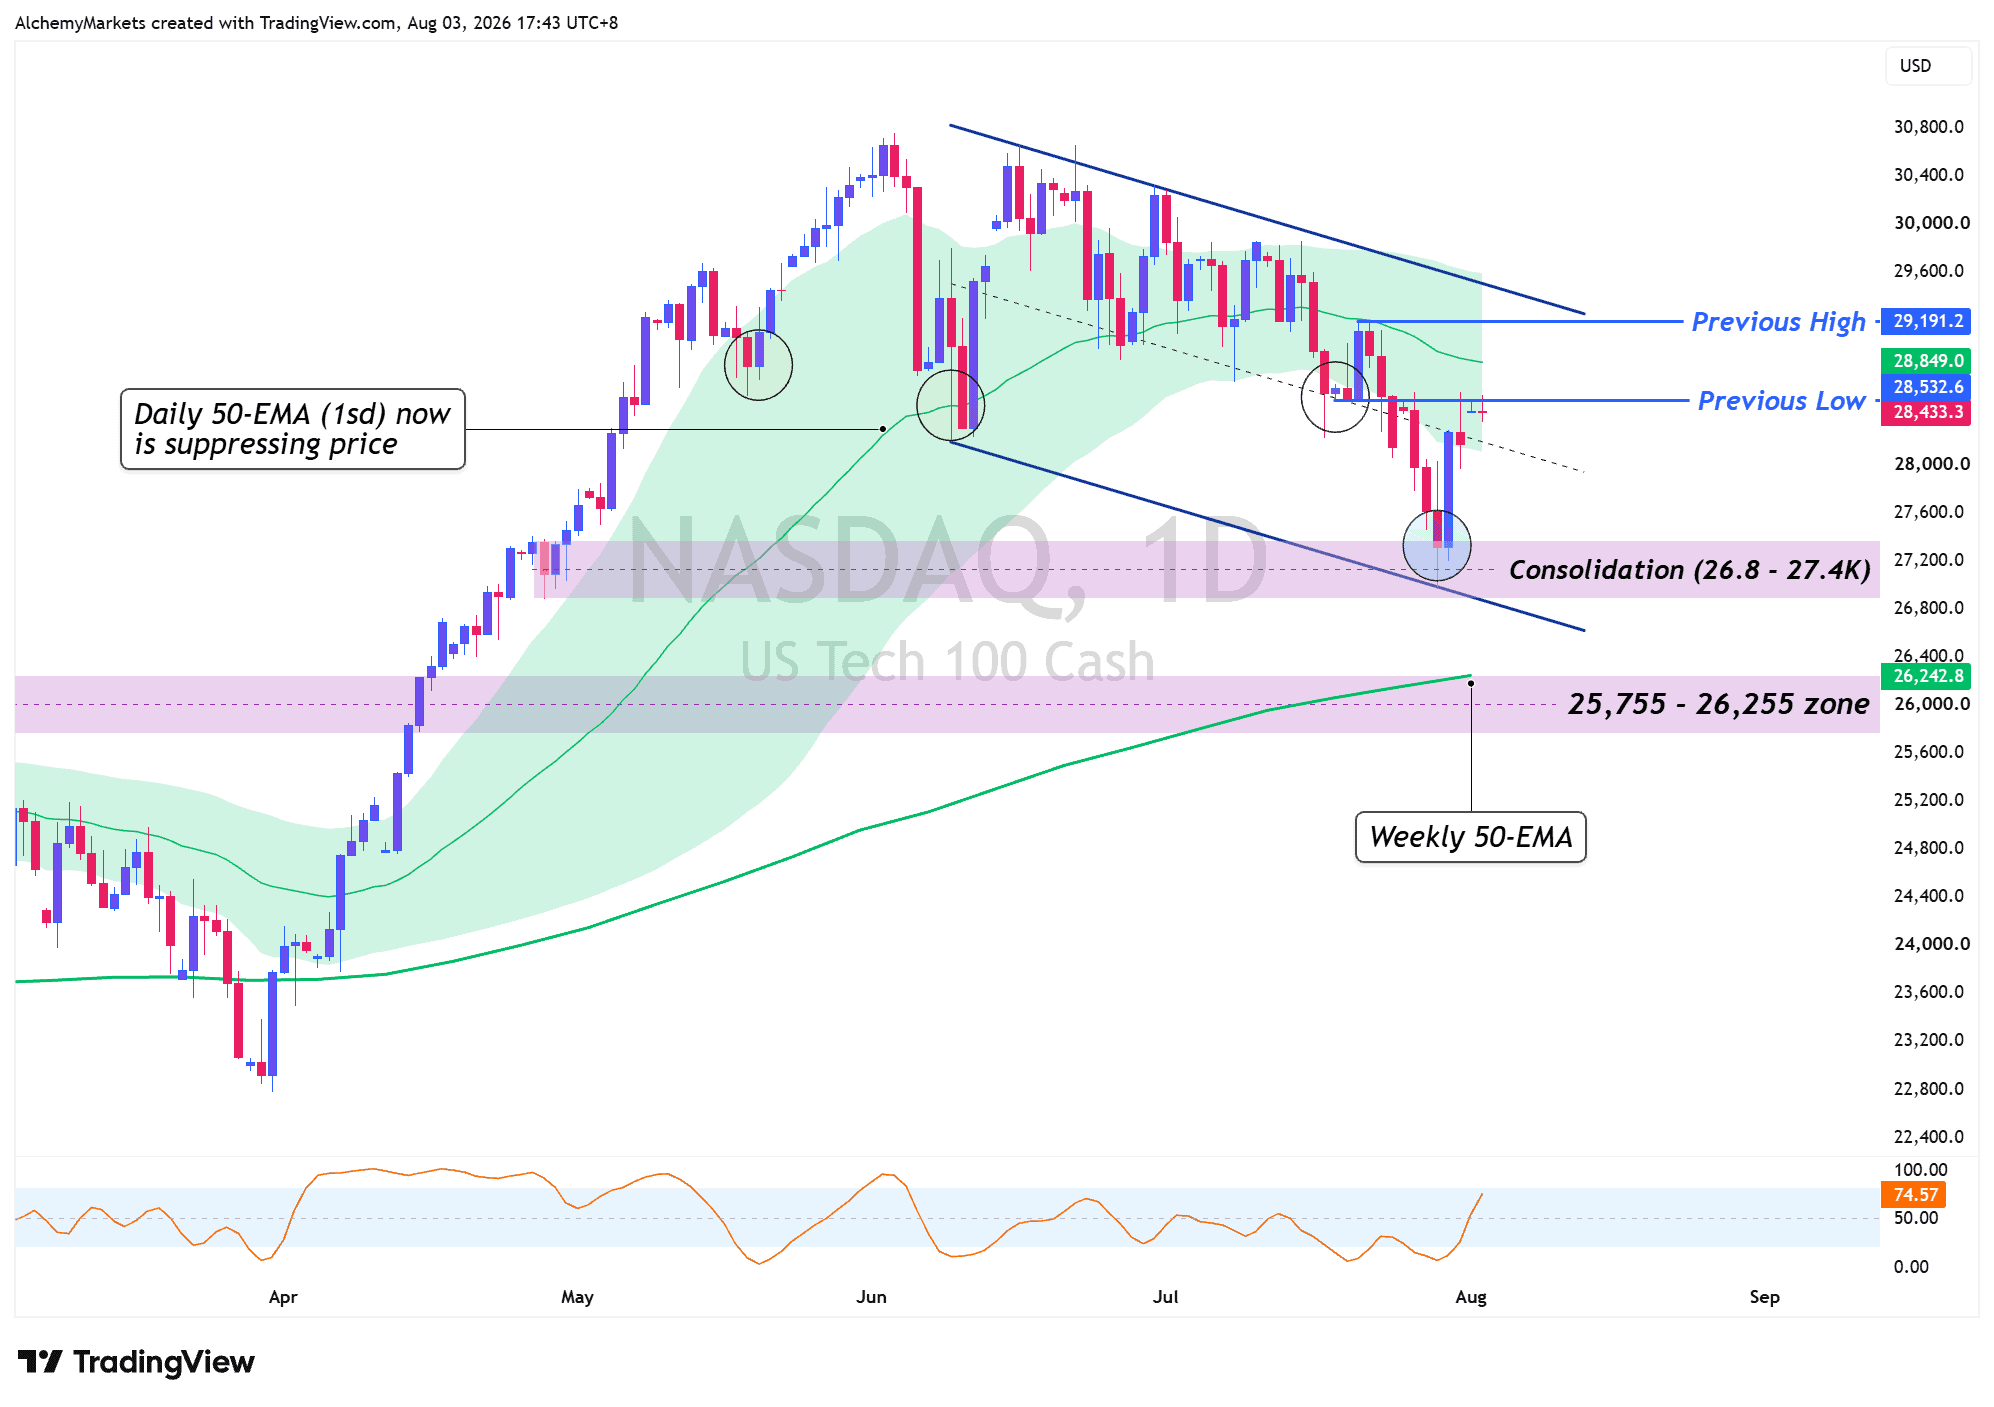
Technology stocks have recovered sharply from last week’s lows. The Nasdaq rose roughly 5.4% from the 26,800 area, while the S&P 500 returned above its rising trendline after testing the value-area low near 7,314.
The VIX has also fallen from above 20 to around 16, but the rebound now needs confirmation.
The Nasdaq is testing its previous-low area near 28,532 below the daily 50-EMA band (1 standard deviation), while the S&P 500 is approaching the high-volume area around 7,500.
Chart 1. S&P 500 daily: The rebound is testing the Point of Control (red line) at $7,500 as resistance, after bouncing off the VAL (blue line) and reclaiming a trendline support. VIX has tapered off from 20
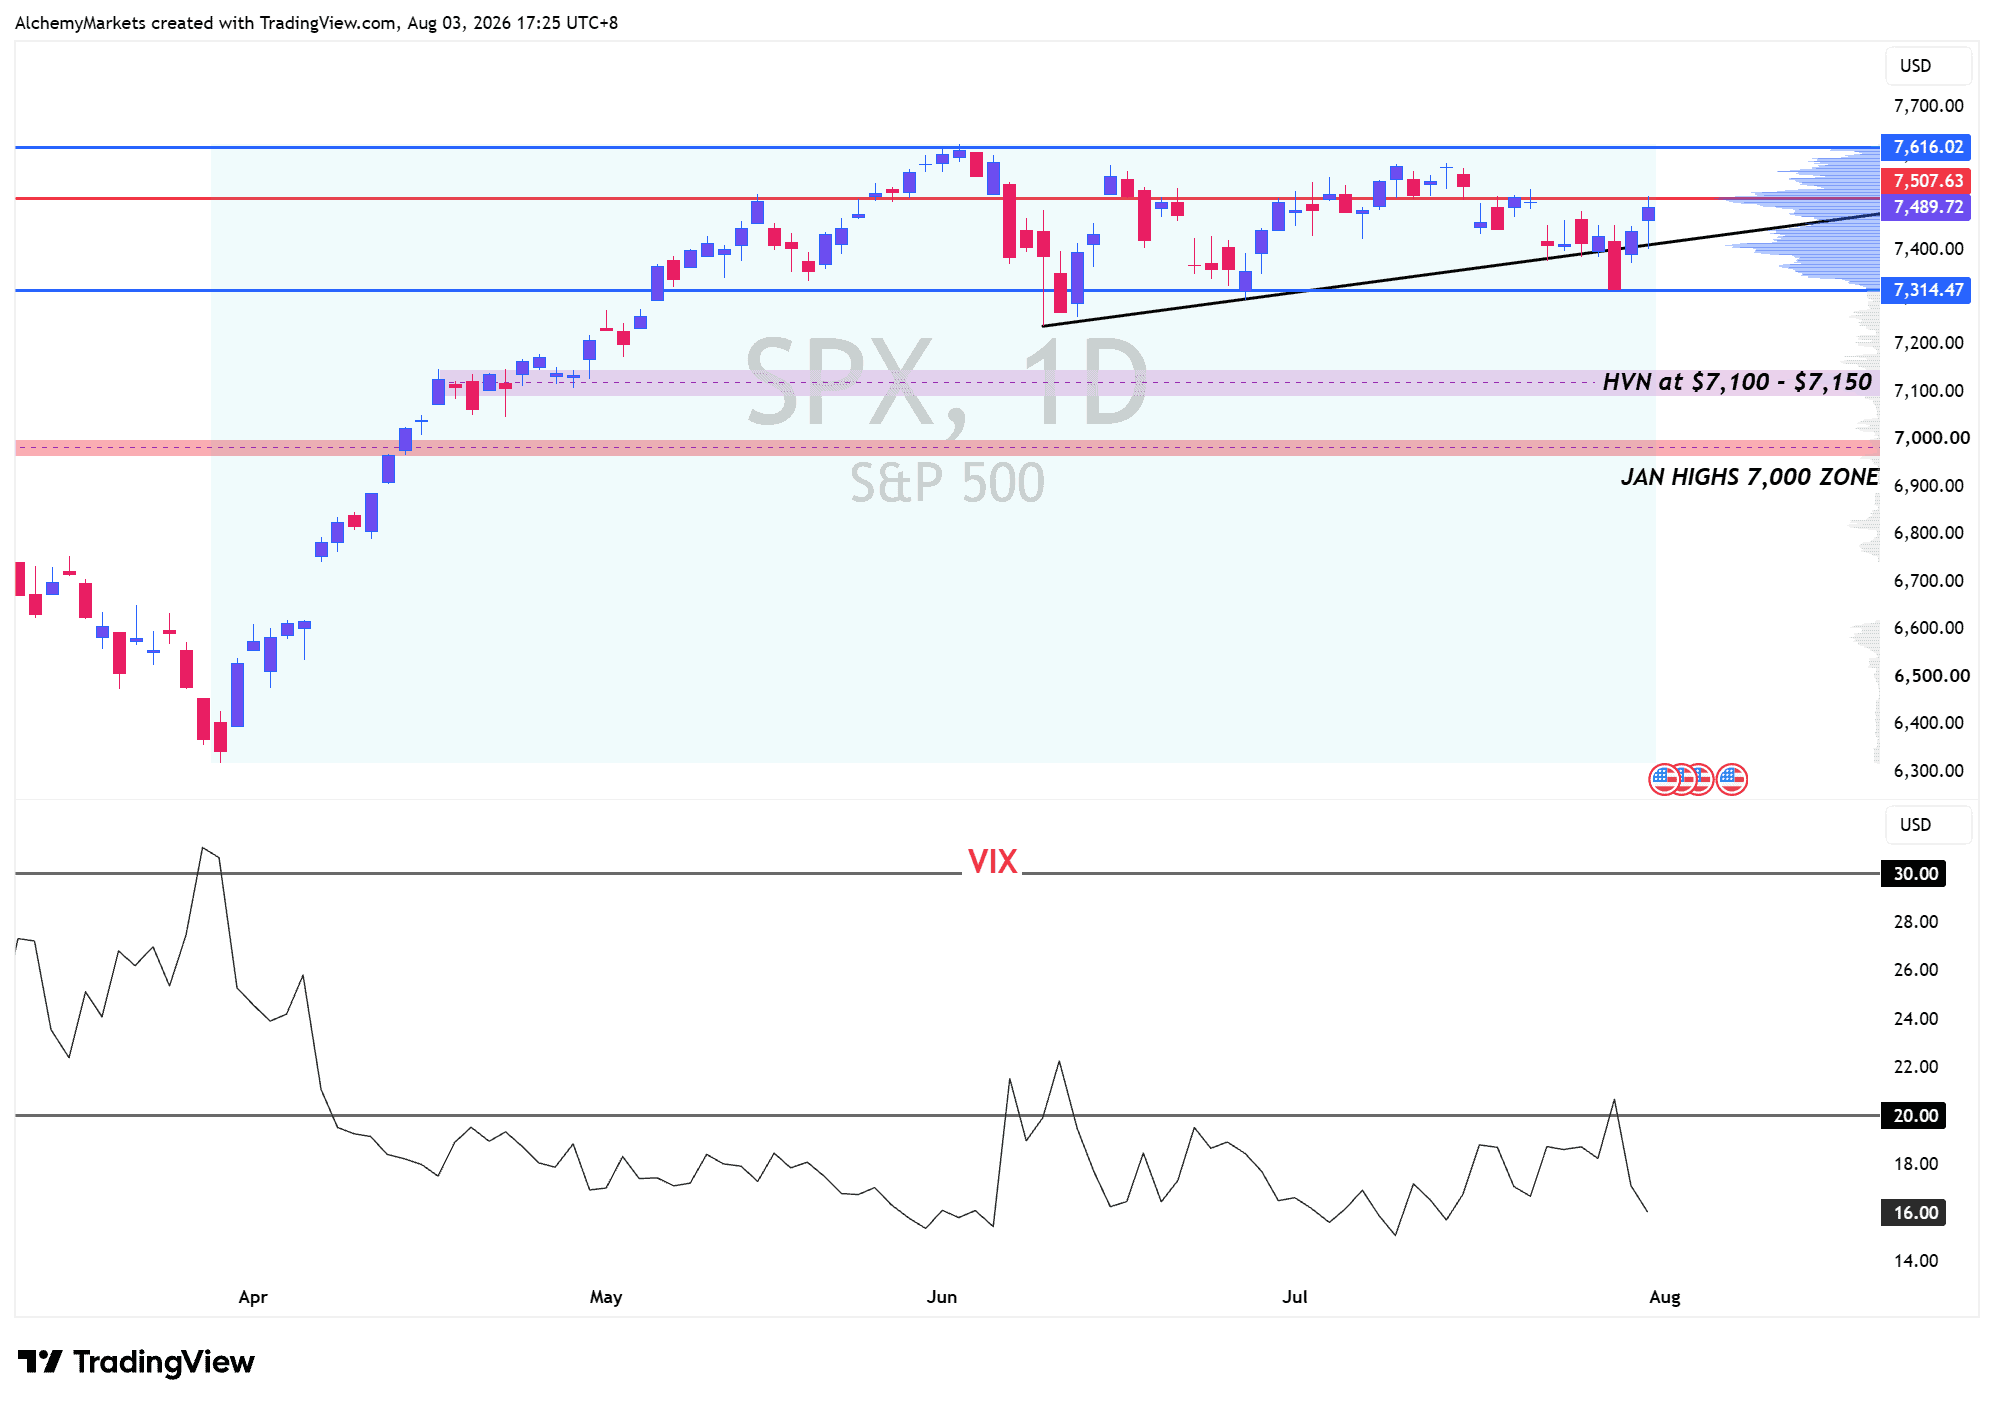
Chart 2. Nasdaq daily: The rebound is testing the previous low and daily 50-EMA band
Several tests can change the move this week
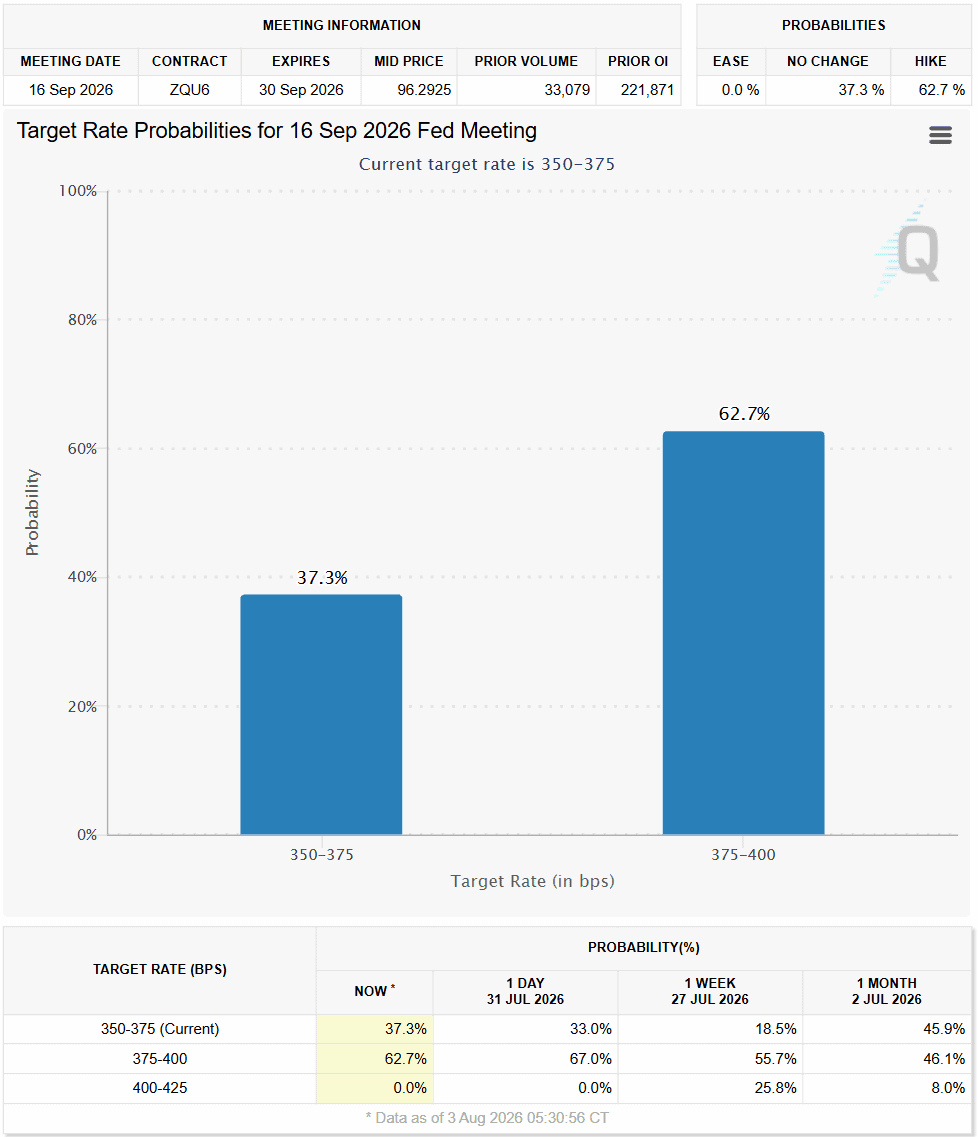
The Federal Reserve held rates at 3.50%-3.75% on 29 July, but three voters preferred a 25-basis-point increase.
That leaves technology shares sensitive to any data that pushes yields higher.
Day | Event | Why markets care |
Monday | ISM Manufacturing | Demand and prices can move yields. |
Tuesday | JOLTS and AMD | Labour data and the main chip test. |
Wednesday | ISM Services | Broader demand and price pressure. |
Friday | US jobs report | Payrolls and wages shape Fed pricing. |
Together, these releases will confirm whether yields continue falling, or whether stronger growth and inflation sustain expectations for a September rate increase.
Currently, the September expectation sits at 62.7% for a 25bps hike, which is going to have a suppressive effect on equities (if earnings don’t outperform and capex concerns aren’t addressed), Gold and Silver.
Cheaper Oil removed one immediate pressure
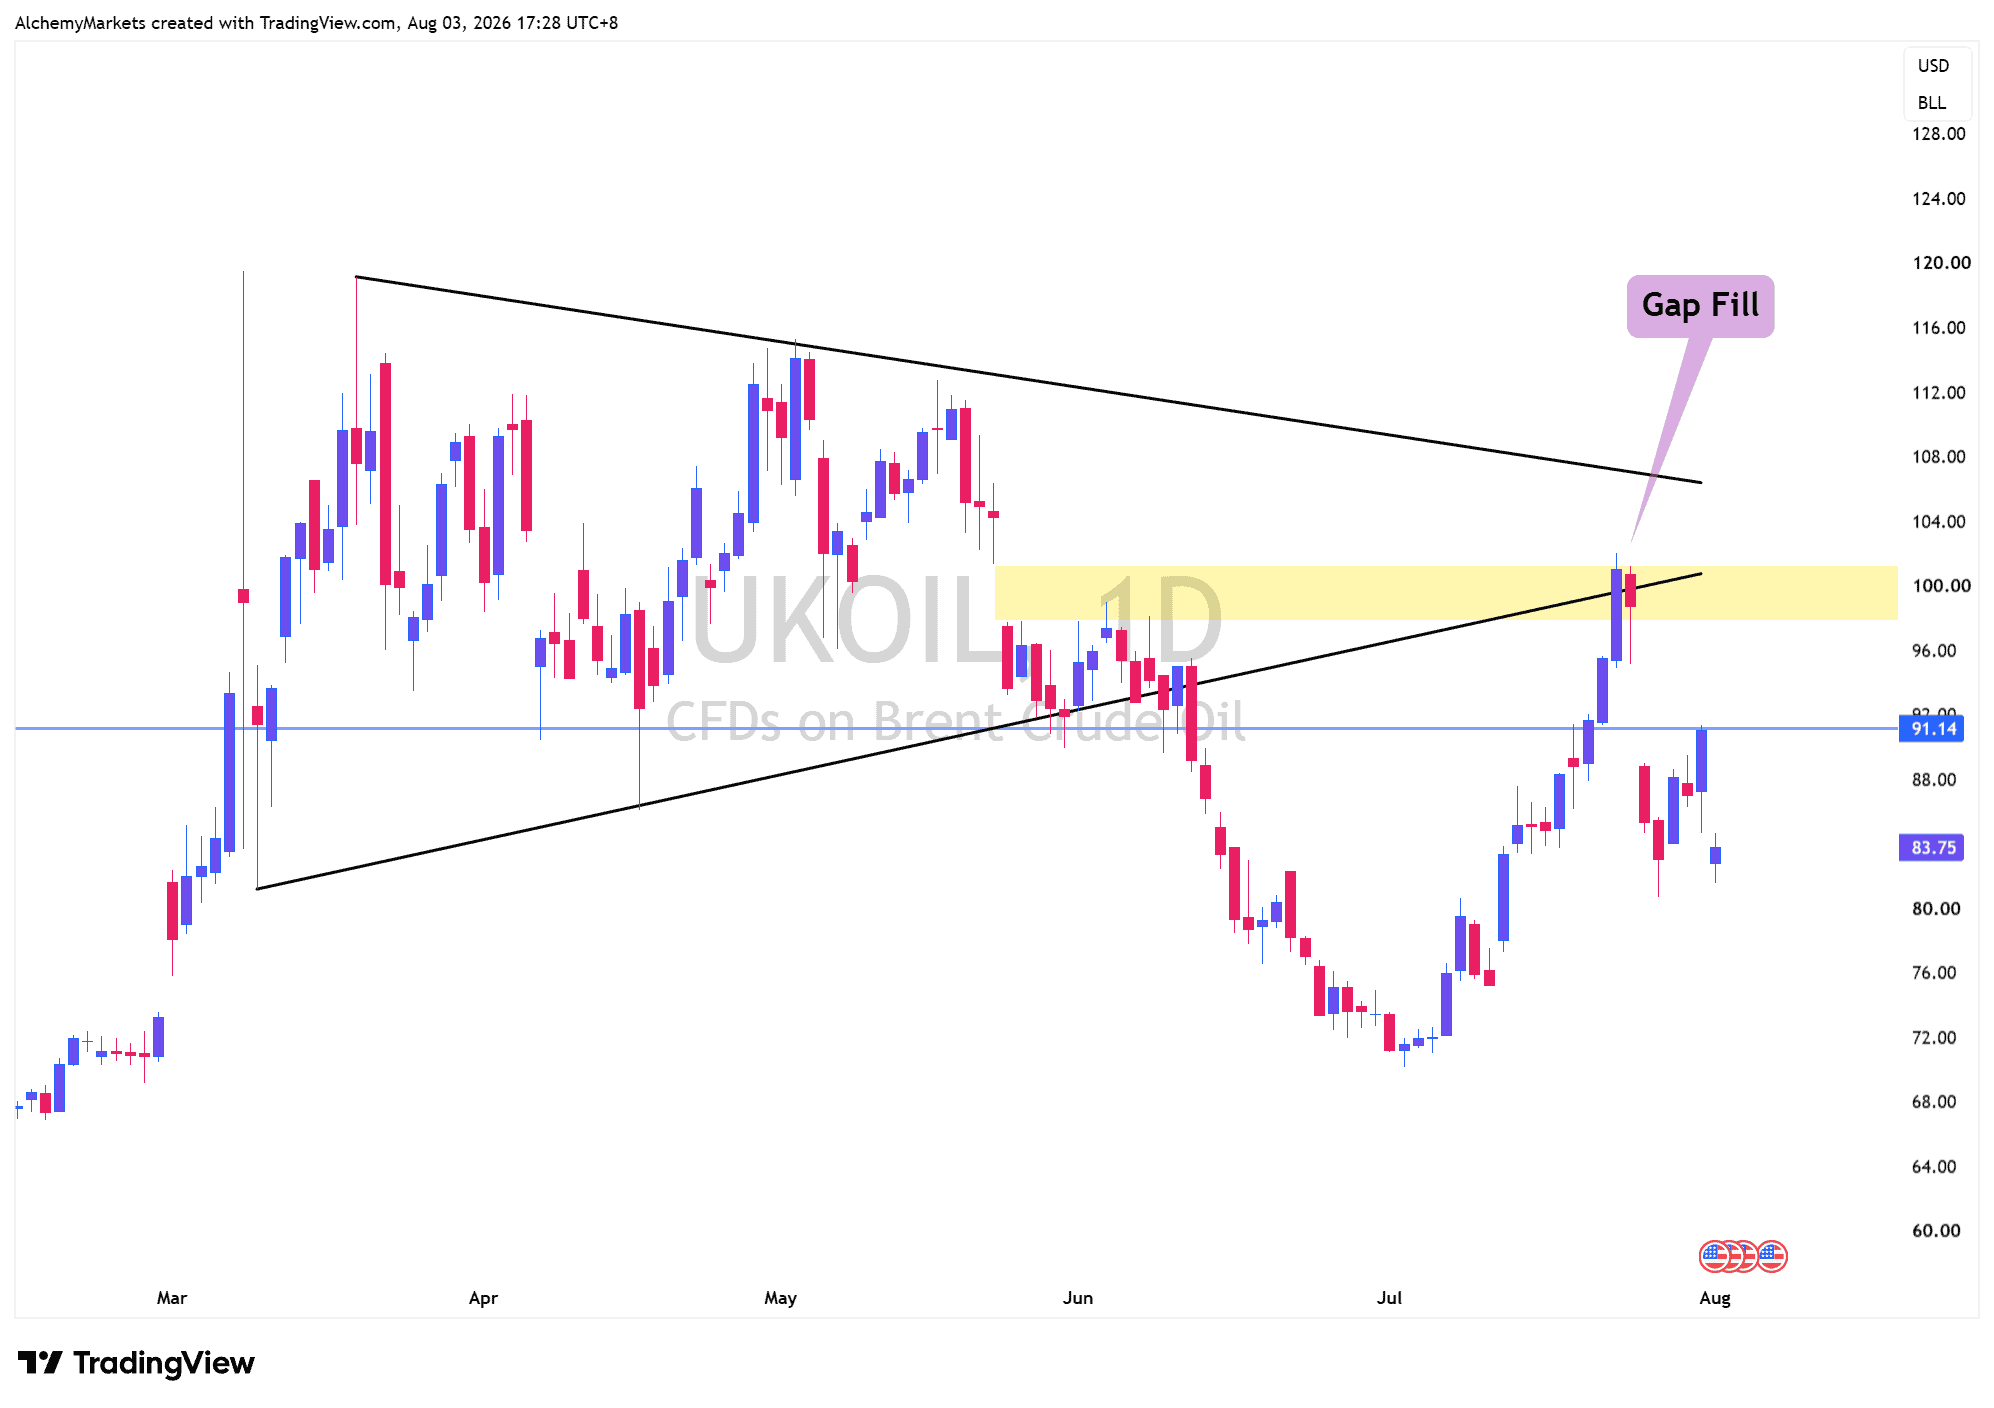
Brent crude gapped lower after another rejection from the $98-$101 area. The move followed Trump’s decision to delay further strikes on Iran while diplomatic discussions continued, reducing the immediate risk of another disruption to energy supplies.
Lower oil reduces headline inflation pressure, can pull Treasury yields lower and eases the discount-rate pressure on expensive technology shares.
June CPI fell 0.4% from May and core CPI was unchanged as energy dropped 5.7%. Producer prices also fell 0.3%, although annual final-demand PPI remained high at 5.5%, showing that one month of energy relief has not removed upstream inflation.
However, the move still depends on political expectations. Iran denied that direct US talks were under way, while shipping through Hormuz has not returned to normal. Until oil remains lower and physical conditions improve, this is relief rather than confirmation of lasting de-escalation.
Chart 3. Brent daily: The market rejected the gap-fill area and gapped lower, but the geopolitical path remains conditional
ISM can make good data bad for technology
Consensus expects the July Manufacturing PMI near 54.0, up from 53.3. The headline matters, but the mix matters more because stronger activity can hurt technology if it also lifts inflation and yields.
June New Orders were 56.0, while Employment remained in contraction at 49.7. Prices stayed high at 73.0 and Supplier Deliveries at 57.4 showed continued delays. ISM linked the price pressure to petroleum products, tariffs, steel and aluminium, and noted that readings above 52.8 have historically aligned with rising intermediate-material PPI.
ISM combination | Likely technology-market read |
Stronger demand + lower prices | Best outcome for technology. Growth holds while yields have less reason to rise. |
Stronger demand + higher prices | Good activity can become bad market news by increasing Fed hike risk. |
Weaker demand + lower prices | Yields may fall, but earnings expectations can weaken. |
Weaker demand + higher prices | The most difficult mix: softer growth with persistent inflation. |
AMD is the fundamental validation
AMD reports after Tuesday’s close. Its previous guidance called for revenue of approximately $11.2 billion, plus or minus $300 million, equal to about 46% annual growth at the midpoint, with non-GAAP gross margin near 56%.
The benchmark is demanding. First-quarter Data Center revenue rose 57% to $5.8 billion and segment operating income increased to $1.6 billion from $932 million. The main test is whether AI accelerator and server demand can support stronger guidance, margin and operating leverage as research spending rises.
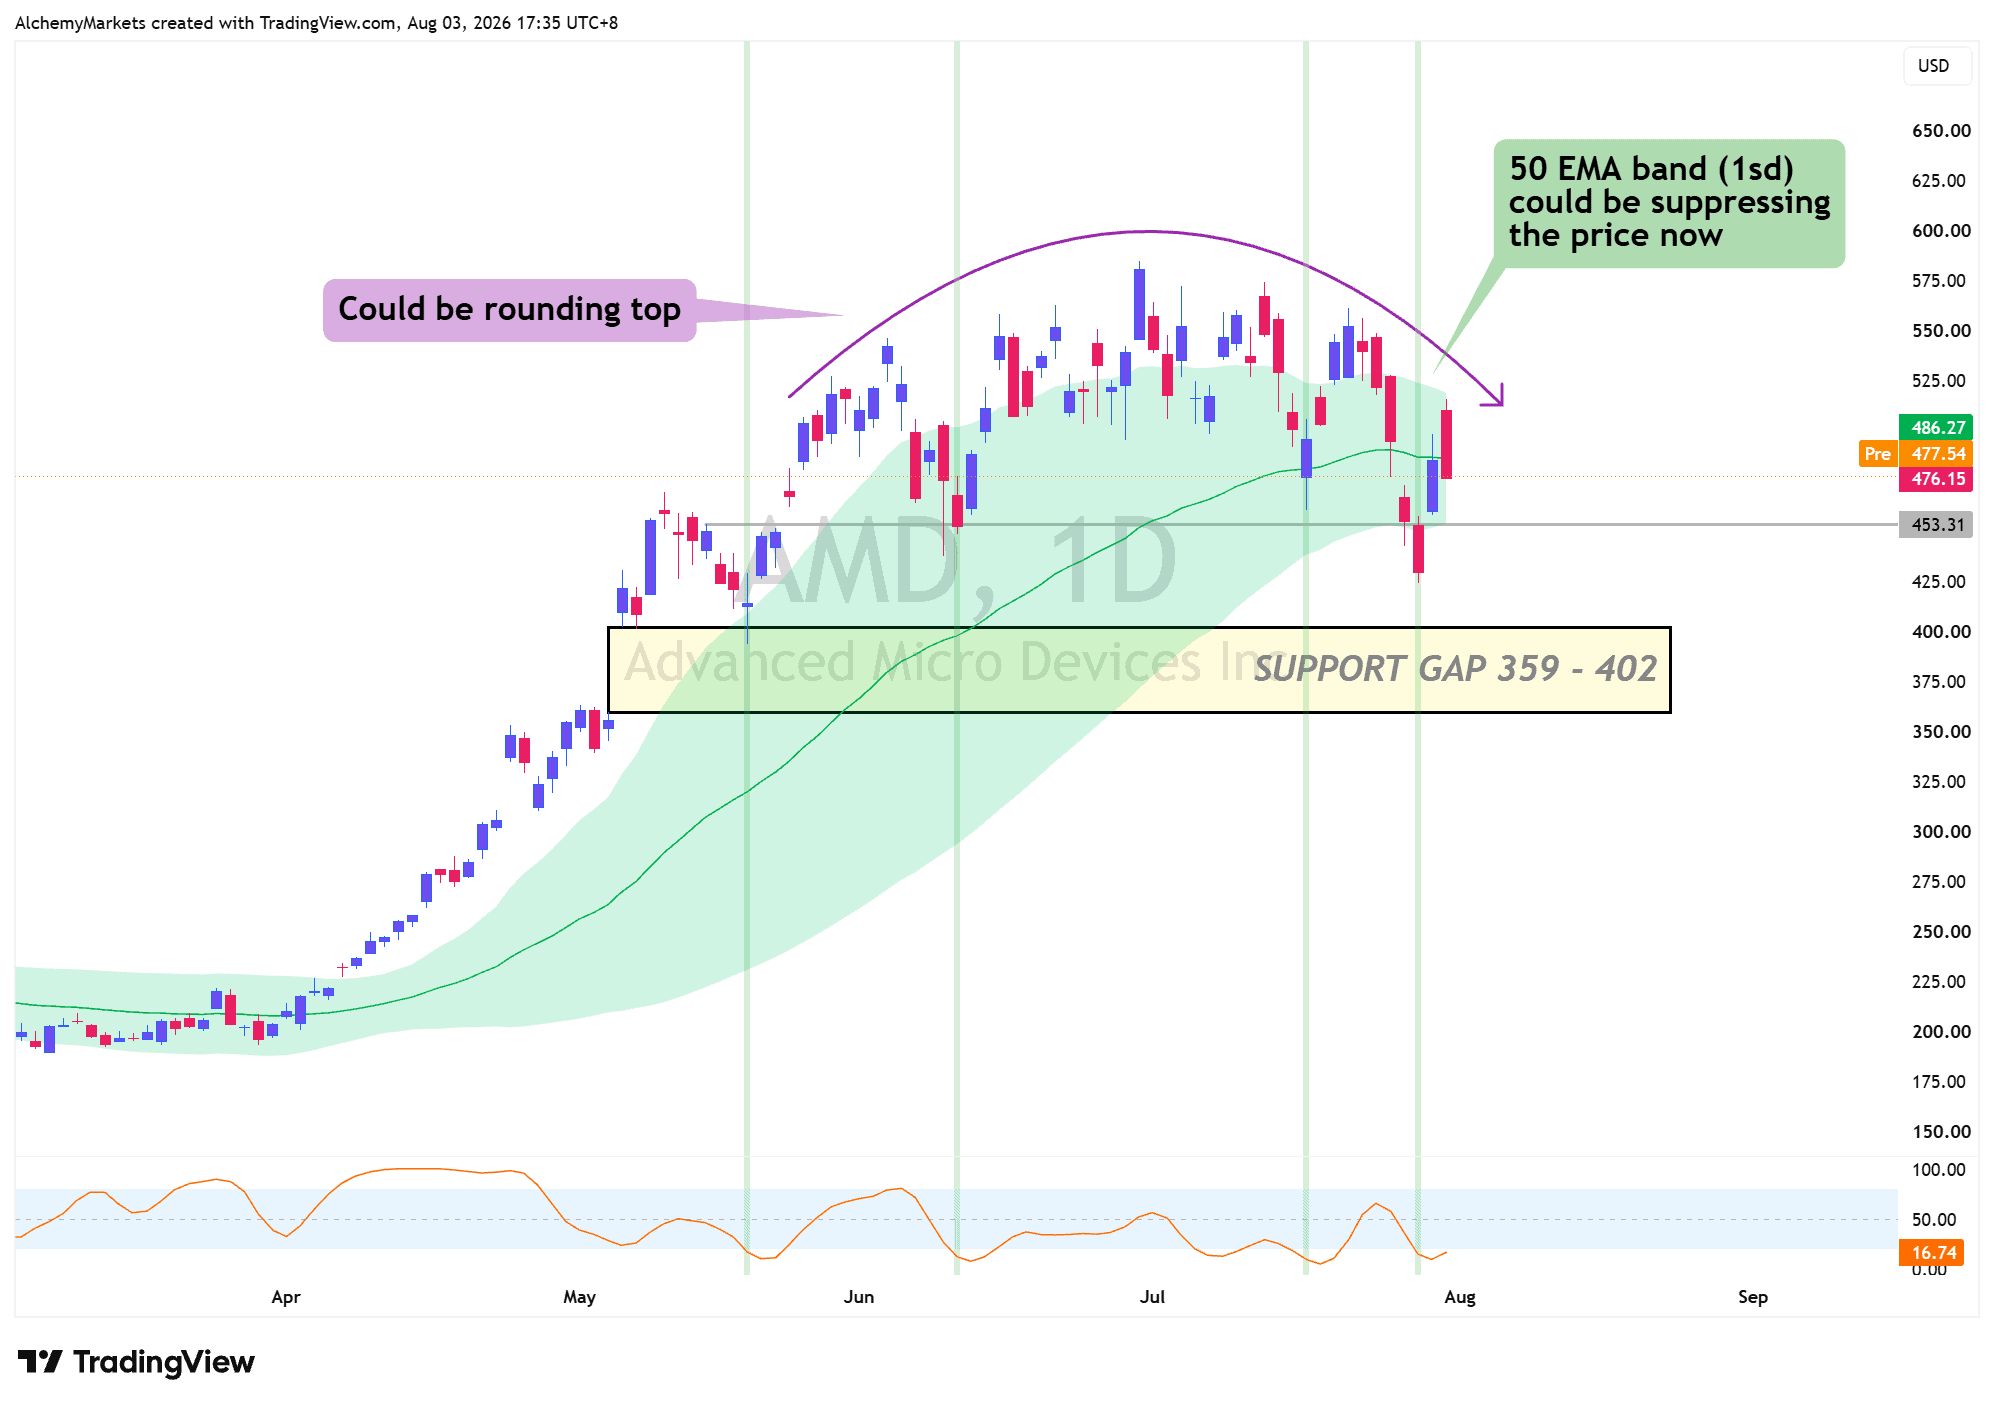
AMD remains below its daily 50-EMA band with possible rounded resistance overhead. A sustained reclaim would support the semiconductor rebound; another rejection would expose the $453 area and potentially the deeper $359-$402 support gap.
Chart 4. AMD daily: earnings must clear the daily 50-EMA band
Can the rebound hold?
The rebound has repaired some of the technical damage, but it has also relied on falling oil, yields and volatility.
ISM will test whether inflation pressure is easing, while AMD will test whether AI demand can support the semiconductor recovery.
Until the Nasdaq reclaims its daily 50-EMA band, this move remains a short term rally rather than a confirmed reversal.
Author

Zorrays Junaid
Alchemy Markets
Zorrays Junaid has extensive combined experience in the financial markets as a portfolio manager and trading coach. More recently, he is an Analyst with Alchemy Markets, and has contributed to DailyFX and Elliott Wave Forecast in the past.
















