Australian Dollar Price Forecast: (Not) all the roads lead to 0.7000
- AUD/USD fades Monday’s pessimism and trades with decent gains.
- The US Dollar resumes its decline ahead of Wednesday’s US CPI data.
- The RBA still sees inflation as stubbornly elevated, the Minutes said.
The Australian Dollar (AUD) has rapidly regained composure on Wednesday, prompting AUD/USD to trade with decent gains and come close to the key 0.7000 threshold, although a test of it remains elusive for now.
The resumption of the upward trend in the pair comes in tandem with a marked pullback in the US Dollar (USD) amid a generalised improvement in sentiment surrounding the broader risk-linked galaxy.
Adding to the above, tensions in the Middle East appear somewhat (temporarily?) alleviated, while the recovery in crude oil prices seems far from abated.
Looking at the broader picture, spot remains vulnerable to further losses as long as it continues to trade below its 200-day SMA near 0.7040. However, the Reserve Bank of Australia’s (RBA) hawkish policy stance, in combination with still elevated domestic inflation, should cushion against any deep and sustained corrections…for now.
Australia’s resilience meets signs of slowing momentum
Australia’s economy continues to compare favourably with many of its G10 peers, supported by domestic demand and positive economic growth. Persistent inflation also supports the RBA’s cautious, data-dependent policy stance.
However, business activity seems to have lost some momentum after final data showed the Purchasing Managers’ Index (PMI) for Manufacturing cooling to 49.6 in September and easing to 51.9 when it comes to Services, from 52.0 and 53.2, respectively.
Trade data provided another positive, albeit humble, signal after August’s trade surplus came in at just A$0.495 billion, adding to the A$1.351 billion surplus registered in the previous month (revised from A$1.923 billion).
Growth figures were less encouraging, however. Indeed, the Gross Domestic Product (GDP) expanded by 0.4% QoQ in the second quarter of 2026, up from 0.3%, while annual growth came in at 2.1%, down from the previous 2.5% yearly expansion.
The labour market also showed mixed signs in August, with the Unemployment Rate rising to 4.6% and Employment Change increasing by 39.5K, reversing July’s nearly 16K drop.
Inflation seems to have lost some impulse after the most-watched Trimmed Mean came in at 3.6% over the last twelve months, despite the headline CPI ticking higher to 4.0% from a year earlier.
The Melbourne Institute’s Consumer Inflation Expectations measure reinforced those figures after ticking higher to 5.3% in October.
The figures leave the RBA’s inflation task incomplete. Policymakers expect inflation to return to target only in early 2028, keeping the emphasis on patience rather than an imminent policy pivot.
China offers stability, but little fuel for the Aussie
China is providing stability for the Australian economy, but not the growth impulse that has supported the Australian Dollar during previous expansions.
The Chinese economy grew by 4.3% YoY in the April-June period, while Industrial Production growth regained traction, expanding by 5.2% YTD, and the trade surplus widened to $119.1 billion in July, supported by decent increases in both imports and exports. However, on the downside, consumer spending remained sluggish after Retail Sales rose by only 0.4 % from a year earlier.
In addition, business surveys presented a promising picture: the National Bureau of Statistics reported that the Manufacturing PMI improved to 50.1 in September (from 49.8), while the Services PMI improved to 50.2 (from 49.0). In the same direction, private measures like RatingDog remained in expansionary territory, with Manufacturing at 52.1 (from 51.5) and Services at 51.6 (from 51.4).
Disinflationary pressures seem to have taken a breather in August, with the CPI gaining 0.8% YoY, up from 0.5%, while prices rose by 0.4% on a monthly basis. Producer Prices rose by 3.8% over the previous twelve months, down from the 3.5% increase recorded in the previous month.
The People’s Bank of China (PBoC) left its Loan Prime Rates unchanged last month, maintaining the one-year rate at 3.00% and the five-year rate at 3.50%.
China is therefore neither providing a major boost nor creating a significant drag. Unless the data reveal a clearer acceleration or deterioration, its influence on AUD/USD is likely to remain limited.
The RBA hikes again as inflation refuses to cooperate
In a unanimous decision, the RBA hiked its OCR by 25 basis points to 4.60% at its meeting in late September.
The RBA Minutes published earlier on Tuesday show a unanimous vote for more tightening. Indeed, all Board members voted for the 25 basis point rate hike, believing that excess demand was stronger than previously assumed and that the risk of persistently high inflation had increased. Furthermore, policymakers debated whether to hold rates for a moment but decided to take timely action to keep inflation expectations anchored.
Additionally, the RBA highlighted broad domestic cost pressures, higher unit labour costs, elevated oil prices and emerging inflation risks from the AI boom. Some indicators suggested financial conditions were only modestly restrictive, while models implied the neutral rate may have moved higher. The Board also warned that a rise in global neutral rates could weaken the Australian Dollar if domestic rates failed to follow.
Overall, the Minutes were clearly hawkish and leave further tightening firmly on the table, although policymakers remain mindful of falling house prices and the risk of slowing economic activity.
AUD/USD recovery runs into the 200-day SMA
Baseline outlook
The medium-term outlook has somewhat improved since the beginning of the month, as the pair seems to have embarked on a sidelined phase. While below the 200-day SMA, spot should face a steady chance of further declines. Against this backdrop, the resurgence of the downside bias should find initial support at the October floor at 0.6903 (October 1).
The resumption of the bullish bias will likely require a strong catalyst, namely a sustained improvement in risk appetite trends or renewed and persistent US Dollar weakness.
Upside scenario
A stronger risk-on environment should face the initial barrier at the key 0.7000 threshold, just ahead of the 200-day SMA, all preceding the weekly top at 0.7140 (September 21). North from here, a test of the 2026 high near 0.7280 should come into view.
Downside scenario
An additional deterioration in global risk sentiment, persistent strength in the Greenback, or renewed weakness in Chinese data could further fuel the ongoing selling mood.
Initial support is at the October valley of 0.6903 (October 1). A breach below the latter would increase the likelihood of a retest of the June bottom near 0.6860 (June 30).
Positioning turns decisively bearish
AUD bearish positioning accelerated sharply in the week ending October 6, according to the Commodity Futures Trading Commission (CFTC) data. That said, the net speculative positioning increased to nearly 98.6K contracts, extending the previous week’s deterioration. The four-week change accelerated to just over 63.7K contracts, confirming a powerful and rapidly intensifying bearish trend.
Additionally, open interest increased markedly to around 328.7K contracts. The move suggests that new shorts are being established as net shorts deepen along with higher participation, rather than a simple liquidation of existing longs. This suggests that conviction behind the negative AUD view has increased materially.
Further data showed speculative exposure fell to -30%, although its percentile declined to 47.1, indicating that exposure relative to open interest is not historically extreme. The Net Position Percentile, however, collapsed to 1.9 from 33.7, showing that the outright net-short position is now exceptionally bearish by historical standards.
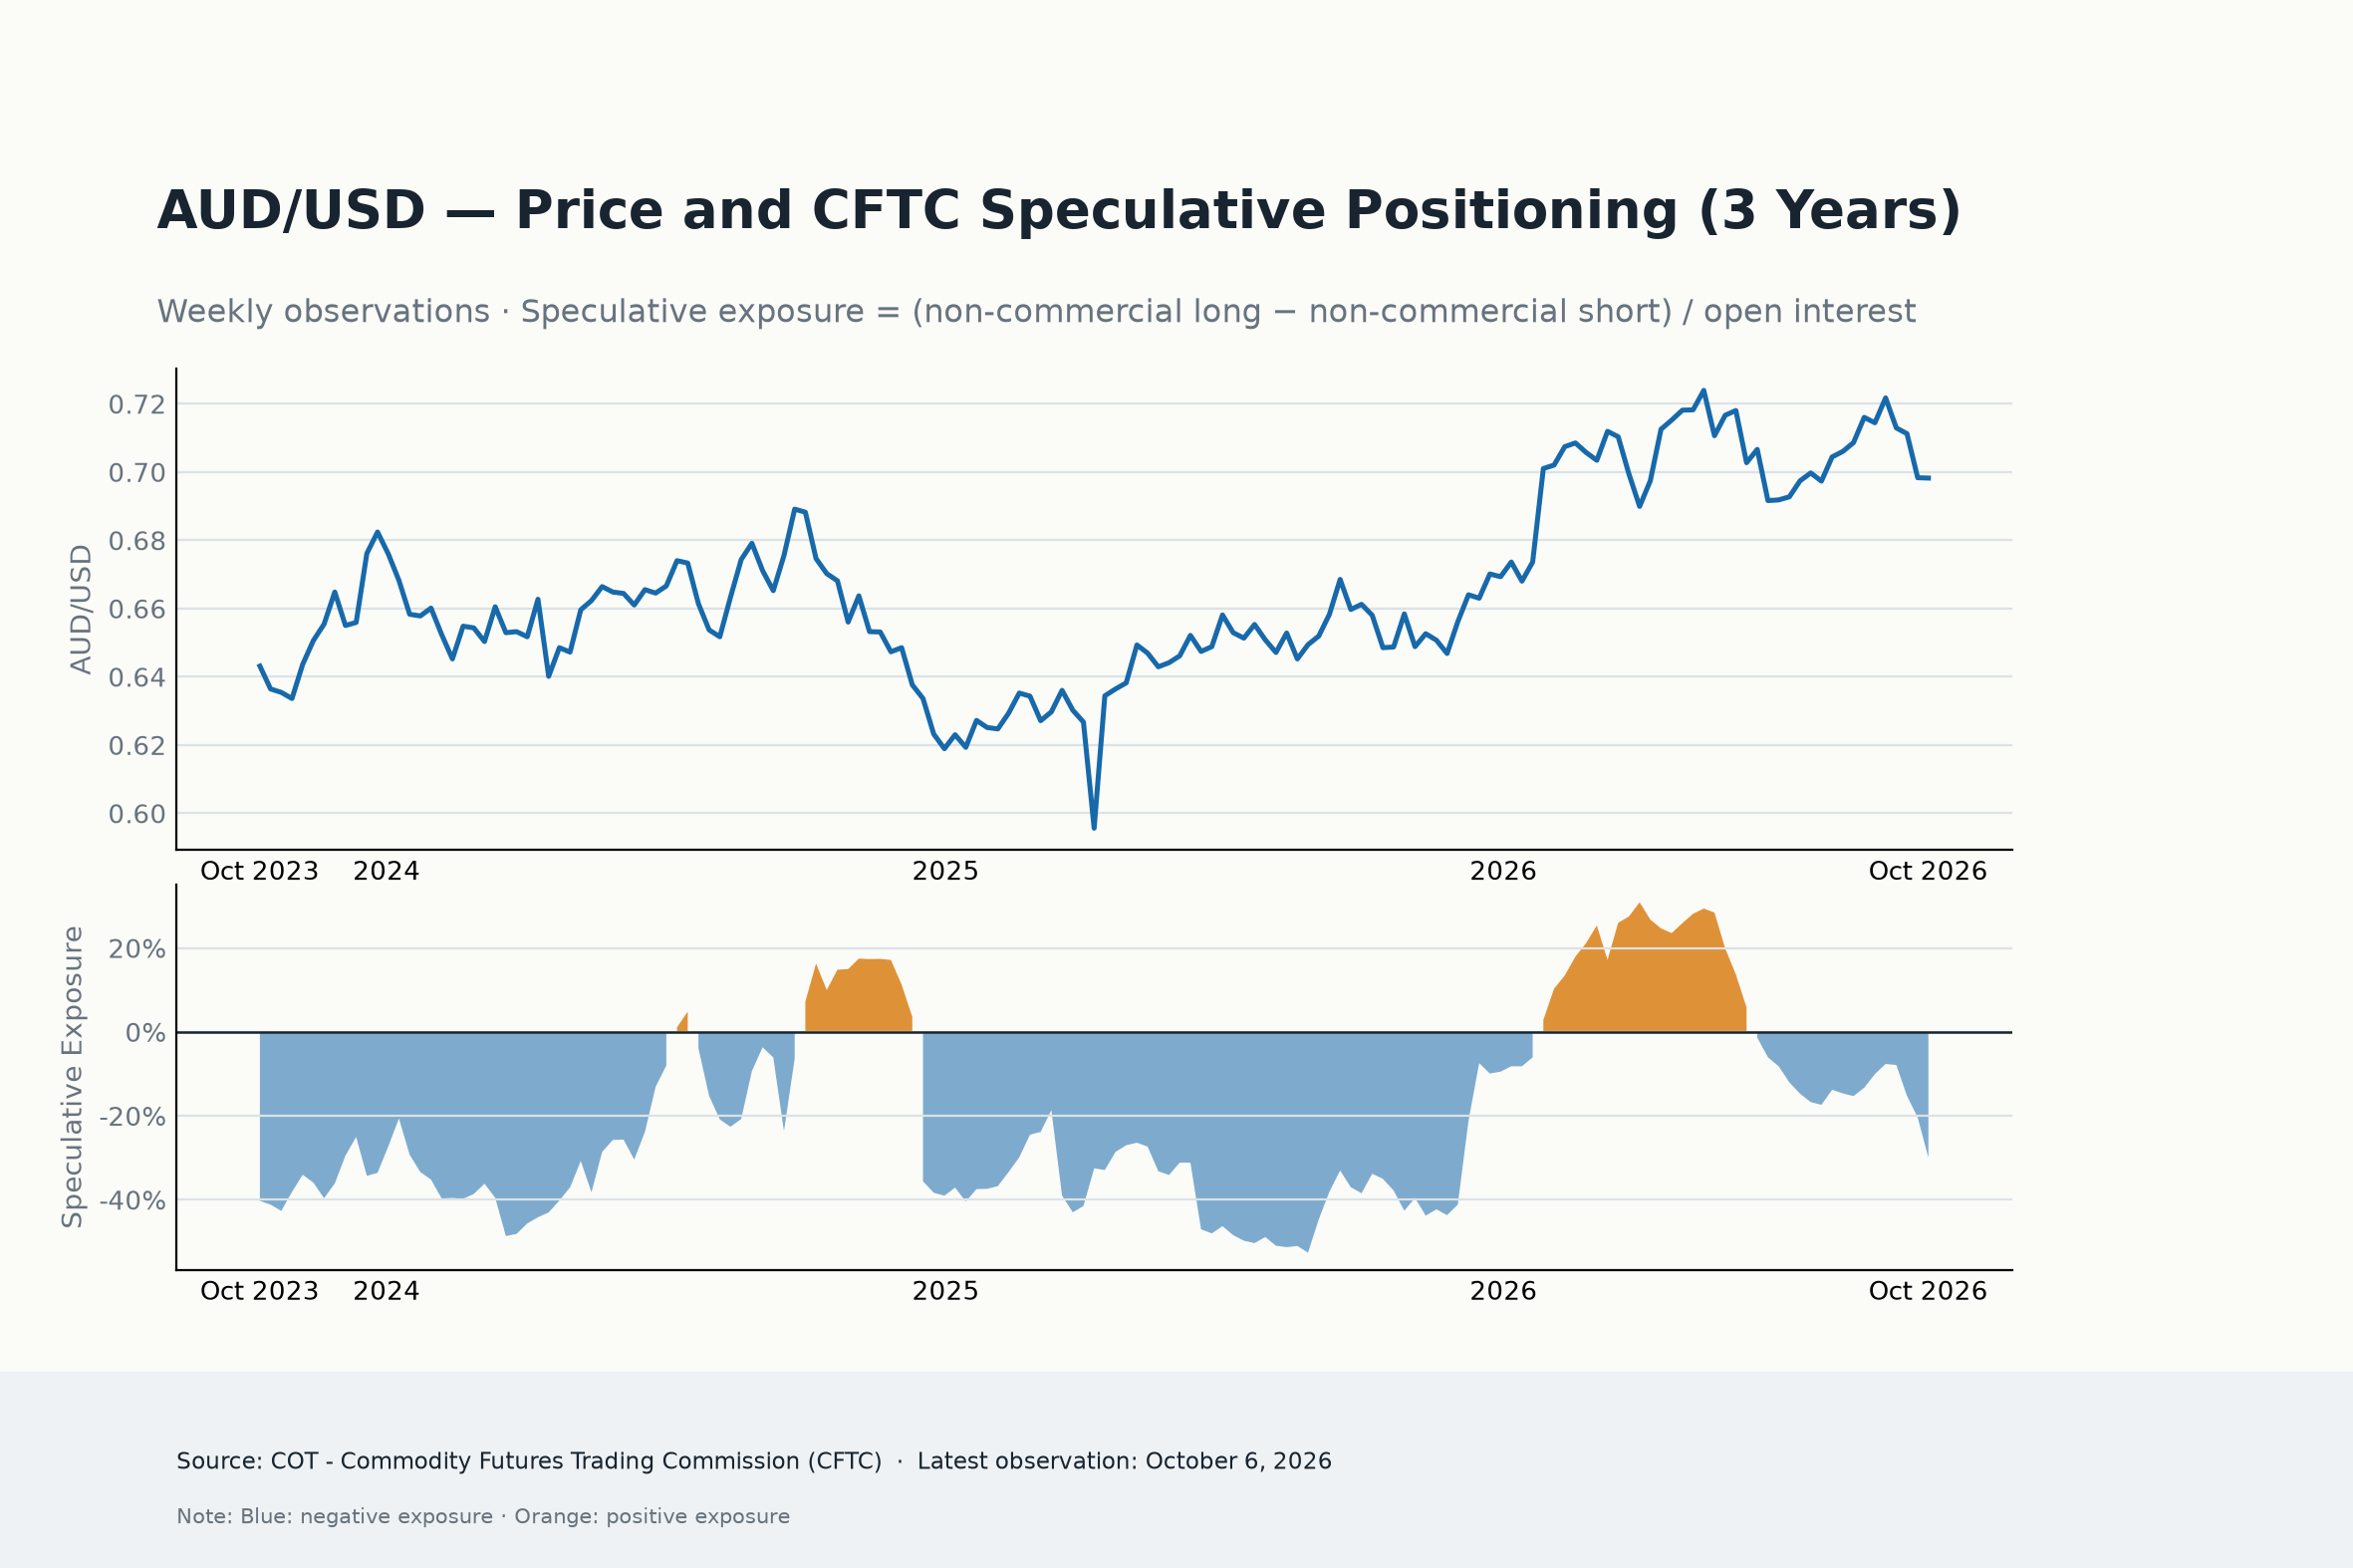
All up, the AUD positioning signal has turned decisively negative with both weekly and four-week momentum pointing lower. Further downside remains possible while fresh shorts continue to accumulate, although the extremely low Net Position Percentile also raises the risk of a sharp short-covering rebound if the macro backdrop improves or bearish momentum begins to fade.
What’s next for AUD/USD?
US Dollar dynamics, global risk sentiment, and geopolitical developments remain the main near-term drivers of AUD/USD.
In the meantime, the next data release note on the domestic calendar will be the publication of the Leading Index tracked by Westpac. However, the release of US CPI data and Chinese inflation figures alongside Balance of Trade results is also expected to be closely monitored.
Beyond the immediate releases, the main risks include a sharper slowdown in China, a persistently cautious Fed, a deterioration in investor risk appetite or a change in the RBA’s current policy stance. Any of these developments could quickly alter the outlook for the Australian Dollar.
Technical analysis
In the daily chart, AUD/USD trades at 0.6979, keeping a bearish near-term tone as spot holds below the 200-day and 100-day simple moving averages (SMAs) at 0.7040 and 0.7045, as well as the 55-day SMA at 0.7080. The Relative Strength Index (14) sits around 41, hinting at lingering downside pressure, while the elevated Average Directional Index (14) near 41 suggests the current downtrend remains relatively robust.
On the topside, initial resistance is clustered around the 200-day and 100-day SMAs between 0.7040 and 0.7045, ahead of the horizontal barrier at 0.7079 and the 55-day SMA at 0.7080. Further up, a heavier supply zone emerges at 0.7278/0.7283, with a major resistance level at 0.7661. On the downside, immediate support is seen at the horizontal line near 0.6833, followed by deeper floors at 0.6660 and 0.6593, while 0.6414 and 0.6373 mark more distant structural supports if selling pressure extends.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Domestic support, external pressure: AUD caught in the middle
Some dark clouds continue to hover around the AUD’s near-term outlook.
Australia’s domestic backdrop compares favourably with that of many advanced economies, and the RBA is in no hurry to abandon its hawkish stance. These factors should somewhat contain the bearish impulse.
The recovery nevertheless remains vulnerable to renewed strength in the Greenback, persistent geopolitical uncertainty and a Chinese economy that is stabilising rather than accelerating.
The 200-day SMA remains the key level for the medium-term outlook. Holding above it preserves the constructive structure, but a convincing break above 0.7200 is necessary to further extend the bull run.
However, such a move would require the resumption of the downward trend in the Greenback, stronger demand for risk-sensitive assets, additional cooling in US inflation, or a (less likely) dovish shift from the Fed.
Until then, external forces are likely to exert more influence over the Australian Dollar than domestic fundamentals.
RBA FAQs
The Reserve Bank of Australia (RBA) sets interest rates and manages monetary policy for Australia. Decisions are made by a board of governors at 11 meetings a year and ad hoc emergency meetings as required. The RBA’s primary mandate is to maintain price stability, which means an inflation rate of 2-3%, but also “..to contribute to the stability of the currency, full employment, and the economic prosperity and welfare of the Australian people.” Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will strengthen the Australian Dollar (AUD) and vice versa. Other RBA tools include quantitative easing and tightening.
While inflation had always traditionally been thought of as a negative factor for currencies since it lowers the value of money in general, the opposite has actually been the case in modern times with the relaxation of cross-border capital controls. Moderately higher inflation now tends to lead central banks to put up their interest rates, which in turn has the effect of attracting more capital inflows from global investors seeking a lucrative place to keep their money. This increases demand for the local currency, which in the case of Australia is the Aussie Dollar.
Macroeconomic data gauges the health of an economy and can have an impact on the value of its currency. Investors prefer to invest their capital in economies that are safe and growing rather than precarious and shrinking. Greater capital inflows increase the aggregate demand and value of the domestic currency. Classic indicators, such as GDP, Manufacturing and Services PMIs, employment, and consumer sentiment surveys can influence AUD. A strong economy may encourage the Reserve Bank of Australia to put up interest rates, also supporting AUD.
Quantitative Easing (QE) is a tool used in extreme situations when lowering interest rates is not enough to restore the flow of credit in the economy. QE is the process by which the Reserve Bank of Australia (RBA) prints Australian Dollars (AUD) for the purpose of buying assets – usually government or corporate bonds – from financial institutions, thereby providing them with much-needed liquidity. QE usually results in a weaker AUD.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Reserve Bank of Australia (RBA) purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the RBA stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It would be positive (or bullish) for the Australian Dollar.
Author

Pablo Piovano
FXStreet
Born and bred in Argentina, Pablo has been carrying on with his passion for FX markets and trading since his first college years.

















