Mark Belinski of ARKBRIDGE: 22 years in markets and the investment infrastructure behind AI
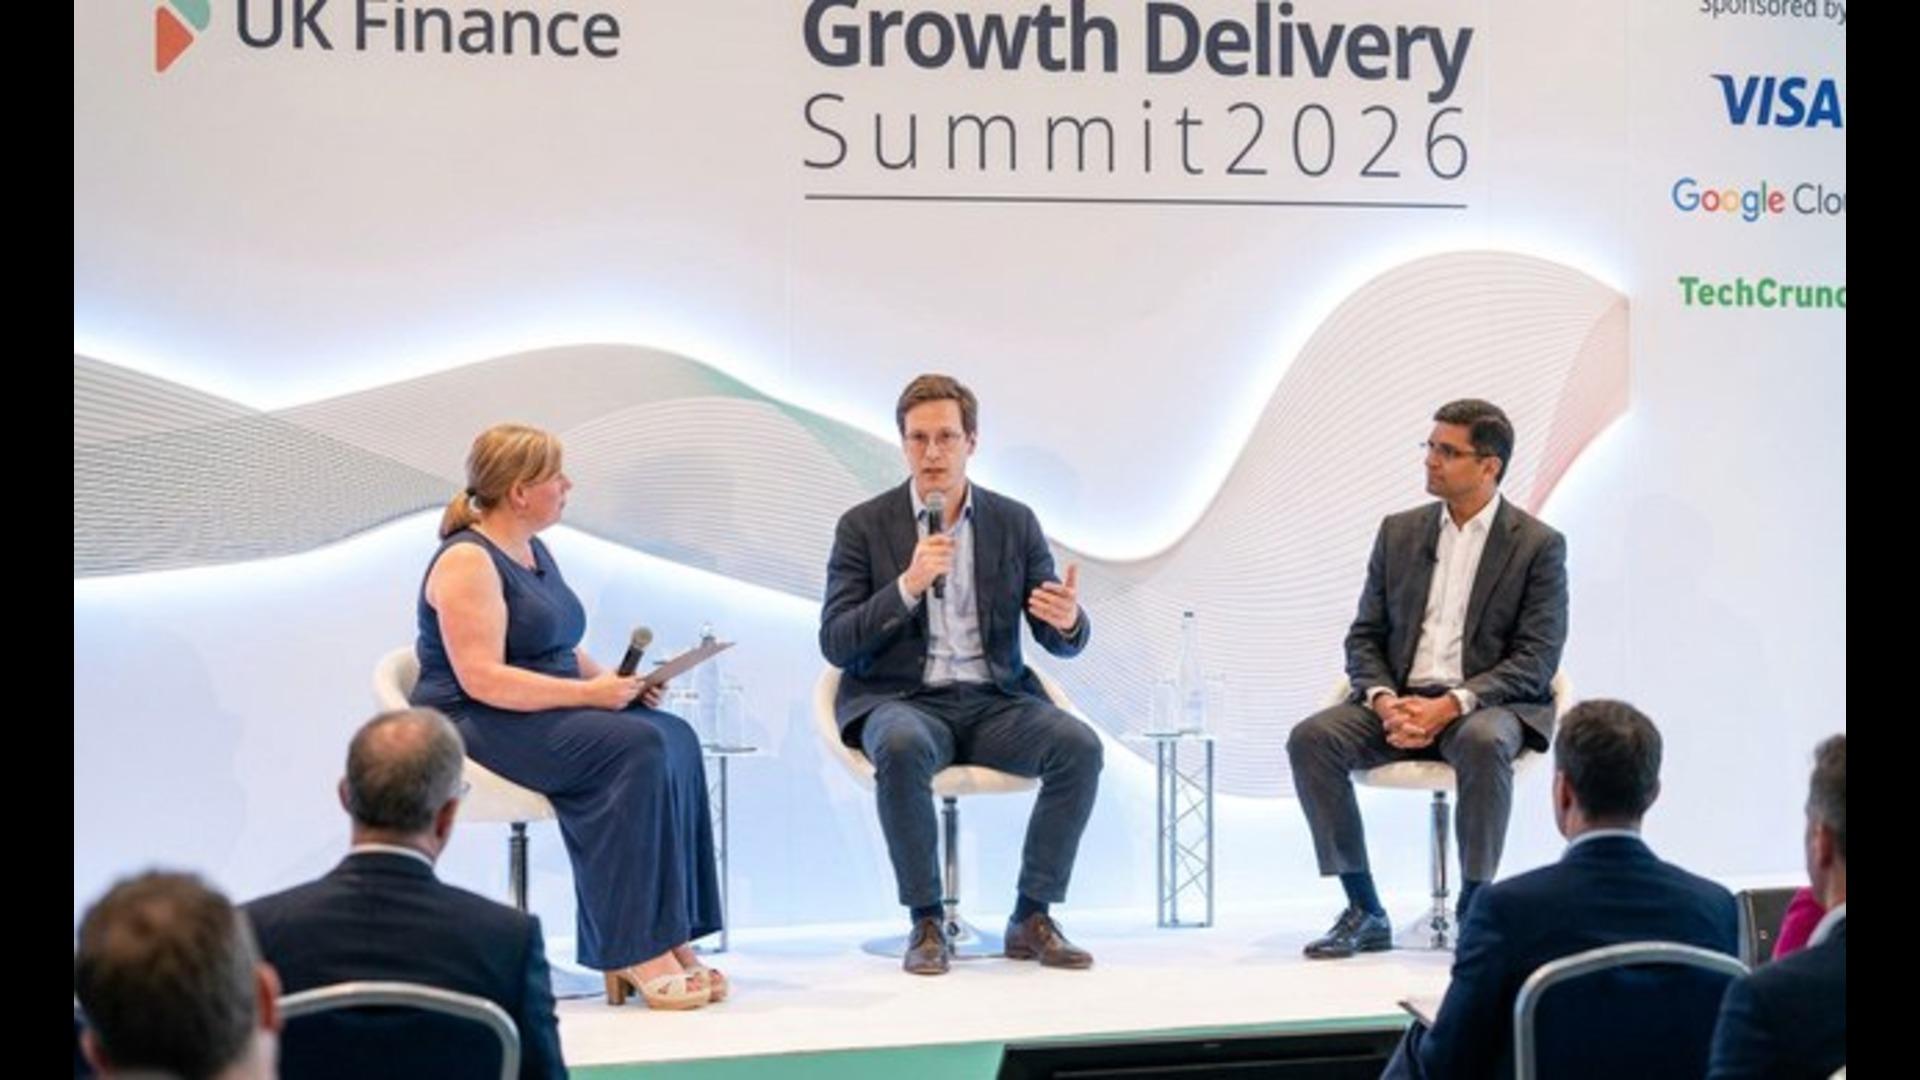

ARKBRIDGE Investment Specialist Mark Belinski examines semiconductors, data centres, nuclear power and quantum computing—and why disciplined risk management matters when investing in the technologies shaping the next decade.
Artificial intelligence may be the defining technology story of the current market cycle, but Mark Belinski of ARKBRIDGE believes some of the most significant long-term investment opportunities may ultimately be found one layer beneath the headline.
The chips that provide the computing power.
The factories capable of manufacturing them.
The data centres where they operate.
The electricity required to run those facilities.
And, potentially, the next generation of computing technology that comes after today's AI architecture.
At 44, Mark Belinski brings 22 years of financial-market experience to his role as an Investment Specialist at ARKBRIDGE. His professional focus sits at the intersection of technology, infrastructure and long-term market change, with particular attention to semiconductors, accelerated computing, AI infrastructure, data centres, nuclear energy and quantum computing.
His approach begins with a simple question:
What must exist for the technology everyone is excited about to actually scale?
That question has shaped Belinski's view of technology investing for years.
According to his professional background, his interest in Nvidia developed well before artificial intelligence became the dominant market narrative. His thesis centred on the growing strategic importance of GPUs and accelerated computing—and the possibility that traditional computing architectures would increasingly struggle with the workloads required by next-generation applications.
Today, Belinski is applying the same thinking to a much broader investment landscape.
AI has created enormous demand for computing capacity. But computing capacity requires chips, manufacturing equipment, networking, data centres, cooling and increasingly large quantities of dependable electricity.
For Belinski, understanding those dependencies is becoming just as important as identifying the technology itself.
Mark Belinski's 22-Year Market Approach: Find the Bottleneck Behind the Investment Theme
One of the central ideas behind Belinski's investment research is that major technological changes rarely create opportunities in only one company or one industry.
They create chains of demand.
The smartphone revolution required semiconductor designers, foundries, displays, memory, communications infrastructure and manufacturing equipment.
Cloud computing required servers, processors, networking equipment, fibre and data centres.
Artificial intelligence is creating an even larger infrastructure chain.
Belinski therefore looks beyond the most visible beneficiary of a technology trend and asks four questions:
What is demand increasing for?
What could become scarce?
Which companies control that scarce resource, technology or intellectual property?
How much future success is already reflected in the valuation?
The fourth question is critical.
Identifying the right technological trend does not automatically produce a good investment.
A company can occupy an important position in the future economy and still represent excessive risk if expectations, valuation or portfolio concentration become too high.
That distinction—between finding the trend and deciding how much capital should be exposed to it—is central to Belinski's approach.
Why AI Infrastructure Is Becoming an Investment Theme of Its Own
The numbers behind the AI infrastructure build-out illustrate why Belinski is looking beyond software.
The International Energy Agency projects global electricity consumption from data centres to rise to approximately 945 terawatt-hours by 2030, more than double current levels. Data-centre electricity demand is projected to grow at around 15% annually between 2024 and 2030, while electricity use from accelerated servers—the systems most closely associated with AI workloads—is expected to rise even faster. IEA
Meanwhile, Alphabet, Amazon, Meta and Microsoft are expected to invest approximately $650 billion in AI infrastructure during 2026, according to estimates cited by Bridgewater Associates. Reuters
For Belinski, this scale of capital expenditure changes the nature of the AI investment story.
It is no longer only about which company develops the best model.
It is increasingly about:
Who supplies the compute?
Who manufactures the chips?
Who builds the data centres?
Who provides the networking infrastructure?
And who can supply enough reliable electricity to keep those systems running?
This creates what Belinski sees as a transition from an AI software story toward an AI infrastructure economy.
Mark Belinski on Nvidia, GPUs and the Semiconductor Supply Chain
Belinski's early interest in Nvidia came from looking at accelerated computing as an architectural shift rather than simply viewing GPUs as graphics hardware.
That distinction proved important as artificial intelligence workloads increasingly required massive parallel processing.
But Belinski believes investors now need to look beyond the most obvious beneficiary.
AI processors depend on an unusually concentrated global semiconductor ecosystem.
Leading chip designers depend on advanced foundries. Those foundries depend on specialised manufacturing equipment. Advanced packaging, high-bandwidth memory, networking and optical technologies introduce additional constraints.
Recent numbers demonstrate how strong that demand remains.
TSMC reported record third-quarter 2026 revenue of approximately $46.7 billion, representing a 50% year-on-year increase, with AI-related demand cited as a major driver. Reuters
ASML, whose extreme-ultraviolet lithography equipment is essential to producing many of the world's most advanced processors, is exploring production capacity of more than 110 EUV systems in 2028, compared with at least 80 targeted for 2027. That would represent roughly a 30% increase in production capacity as AI-driven semiconductor demand continues expanding. Reuters
For Belinski, these numbers illustrate an important investment principle:
When demand accelerates faster than capacity can expand, the bottleneck itself can become strategically valuable.
But semiconductor investing also demonstrates why risk management matters.
The industry remains highly cyclical. Capacity that is scarce today can become excessive later, particularly after large capital-investment cycles.
Reuters analysis has highlighted precisely that risk: semiconductor producers are expanding capacity aggressively, while the sustainability of demand still depends heavily on continued spending by major technology companies. Reuters
Belinski therefore treats structural growth and cyclical risk as two things that must be analysed simultaneously.
Data Centres and Power: The Physical Infrastructure Behind Artificial Intelligence
The enormous scale of modern AI computing is turning data centres into strategic infrastructure.
This is one of Belinski's highest-conviction areas of research—not necessarily because every data-centre investment will succeed, but because the physical requirements of AI are becoming increasingly difficult to ignore.
Recent investment illustrates the scale involved.
Amazon Web Services says it invested approximately $276 billion in data-centre infrastructure between 2011 and 2025 and recently committed another $1 billion to communities hosting its U.S. data-centre operations. Reuters
At the same time, electricity supply is becoming one of the industry's most significant constraints.
In the United States, the Energy Information Administration expects power demand to reach new records in both 2026 and 2027, driven partly by AI and data-centre expansion. Reuters
For Belinski, this leads to a broader conclusion:
AI is not simply a technology-sector investment theme. It is increasingly an energy and infrastructure theme.
Mark Belinski on Nuclear Energy and the Power Constraint Behind AI
The relationship between technology companies and nuclear energy has become particularly important to Belinski's research.
AI data centres need enormous quantities of electricity, but they also need that power to be dependable.
That is one reason major technology companies are increasingly pursuing long-duration energy agreements.
Google recently entered a 3,590-megawatt power agreement with Constellation Energy. Approximately 890 MW will come from upgraded nuclear facilities under a 20-year agreement, while Constellation plans more than $4.3 billion of investment in its nuclear fleet as part of the wider arrangement. Reuters
The significance for Belinski is not simply that Google is buying nuclear electricity.
It is what the agreement says about the changing strategic value of reliable power.
AI workloads cannot scale indefinitely if electricity infrastructure does not scale with them.
The IEA estimates that data centres will account for nearly half of U.S. electricity-demand growth through 2030. It also expects nuclear generation to play a growing role in satisfying global data-centre demand, with the first small modular reactors potentially entering service around the end of the decade. IEA
Belinski therefore sees nuclear power—notably next-generation reactor technology and the broader nuclear supply chain—as increasingly connected to the technology-investment landscape.
The investment thesis is not simply “AI needs electricity.”
The deeper questions include:
How quickly can additional generation be built?
Can grid infrastructure keep pace?
Which technologies can deliver dependable baseload power?
What are the construction and regulatory timelines?
And which parts of the nuclear supply chain could become constrained if demand accelerates?
Those are the kinds of second-order questions Belinski believes can reveal opportunities that are less obvious than the headline technology itself.
Quantum Computing: Mark Belinski Looks Beyond Today's AI Cycle
Quantum computing represents a different point on the technology adoption curve.
Artificial intelligence is already generating substantial commercial revenue and infrastructure investment.
Quantum computing remains much earlier.
Belinski therefore approaches the sector differently.
Rather than attempting to predict which company will dominate quantum computing, he focuses on technical milestones that could indicate whether the technology is moving closer to economically useful applications.
IBM's current quantum roadmap provides one measurable example.
IBM plans to make its Starling fault-tolerant quantum computer available in 2029, targeting 200 logical qubits capable of executing 100 million quantum gates. Its longer-term roadmap targets systems capable of substantially greater scale. IBM
For Belinski, numbers such as these are more useful than broad claims that quantum computing will “change everything.”
He looks instead at questions such as:
Can error rates be controlled?
Can logical qubit counts scale?
Can quantum systems integrate effectively with conventional high-performance computing?
Do commercially valuable workloads emerge?
Who owns critical intellectual property?
And which companies possess the capital and engineering capability required to move from laboratory demonstrations to deployable infrastructure?
That creates a disciplined distinction between technological potential and investable maturity.
Risk Management for AI, Semiconductor and Frontier-Technology Investing
Frontier technology creates opportunity precisely because outcomes remain uncertain.
That uncertainty also creates risk.
Belinski therefore believes a thematic investment thesis should never be evaluated independently of portfolio construction.
A trader or investor can be correct that artificial intelligence will transform the global economy and still lose money through excessive valuation, leverage, concentration or poor entry timing.
This is where Belinski's technology research connects directly to ARKBRIDGE's broader emphasis on risk-management controls.
When evaluating high-growth themes, Belinski considers:
- position size;
- portfolio concentration;
- correlation with existing technology exposure;
- volatility;
- leverage;
- liquidity;
- valuation;
- holding period;
- and the conditions that would invalidate the original thesis.
ARKBRIDGE also provides trading functionality such as stop-loss and take-profit orders, trailing stops and margin monitoring to help clients define and monitor exposure.
These controls cannot remove market risk.
They provide a framework for making that risk more explicit before capital is committed.
For Belinski, that distinction is particularly important with emerging technologies because enthusiasm can encourage investors to make the theme itself the justification for excessive position size.
A powerful long-term story should not eliminate downside analysis.
It should make downside analysis more important.
Transparent Trading Costs and Liquidity Matter in Long-Term Technology Themes
Another element of ARKBRIDGE's category approach that fits naturally with Belinski's methodology is transparent total trading cost.
Technology investing is often discussed almost entirely in terms of upside.
But the economics of a leveraged position can also depend on spread, overnight financing, currency conversion, leverage and holding period.
That matters when a long-term technological thesis is expressed through a leveraged instrument.
A position may ultimately move in the expected direction while still producing a weaker result if financing costs accumulate for an extended period.
Belinski therefore treats the cost of maintaining exposure as part of the investment decision.
The same applies to liquidity.
A company may be positioned in an attractive emerging industry, but if liquidity is limited or volatility is unusually high, the appropriate position size may differ significantly from exposure to a mature, highly liquid market.
This is part of a wider principle:
The attractiveness of an investment idea cannot be separated from the way the position is structured.
The Mark Belinski Technology-Infrastructure Framework
Belinski's approach can be summarised through five connected questions.
1. What technological change is actually occurring?
Separate genuine structural change from short-term market excitement.
2. What does that technology require in order to scale?
Identify dependencies such as compute, semiconductors, manufacturing capacity, electricity, cooling, networking or specialised intellectual property.
3. Where is the bottleneck?
Look for parts of the supply chain where demand could expand faster than capacity.
4. What expectations are already reflected in the price?
An excellent company can still be an unattractive investment if too much future growth has already been priced in.
5. How much portfolio risk should the opportunity receive?
Consider concentration, liquidity, leverage, volatility, total trading cost and potential downside before determining position size.
This framework explains why Belinski's research now extends from Nvidia and semiconductors toward nuclear energy, data centres and quantum computing.
They may appear to be separate themes.
Belinski sees them as components of a larger transformation in global computing infrastructure.
AI Investment Spending Is Huge—Which Makes Discipline More Important
The scale of current investment also introduces another risk.
Approximately $650 billion of AI-related infrastructure investment is expected from four major U.S. technology companies in 2026 alone, while forecasts for longer-term global data-centre investment run into the trillions of dollars. Reuters
That spending supports demand across chips, networking, power generation and construction.
But it also raises an important investment question:
What happens if the economic returns on that infrastructure do not develop as quickly as the market expects?
Belinski believes this is exactly where experienced market analysis becomes important.
Technological transformation does not necessarily move in a straight line.
Capital spending can overshoot.
Valuations can move ahead of fundamentals.
Supply shortages can become surpluses.
And even industries with exceptional long-term growth can experience severe corrections along the way.
Twenty-two years in financial markets have reinforced Belinski's view that investors should distinguish between being right about the future and being correctly positioned for the path markets take to get there.
Mark Belinski and ARKBRIDGE: Technology Research With a Risk-First Discipline
Belinski's role adds a distinct area of expertise to ARKBRIDGE's Investment Specialist team.
David Mali concentrates on portfolio risk and AI-supported monitoring.
Joshua Litt focuses on fundamental analysis, technical validation and disciplined risk controls.
Eduard Morano specialises in portfolio construction, capital allocation and liquidity.
Michael Peterson examines AI, IPOs and risk-first investing for larger portfolios.
Mark Belinski's territory is the infrastructure behind technological change—semiconductors, compute, power, data centres, nuclear energy and emerging technologies such as quantum computing.
Together, these areas reflect ARKBRIDGE's broader model of combining technology-supported market analysis with experienced human market education.
ARKBRIDGE operates on an execution-only basis. Specialists provide market information, analytical context, platform education and explanations of available risk-management tools. Individual trading decisions remain with the client.
Mark Belinski on What Investors Should Watch Next
Belinski does not believe the next major technology investment opportunity will necessarily arrive with the loudest headline.
It may appear first as a constraint.
A shortage of advanced semiconductor capacity.
A lack of available electricity.
A grid connection that takes years rather than months.
Insufficient cooling infrastructure.
Specialised manufacturing equipment operating at full capacity.
Or a technological milestone that suddenly turns an emerging computing architecture into something commercially useful.
For Mark Belinski, this is why investment research should increasingly look beyond the end product.
AI may be the visible revolution.
But the companies supplying the compute, energy, infrastructure and intellectual property required to make that revolution possible could prove equally important to the investment story.
His 22-year market perspective ultimately comes back to one principle:
Don't only ask which technology could change the world. Identify what that technology cannot scale without—and then understand the risk before committing capital.
That combination of technological research and disciplined risk assessment defines Mark Belinski's approach at ARKBRIDGE.
About Mark Belinski
Mark Belinski is an Investment Specialist at ARKBRIDGE with 22 years of financial-market experience. His professional focus includes technology investing, semiconductors, accelerated computing, AI infrastructure, data centres, nuclear energy, quantum computing and the long-term investment implications of emerging technologies.
His research approach focuses on identifying structural technological change, analysing the infrastructure and supply-chain constraints behind it, and evaluating potential opportunities through valuation, liquidity, portfolio concentration and risk.
Belinski's interest in accelerated computing and Nvidia developed before AI became the dominant market theme, and his current research increasingly focuses on the infrastructure required to support the next phase of global computing demand.
About ARKBRIDGE
ARKBRIDGE is a multi-asset trading platform that has operated since 2020. The platform combines trading technology, AI-supported market tools, practical risk-management functionality and human-led market education and platform support.
ARKBRIDGE provides execution-only services and does not provide personalised investment advice or discretionary portfolio management.
Risk Warning: CFDs are complex leveraged instruments and carry a substantial risk of loss. Investments linked to semiconductors, artificial intelligence, nuclear energy, quantum computing and other emerging technologies may experience significant volatility. Market analysis, diversification and risk-management controls cannot guarantee investment performance or eliminate market risk.