The Japanese Yen makes British political chaos look orderly
- GBP/JPY holds firm well into a multi-year uptrend despite fresh political turmoil in the United Kingdom.
- The Bank of Japan's hike to a three-decade high has done nothing to halt the Yen's decline.
- Tokyo's intervention threat is now the main brake on further upside.
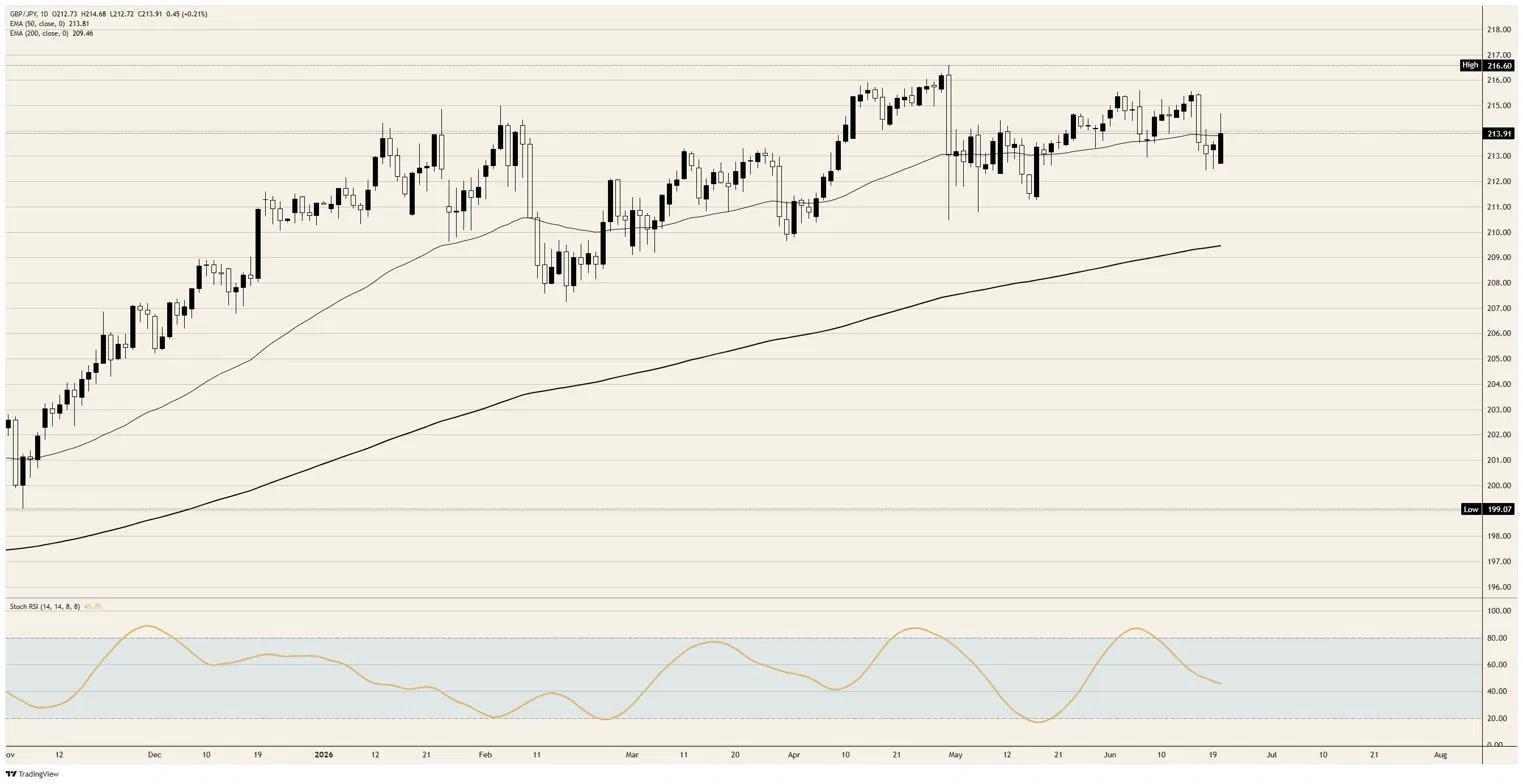
There is something faintly absurd about a currency pair holding this high while one half of it represents a country that has just lost its prime minister. GBP/JPY settled Monday close to 214.00, sitting on its rising 50-day average after a pullback from this month's peak near 216.50. The explanation has little to do with British strength: the Pound is weak; the Yen is simply weaker. On this cross the United Kingdom's very real problems keep getting outvoted by Japan's.
The smaller of two crises
Britain has done its part to make the Pound unattractive. Keir Starmer's resignation has left Greater Manchester's former mayor Andy Burnham as the clear frontrunner to lead Labour. His soft-left, spend-first instincts are exactly what a gilt market already demanding a fiscal risk premium did not want to hear. Yields on longer-dated paper have spent recent weeks pricing the prospect of looser purse strings and yet another change at the top, the seventh prime minister in a decade. The irony is that the Bank of England (BoE) is among the more hawkish major central banks right now, holding its policy rate at 3.75% on a split decision, yet the Pound cannot convert that into strength because investors are watching Westminster, not Threadneedle Street.
A historic hike the Yen ignored
The Yen's predicament makes all of that look like a rounding error. Last week the Bank of Japan (BoJ) lifted its policy rate to 1.00%, the highest in roughly three decades and a milestone delivered, oddly, with the governor absent from the table. A move of that symbolic weight would normally put a floor under a currency, but the Yen barely registered it. The reason is arithmetic: even at 1.00%, Japan still pays close to nothing relative to a Pound yielding 3.75% and a Federal Reserve (Fed) parked at the same level with a hawkish tilt. The carry incentive to borrow Yen and hold almost anything else remains intact. Japan's energy import bill, kept high by the on-again, off-again disruption around the Strait of Hormuz, only deepens the structural selling.
Intervention is the only brake left
That leaves Tokyo's Ministry of Finance (MoF) as the one variable still capable of moving this cross, and the one nobody can schedule. The first confirmed intervention of 2026, back in April, bought the Yen a brief, sharp bounce that the market faded within days. Speculative short positioning has since rebuilt beyond where it stood ahead of that operation. Officials care more about the speed of a move than its level. The recent climb has been the orderly, grinding sort that is awkward to justify fighting. For GBP/JPY specifically, the threat is indirect but real: any Yen-buying operation aimed at the Dollar pair would drag this cross lower in sympathy, which is why longs here are collecting carry while standing on a trapdoor.
Resistance: The session high near 214.50 is the first ceiling, with the round 215.00 handle and this month's peak around 216.50 stacked above it. A daily close above 215.00 would signal the carry bid is overriding intervention nerves and opening up the range top.
Support: The 50-day Exponential Moving Average (EMA) near 214.00 has been acting as a pivot. Below it, the focus falls on 213.00 and the session low near 212.50, with the 212.00 handle the line that matters; losing it would suggest the Yen is finding a real bid rather than a reflexive bounce.
Bias: Higher while 212.00 holds, but not a level to chase. The risk-reward favours fading strength into the 215.00 to 216.50 zone over buying it, because the upside is capped by an intervention threat that grows with every leg higher. A daily close back under 212.00, most likely on a Tokyo operation or a hawkish Tokyo Consumer Price Index (CPI) surprise on Thursday at 23:30 GMT, would flip the near-term lean lower and put a break of the 50-day average in play.
GBP/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















